
KAWS Bottle Launch Might Change The Case For Investing In Pernod Ricard (ENXTPA:RI)
- Absolut Vodka, part of Pernod Ricard, has released a past Artist Edition bottle with contemporary artist KAWS, featuring his XX motif, CHUM character, and artwork-inspired design on the iconic apothecary-shaped bottle.
- The KAWS collaboration highlights Pernod Ricard’s focus on higher value brand experiences, using art-led packaging to refresh consumer interest in a core premium vodka product.
- We will now explore how Pernod Ricard's investment narrative could be influenced by the KAWS-led Absolut Artist Edition branding push.
Scan how Pernod Ricard’s art-led Absolut move compares with other consumer brands by reviewing 616 high quality undiscovered gems that may be building similar under the radar brand equity plays.
Pernod Ricard Investment Narrative Recap
To own Pernod Ricard, you need to believe that premium spirits, disciplined cost programs, and selective brand building can matter more than near term softness in key geographies. The short term swing factor remains execution on earnings and margin guidance while the business faces weaker demand in markets like the U.S. and China and a tougher pricing backdrop.
The biggest risk today is pressure on profitability from regulation, taxes, FX and a moderation trend that can hit volumes and premium tiers at the same time. The Absolut x KAWS release looks more like incremental brand maintenance than a material shift for near term revenue or margins.
The Absolut KAWS Artist Edition sits neatly inside Pernod Ricard’s push toward higher value, experiential brands. This is one of the main long term levers analysts focus on. It aligns with the premiumization and innovation narrative that underpins current analyst expectations for earnings growth of 8.62% a year and margin improvement from 12.8% to 16.0% by 2029.
For you as a shareholder, the real question is less about this one bottle and more about repetition and scale. If the group can keep rolling out similar value adding concepts across vodka, whiskey and ready to drink formats, it may support pricing power and help offset weaker volumes or FX headwinds, while cost savings and portfolio reshaping do the heavier lifting on margins.
Pernod Ricard's current analyst story points to revenues of €9.8 billion and earnings of €1.6 billion by 2029. That profile rests on 1.5% yearly revenue growth and an earnings increase of about €400 million from the current €1.2 billion base.
Uncover why Pernod Ricard's fair value indicates a 39% potential upside to its current price before that discount narrows.
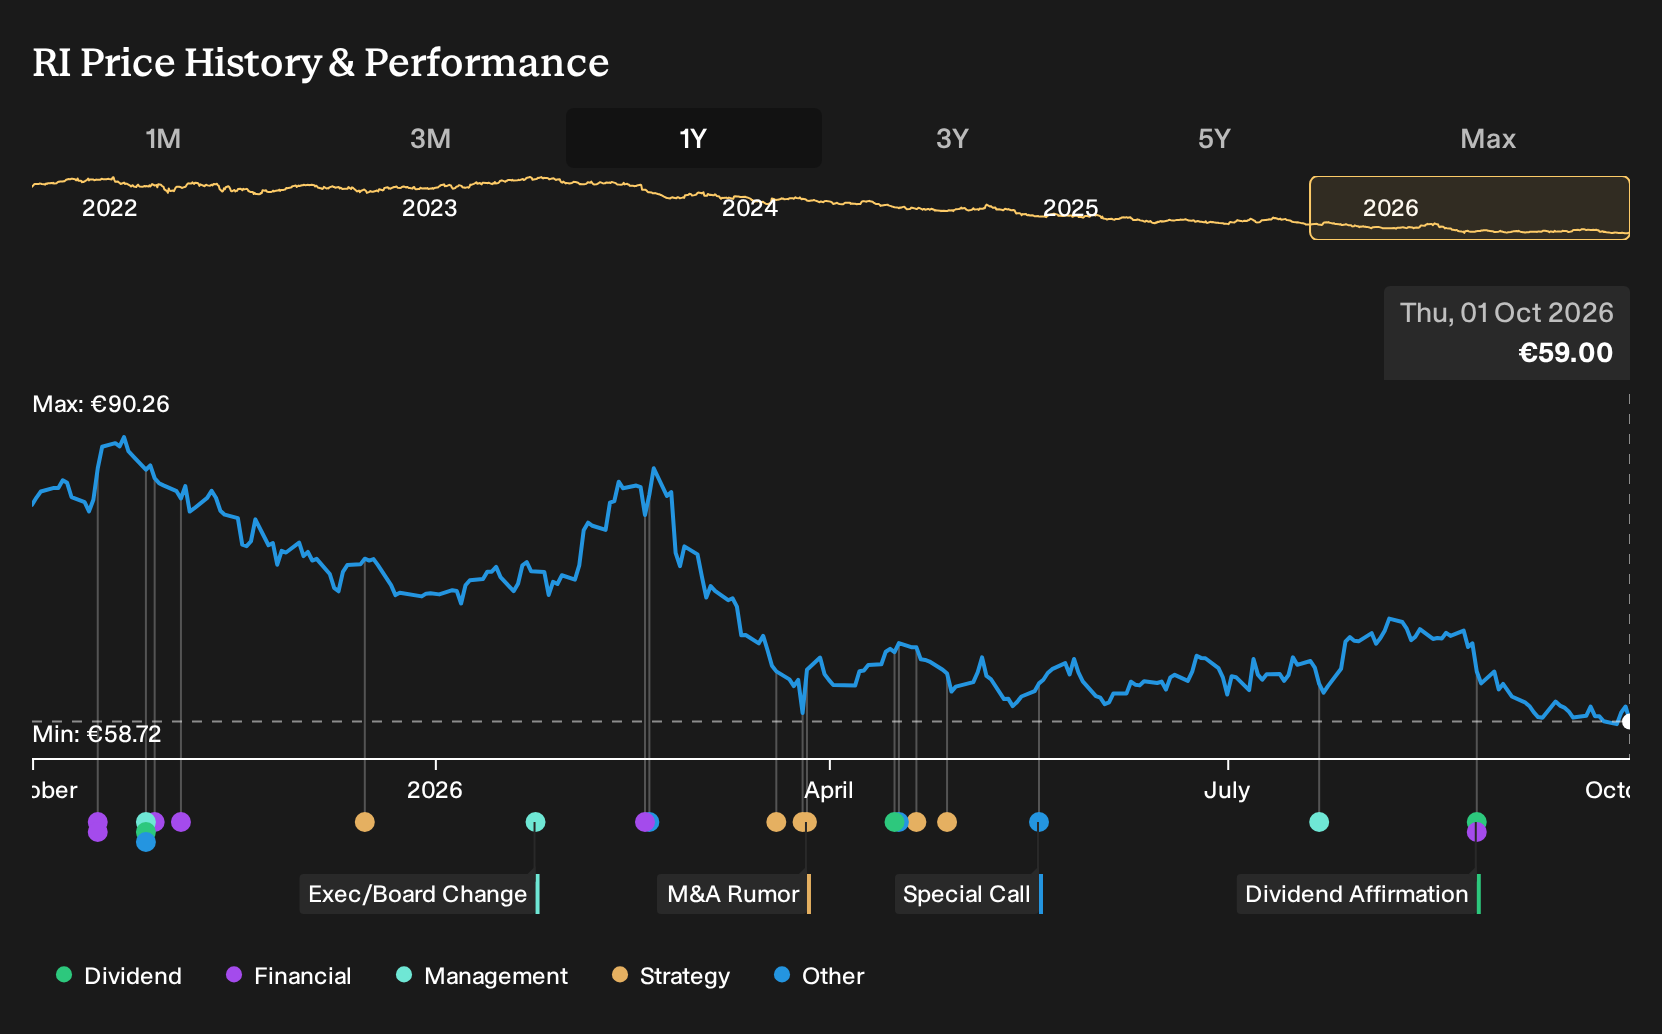
Exploring Other Perspectives
One alternate view on Pernod Ricard leans hard into the cost story. The most optimistic analysts were already pencilling in €11.6b of revenue and €2.0b of earnings by 2029, built on bigger efficiency gains and richer product mix. A KAWS driven Absolut push could either support that thesis or prompt fresh revisions.
Explore 5 other Pernod Ricard fair value estimates, including one that suggests as much as 159% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Pernod Ricard research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pernod Ricard. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pernod Ricard's overall financial health at a glance.
Looking for more Pernod Ricard style investment ideas?
If Pernod Ricard's mix of brands, cash generation and long term compounding appeal to you, it can help to widen the lens and see how other businesses score on quality, balance sheet strength and income potential using the Simply Wall St Screener.
- If you care most about long term quality at a reasonable entry point, review a curated set of attractively priced compounders through 189 high quality undervalued stocks.
- If resilience matters more than excitement for your portfolio, filter for companies with stronger financial footing and cleaner balance sheets using the list of solid balance sheet and fundamentals (207 results).
- If dependable income is near the top of your checklist, focus on stocks with higher yields and more robust payout profiles via the 157 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com