
3 Nuclear Stocks With Revenue Growth Over 8%
Bond yields have surged to levels last seen in the dot-com era, and higher borrowing costs are squeezing every energy project that depends on cheap debt. Reliable electricity for AI data centers and climate goals still needs to be built, yet capital is suddenly more expensive and selective. That is where this long term clean power theme comes in. This article breaks down three stocks filtered for this new reality.
The stocks highlighted below are just a sample of the theme, and the full screen surfaced 16 more companies with equally compelling nuclear infrastructure stories that are not covered here. If you want to identify your own high-conviction candidates around this nuclear power buildout, head straight to the Nuclear Renaissance screener.
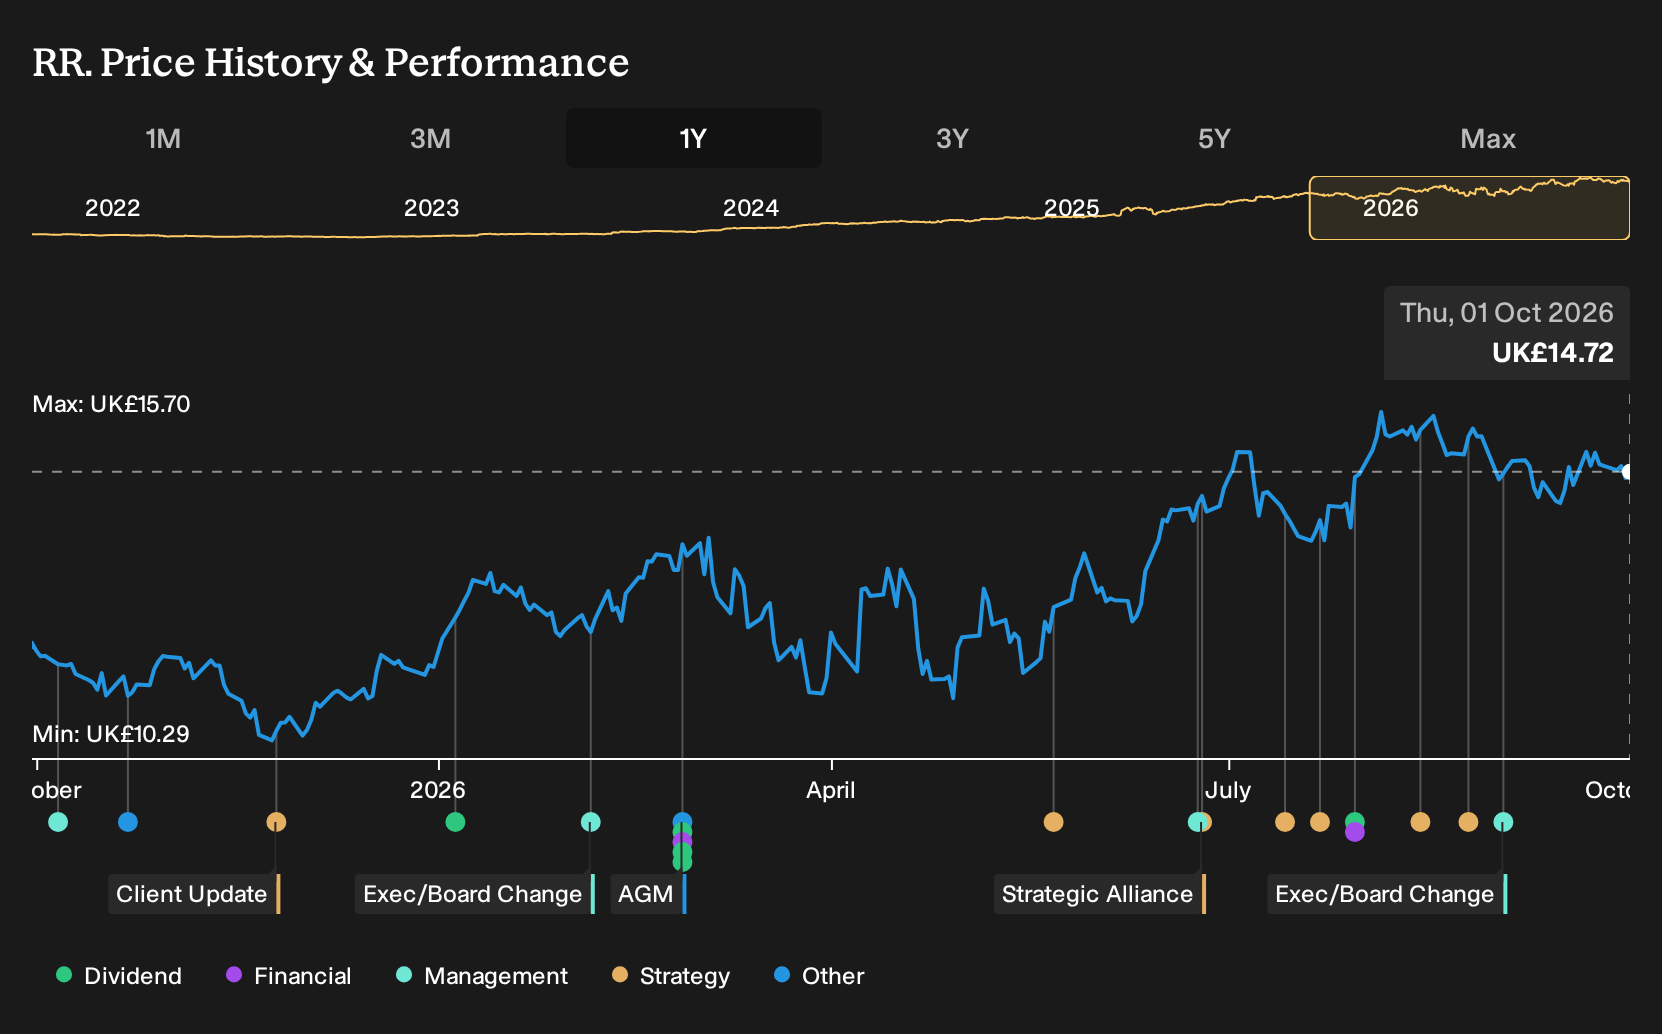
Rolls-Royce Holdings (LSE:RR.)
Rolls-Royce Holdings builds and services mission critical power systems worldwide, from large civil aero engines to defence propulsion and onsite mtu power solutions, with about £11.8b from Civil Aerospace, £5.5b from Power Systems and £5.0b from Defence, and an equity value near £122.1b tying substantial scale to its nuclear linked work.
Rolls-Royce Holdings brings a different angle to the Nuclear Renaissance theme, since its nuclear propulsion and SMR work sit inside a much broader aero engine and power solutions group rather than a pure play reactor builder.
"A significant portion of current narrative and valuation appears premised on Power Systems segment growth, especially the data center power generation boom, continuing at near-peak rates (20%+ per year) as cloud and AI infrastructure expand."
What happens to that carefully balanced thesis if a single pressure point subtly shifts the profit mix that is doing most of the heavy lifting?
If that mix is what really moves the needle, read the full narrative for Rolls-Royce Holdings to see how the nuclear and aero engines story could be decoupling under the surface.
Cameco (TSX:CCO)
Cameco is one of the clearest pure plays on nuclear fuel in this theme, supplying uranium and related services that keep gigawatt scale reactors running for AI data centers and grid decarbonisation efforts.
Cameco Corporation produces uranium concentrate for nuclear utilities and runs fuel services and Westinghouse reactor technology operations, with CA$2.9b from Uranium, CA$551 million from Fuel Services and CA$3.4b from Westinghouse reported against unallocated adjustments, and a market value near CA$53.1b.
"Momentum in utility contracting is building, but current volumes are subdued; as uncovered utility uranium needs through 2045 accumulate, the eventual surge in term contracting is expected to drive material price and volume upside, improving both Cameco's revenue growth and pricing power (with likely gains to net margins)."
For investors, everything hinges on how that still latent shift in long term contracting filters through to future pricing power and profitability.
That hinges on how far contracting momentum really goes, so read the full narrative for Cameco to see how Cameco’s pricing power and risk profile could be shifting.

Bird Construction (TSX:BDT)
Bird Construction ties into the Nuclear Renaissance theme through its role as a contractor on nuclear and power projects, while still earning most of its CA$3.7b in general contracting revenue from a broad mix of Canadian infrastructure work, and carries a market value near CA$4.5b.
Bird Construction gives this theme a different angle, because it is not a pure nuclear operator but a builder that helps turn new reactors, power upgrades, and grid connections into physical assets that can feed AI era electricity demand.
"Accelerating demand for energy transition and green building projects, including nuclear, LNG, wind, hydro, and sustainable/LEED-certified facilities, is resulting in higher-margin, specialized contracts."
What really matters from here is how one quietly growing slice of that contract mix ultimately reshapes Bird Construction’s overall profitability profile.
That quiet shift in mix is the real story, and the full narrative for Bird Construction shows how accelerating energy transition work could reshape Bird Construction’s risk and reward profile.

Seeking Fresh Alternatives Before They Fly
Some of the sharpest breakouts start quietly, then momentum builds and prices move before most investors even look. Scan these fresh ideas while they are under the radar for now and consider them while they are still early in their move.
- Target reliable cash generators with defensible balance sheets by scanning the list of solid balance sheet and fundamentals (9 results), which is curated to highlight businesses that can keep funding growth even when conditions get tougher.
- Hunt for income that keeps working while prices move around by reviewing the 1 dividend fortresses and see which high-yield payers still appear supported by their underlying cash flows.
- Position ahead of potential infrastructure and electrification trends by running through the 39 power grid technology and infrastructure stocks focused on companies involved in building and maintaining critical grid hardware.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com