
Alkermes (ALKS), What Is Behind The Fresh Attention?
Alkermes (NasdaqGS:ALKS) is back on investors’ radar after releasing phase 1 proof of concept data for ALKS 7290 in adults with ADHD, showing clinically meaningful symptom improvements and supportive safety findings.
Recent trading tells a mixed story for Alkermes. The share price is around $40.54, with a 30 day share price return down 14.11% and a 90 day move lower by 25.72%. Yet the year to date share price return is up 43.45% and the 1 year total shareholder return sits at 29.69%, suggesting longer term holders have still seen gains even as short term momentum has cooled around this latest clinical update.
Capitalize on the renewed attention around Alkermes by scanning a curated set of biopharma peers with strong fundamentals and potential price dislocations using the 28 high quality undervalued stocks.The recent pullback in Alkermes after upbeat ALKS 7290 data raises a simple tension. Are investors reassessing the underlying ADHD opportunity, or just cooling on a previously strong run? And what does that mean for valuation next?
Most Popular Narrative: 27.6% Undervalued
On Simply Wall St's most followed narrative, Alkermes screens as materially below an implied fair value of $56 compared with the last close at $40.54. This puts the current pullback in a very different light to the recent price action.
The company is benefitting from margin expansion efforts and cost discipline, seen in lower cost of goods sold post divestiture of lower margin manufacturing operations. Together with growing proprietary product sales, this is driving higher net margins and increasing free cash flow generation. Alkermes' strong cash position, lack of debt, and opportunistic share repurchase authorization provide financial flexibility to accelerate pipeline programs, pursue external growth options, and support sustained earnings growth while minimizing dilution risk to shareholders.
See why 9 investors see Alkermes as 28% undervalued.
Result: Fair Value of $56 (UNDERVALUED)
Still, the Alkermes story can change quickly if orexin trial data disappoints or if rising R&D and integration costs weigh more heavily on profitability.
Find out about the key risks to this Alkermes narrative.
Another View on Alkermes Valuation
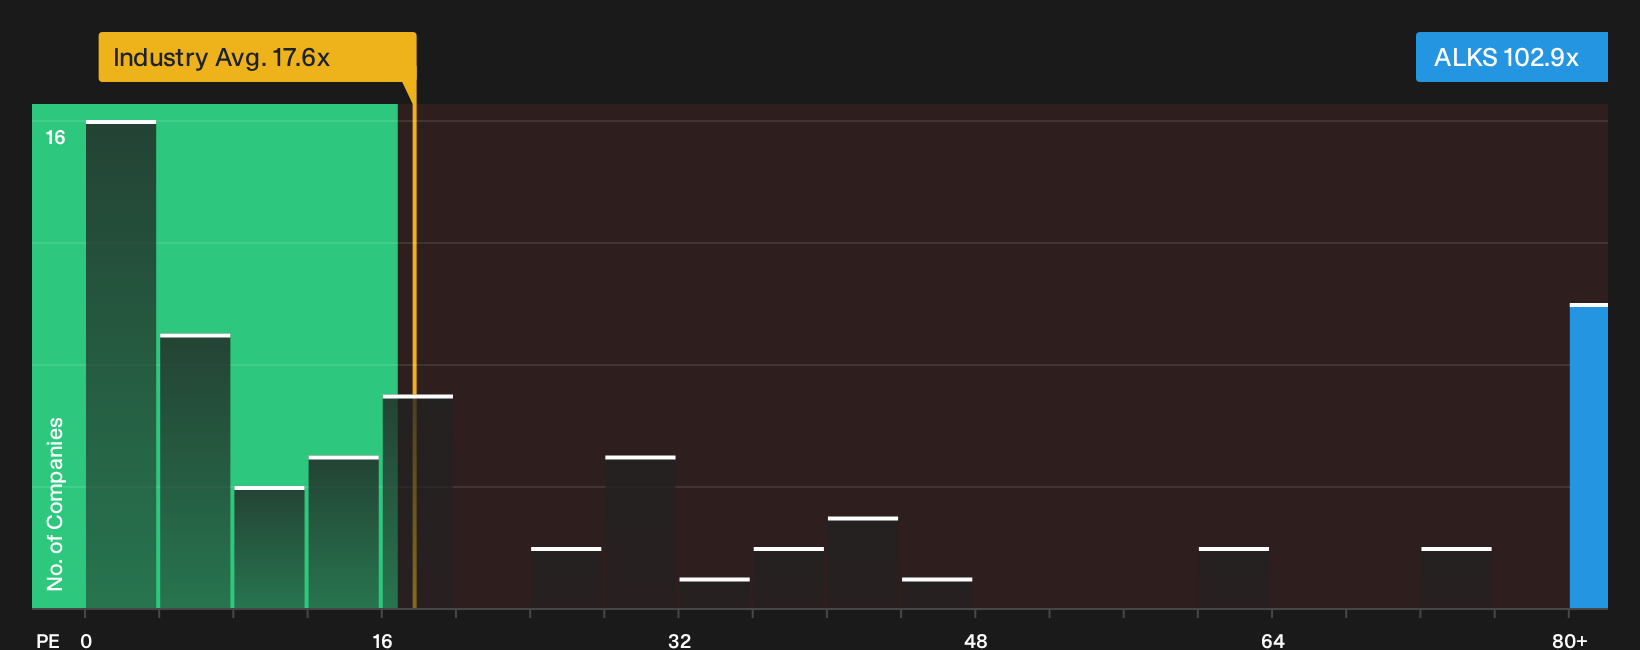
That 27.6% discount to a $56 fair value from the Alkermes narrative clashes with what the P/E multiple is saying. At roughly 102.9x earnings compared with a US Biotechs average of 17.6x and a fair ratio of 42.2x, the stock screens as expensive. Which signal matters more to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Alkermes can be useful if they push you to interrogate the data yourself and move decisively instead of drifting with headlines. To weigh the upside alongside the concerns, start with 2 key rewards and 3 important warning signs.
Looking for more Alkermes-sized opportunities?
Do not stop with Alkermes. Use the Simply Wall St Screener to surface fresh ideas, compare risk profiles, and pressure test where your next dollar should really go.
- Hunt for potential mispriced quality by scanning a curated 28 high quality undervalued stocks that match strong fundamentals with possible valuation gaps.
- Secure a steadier income stream by focusing on companies in our 7 dividend fortresses that pair meaningful yields with underlying financial strength.
- Prioritize resilience first by working through a 31 resilient stocks with low risk scores that filters for businesses with sturdier balance sheets and milder risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com