
Precision Drilling (TSX:PD) Could Be 21% Below Fair Value As Value Appeal Grows
Fresh analyst commentary has pushed Precision Drilling (TSX:PD) back into focus, as its P/E and P/B ratios compare favorably with peer averages, prompting investors to reassess the stock’s current valuation profile.
At around CA$118.74 per share, Precision Drilling has shown mixed near term momentum, with the 1-day share price return of 3.62% and 7-day gain of 0.94% sitting against a 30-day share price decline of 7.47%. The 1-year total shareholder return of 49.28% and 5-year total shareholder return of 119.40% indicate much stronger longer term performance and help explain why valuation signals are drawing fresh attention.
Scan beyond Precision Drilling and line up other value-focused candidates with our hand picked 5 high quality undervalued stocks that share stronger balance sheets and solid cash flow profiles.
After a strong 1-year run and a softer past month, Precision Drilling now sits at a valuation that some see as a second leg of upside rather than a finished story. Do the current multiples still point to room ahead?
Most Popular Narrative: 21% Undervalued
Against the last close of CA$118.74, the most followed narrative anchors Precision Drilling's fair value at CA$151.11 using a 7.2% discount rate, framing the current price as a discount to its modelled earnings and cash flow path.
Expansion of the upgrade program, including investments in digitalization, automation (Alpha rigs), and emissions-reducing EverGreen solutions, enabled by direct customer funding and premium pricing, should continue to drive higher margins and create near-term differentiation, also positioning the company to capitalize on the trend towards lower-emission drilling.
See why 18 investors see Precision Drilling as 21% undervalued.
On this view, Precision Drilling is treated as a business that is currently unprofitable but expected to grow into its valuation through higher margins and a more automated, lower emission rig fleet. The 7.2% discount rate, combined with revenue growth assumptions and margin expansion, produces a fair value that sits well above the present share price.
That set of assumptions leans heavily on the upgrade program, exposure to key North American gas basins, and the potential for share count to shrink over time. It also bakes in risks flagged in the same narrative, including high capital needs, concentrated exposure to Canada and the U.S., and a still meaningful debt load that keeps interest costs elevated.
Result: Fair Value of CA$151.11 (UNDERVALUED)
Still, the Precision Drilling story can crack if higher capital spending on rig upgrades fails to earn its keep, or if interest costs stay stubbornly heavy.
Find out about the key risks to this Precision Drilling narrative.
Another View: Precision Drilling Through A Sales Multiple Lens
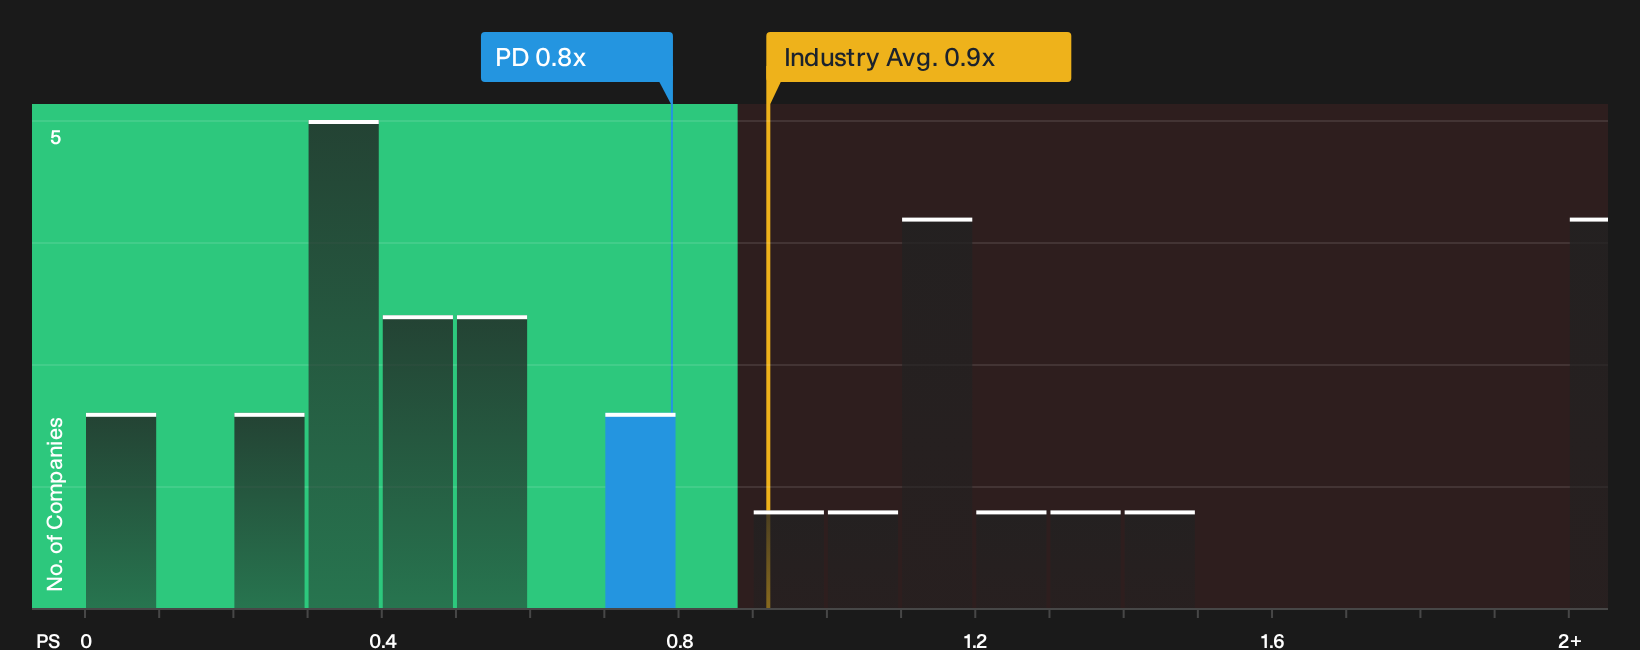
While the SWS DCF model points to strong upside for Precision Drilling, the simple sales multiple sends a cooler message. The stock trades on a P/S of 0.8x, slightly richer than direct peers at 0.7x, yet below the Canadian Energy Services group at 0.9x and under a fair ratio of 1x. That mix hints at some valuation cushion, but also less of a clear bargain on this measure. Which signal do you give more weight to?
For a closer look at how these pricing gaps stack up against the broader peer set and what that might imply for future re rating risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Precision Drilling's valuation can feel messy, so move quickly, review the numbers yourself, and weigh up the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Precision Drilling?
If Precision Drilling has your attention, do not stop there. Use the screener to quickly surface other opportunities that fit your risk, income, and quality preferences.
- Target fresh growth potential by scanning for under-the-radar opportunities through the 9 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Strengthen portfolio resilience by using the 9 resilient stocks with low risk scores to focus on businesses with more durable financial profiles and lower overall risk scores.
- Anchor your research around quality finances by filtering for companies in the list of solid balance sheet and fundamentals (7 results) with healthier leverage and fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com