
Will Asset Integration Savings Change Whitecap Resources Stock Narrative
- Whitecap Resources is reporting early operational benefits from integrating the Veren assets, including cost reductions and better capital efficiency across its oil and gas portfolio.
- The integration progress points to lower operating costs for Whitecap Resources, which may influence how investors view its cash generation profile.
- This article examines how Whitecap Resources' investment narrative may shift as Veren integration affects unit costs and capital efficiency.
Scan how Whitecap Resources' cost focused integration story compares with other cash generative operators by reviewing the hand picked 5 high quality undervalued stocks that combine stronger balance sheets with quality fundamentals.
Whitecap Resources Investment Narrative Recap
To own Whitecap Resources, you need to believe the integration of Veren keeps translating into structurally lower unit costs and better capital efficiency, not just a one quarter story. That is the key near term catalyst. The biggest swing factor remains commodity prices, because lower oil and gas benchmarks would quickly pressure margins and free cash generation.
The recent update on early cost savings looks supportive for the operational side, but it does not remove exposure to weaker well results or higher decline rates that could demand more capital just to hold volumes flat. Integration risk also lingers. Any execution slip could erode the very efficiency gains investors are watching.
Among the recent developments, the clearest link to the current news is the commentary that Veren integration is driving early operational synergies and lower operating costs. That is exactly what the latest update is reinforcing. If those savings prove durable, they can help offset softer net profit margins, which most recently sat at 19.7% versus 26% a year earlier.
This same integration push ties into Whitecap Resources shifting more spending toward Montney and Duvernay assets and leaning on advanced drilling designs and multilateral wells. Execution on that plan, combined with disciplined hedging and balance sheet management, will shape how resilient earnings look if commodity prices weaken or if drilling results fall short of expectations.
Whitecap Resources' current analyst storyline points to revenues of CA$8.2b and earnings of CA$1.5b by 2029, based on an assumed 4.2% yearly revenue growth rate and an earnings increase of about CA$100m from CA$1.4b today.
Uncover why Whitecap Resources' fair value indicates a 16% potential upside to its current price that could narrow quickly.
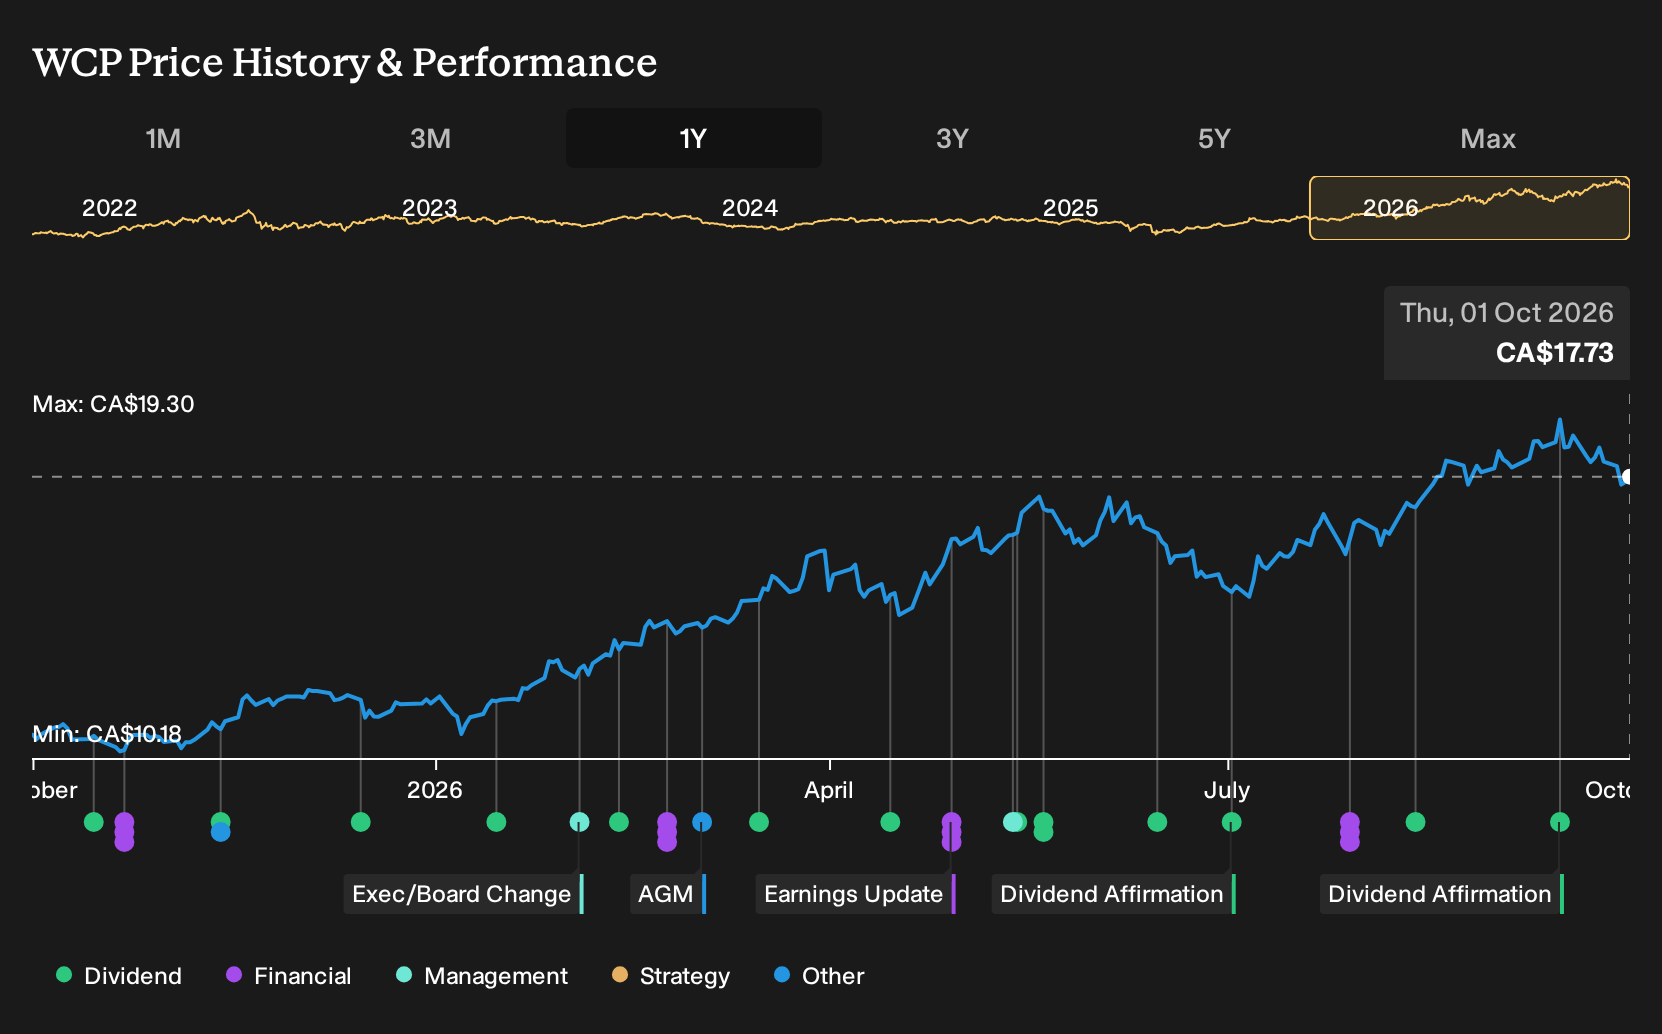
Exploring Other Perspectives
Some of the most optimistic analysts focus less on integration risk and more on Whitecap Resources hitting higher capacity at Kaybob. Before this news, the bullish camp was already pencilling in CA$9.0b of revenue and CA$2.4b of earnings by 2029. That is far above consensus, so it is worth comparing several viewpoints yourself.
Explore 5 other Whitecap Resources fair value estimates, including one that suggests up to 150% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Whitecap Resources research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Whitecap Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Whitecap Resources' overall financial health at a glance.
Looking for more investment ideas beyond Whitecap Resources?
Once you have a view on Whitecap Resources, it can help to compare that thesis with other companies that share similar qualities or offer a different mix of risk and income. The Simply Wall St screener lets you scan hundreds of stocks through a fundamentals lens instead of just following headlines.
- If capital preservation is your priority, consider using the 9 resilient stocks with low risk scores to see which businesses pair resilience with steadier risk profiles.
- Income focused investors might prefer the reliability angle and start with the 1 dividend fortresses for ideas that combine higher yields with supporting fundamentals.
- For those hunting for less crowded opportunities, the 9 high quality undiscovered gems can surface underfollowed companies where quality metrics already look strong.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com