
CACI International (CACI) Extends Revenue Growth, Is The Stock Still Cheap?
CACI International (CACI) has drawn fresh attention after reporting 11.8% annual revenue growth over the past two years, paired with faster earnings per share expansion supported by ongoing share repurchases.
Recent trading has been supportive, with a 24.7% 90 day share price return and a 16.7% year to date gain at a last close of US$627.06. The 1 year total shareholder return of 20.8% and 3 year total shareholder return of about 2x suggest momentum has been building rather than fading.
Scan beyond CACI International and evaluate other defense and government IT contractors showing similar momentum with our curated list of 31 resilient stocks with low risk scores.
CACI International now trades near US$627 after a sharp run, so the key question is whether to step in at this level or wait and hope for a cooler entry as valuation comes into focus next.
Most Popular Narrative: 15% Undervalued
Against CACI International's last close of $627.06, the most followed valuation narrative marks out a fair value of about $735, implying the current quote sits at a clear discount while still tying everything back to long term backlog, margin and cash flow expectations.
The main thing that has to go right is that CACI International converts its growing electronic warfare, counter UAS, and space program wins, along with expanded nontraditional procurement channels, into sustainably higher margins and free cash flow despite concerns about free cash flow margin and returns on capital.
See why 27 investors see CACI International as 15% undervalued.
Result: Fair Value of $735 (UNDERVALUED)
Still, the CACI International story can unravel if expected double digit revenue growth and high EBITDA margins do not materialize, or if free cash flow remains under pressure.
Find out about the key risks to this CACI International narrative.
Another View: What CACI International's P/E Is Signalling
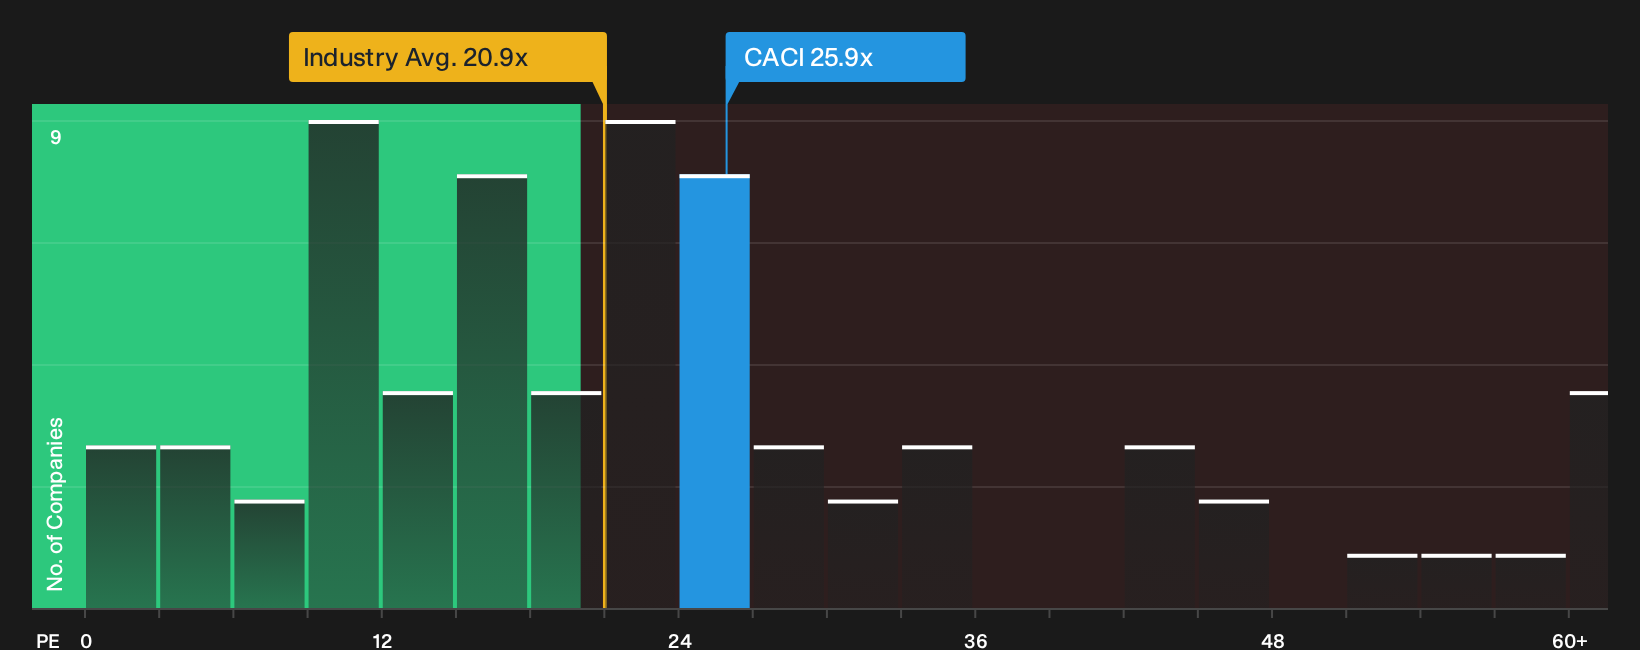
On the flip side of the bullish fair value narrative for CACI International, the current P/E of 25.9x screens as expensive versus both the US Professional Services industry at 20.9x and a fair ratio of 20.8x. That gap points to valuation risk if sentiment cools or growth expectations soften. Which signal do you put more weight on: the discount to fair value, or the premium earnings multiple?
For a deeper look at how those earnings multiples stack up and where the fair ratio might pull the share price over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear opportunity: either way the next move is yours. Move quickly, review the full picture, and weigh the 3 key rewards and 1 important warning sign.
Looking for more CACI International sized ideas?
If CACI International has your attention, do not stop with a single ticker. Broaden your watchlist and give yourself better options for the next decision.
- Target steadier potential by checking companies with stronger fundamentals and lower perceived risk using the 31 resilient stocks with low risk scores.
- Hunt for pricing gaps where quality may trade below intrinsic worth through the 28 high quality undervalued stocks.
- Strengthen your income playbook by scanning for higher yield opportunities with robust payout profiles in the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com