
Learn Why The Bull Case For Modine Manufacturing Stock Could Change Following Data Center Hiring Surge
- Modine Manufacturing has been expanding its Airedale data center cooling footprint, including a 153,000-square-foot plant in Franklin, Wisconsin, supported by hiring up to 300 new workers across shifts with day-one benefits.
- This push to add capacity and labor for energy-efficient data center cooling points to meaningful demand tied to digital infrastructure and higher-spec thermal solutions.
- We will now look at how Modine Manufacturing's data center hiring surge might reshape the broader investment narrative around its growth focus.
Scan the surge in Modine Manufacturing's data center cooling footprint, then size up other infrastructure plays by reviewing the handpicked 39 power grid technology and infrastructure stocks shaping how digital capacity gets built and cooled.
Modine Manufacturing Investment Narrative Recap
To own Modine Manufacturing, you need to buy into a thermal solutions company that is leaning hard into data center cooling while methodically shrinking older combustion focused businesses. The key near term swing factor is how quickly new Airedale capacity in places like Franklin, Wisconsin is absorbed into real orders without pressuring pricing or quality. The hiring ramp helps execution, but it also increases fixed costs.
The biggest risk right now is straightforward. If data center deployment timing or customer budgets slow, Modine could be left with underused plants, inventory, and compressed margins, especially with current net profit margin at 4.3%, below last year’s 7.2%. Integration of prior HVAC acquisitions and ongoing exits from light duty operations add more moving parts that investors need to monitor closely.
The most relevant reference point for this expansion push is the prior multi site Airedale capacity buildout in Franklin, Grand Prairie, Grenada, and Jefferson City announced in mid 2025. That plan linked Modine Manufacturing’s growth focus directly to U.S. based manufacturing and local supply chains for data center cooling equipment. The current Wisconsin hiring is essentially the labor follow through on that footprint.
For catalysts, the open question is how efficiently this enlarged network converts backlog and customer interest into sustained production and better margins, especially as analysts still expect strong earnings and revenue growth from Modine. Execution risk ties back to whether new plants, acquisitions, and exited legacy lines all line up cleanly, or whether short term disruptions and under absorption weigh on reported profitability before the thesis plays out.
Modine Manufacturing's current analyst narrative points to forecast revenues of US$6.5b and earnings of US$996.0m by 2029, built on assumed yearly revenue growth of 24.2%. That earnings figure sits against earnings today of US$144.2m and implies an increase of about 6.9x from current earnings if those projections are met.
Uncover why Modine Manufacturing's fair value indicates a 64% potential upside to its current price, which could narrow quickly.
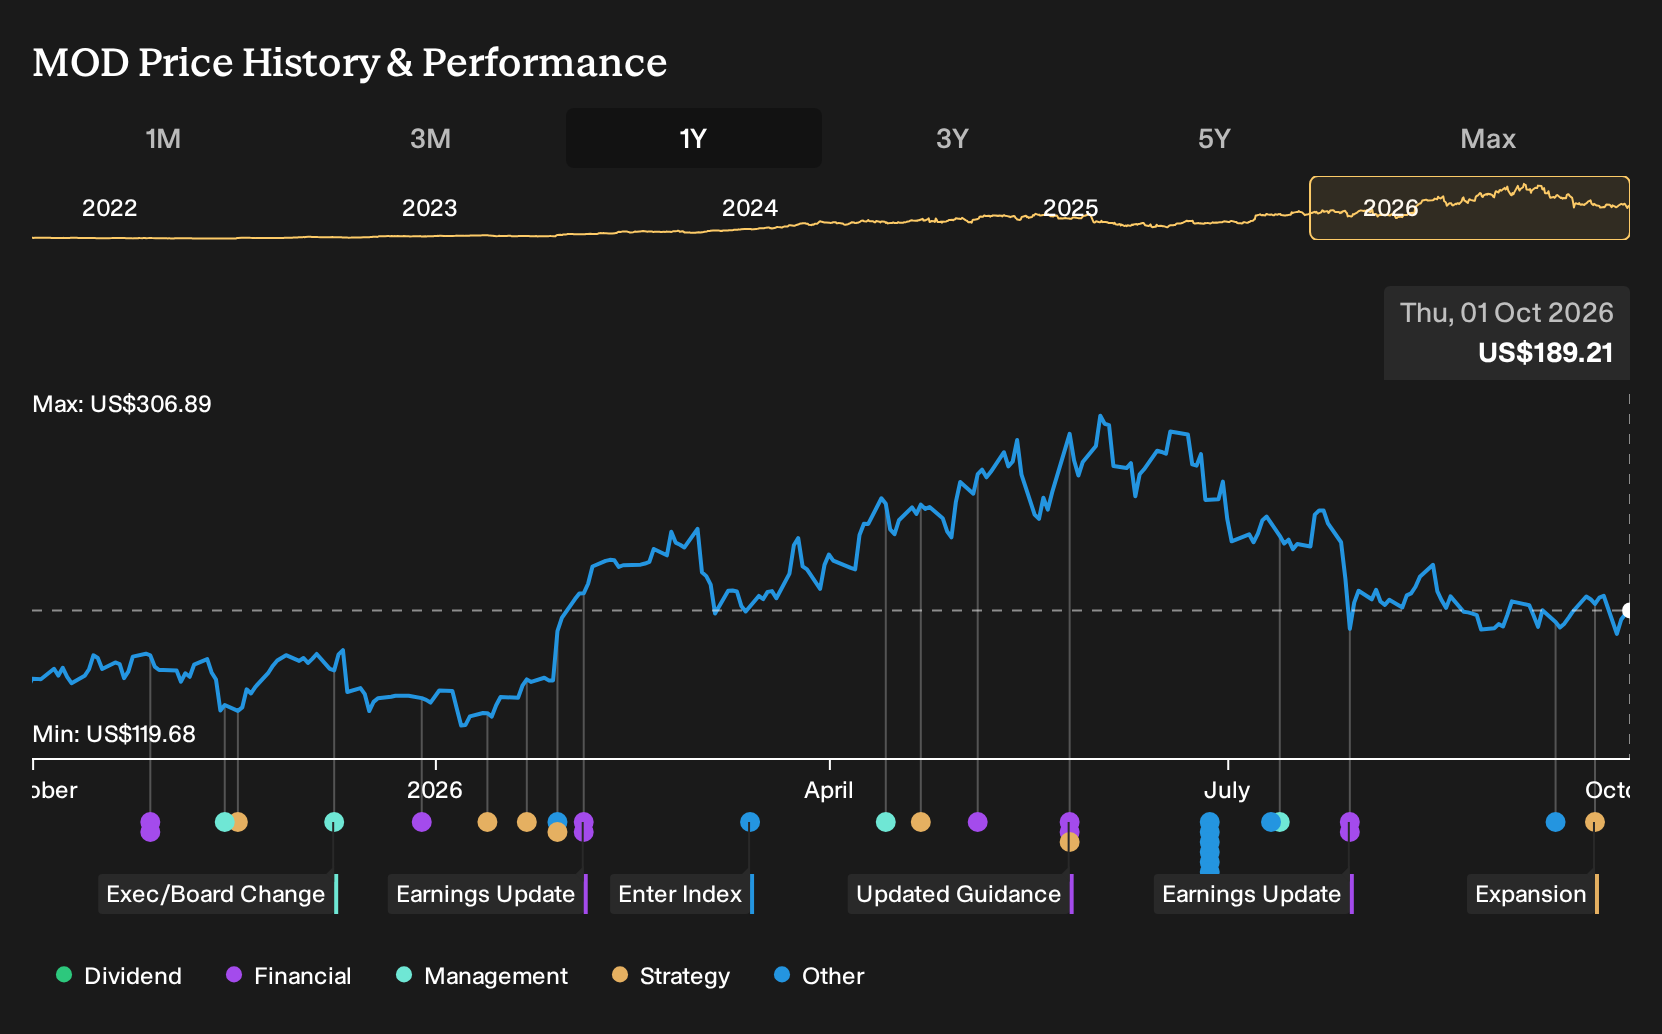
Exploring Other Perspectives
One optimistic twist in the Modine Manufacturing story is the bullish focus on long dated capacity agreements with hyperscale customers, which highest analysts linked to revenue reaching about US$7.3b and earnings near US$974.5m by 2029. Those projections were set before this Wisconsin hiring news, so you may want to see how views shift now.
Explore 2 other Modine Manufacturing fair value estimates, including one that suggests the potential for as much as 64% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Modine Manufacturing research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Modine Manufacturing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Modine Manufacturing's overall financial health at a glance.
Looking For More Investment Ideas Beyond Modine Manufacturing?
If the Modine Manufacturing story has you thinking about where else capital equipment and cash flow resilience might show up, it can help to scan a wider field of companies with similar or complementary traits. The Simply Wall St Screener gives you a structured way to filter for balance sheet strength, income potential, or underappreciated quality before you commit fresh money.
- If you want candidates that combine strong finances with room to grow, review a curated 28 high quality undervalued stocks that already score well on quality and pricing metrics.
- For investors who care most about stability and risk control, filter for companies on the 31 resilient stocks with low risk scores that have consistently lower risk profiles based on multiple factors.
- When the goal is to uncover lesser known opportunities with solid fundamentals, scan the 19 high quality undiscovered gems that rarely make headlines but still clear strict quality hurdles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com