
Novo Nordisk (NVO) Stock Looks Reasonable Given Uncertain Long Term Earnings
Novo Nordisk has seen a steep share price reset in recent years, and the question now is whether the current valuation still lines up with the earnings power investors are paying for.
- The stock has fallen 55.8% over the past 3 years, which puts the focus squarely on whether that drop has brought the earnings multiple closer to what its cash generation can support.
- Fresh long term growth targets, new product ambitions and looming semaglutide patent expiries may reshape how much of Novo Nordisk's current earnings investors treat as durable versus at risk.
- The analysts covering Novo Nordisk have run their own numbers. See what analysts think Novo Nordisk's shares could be worth.
The issue now is whether Novo Nordisk's current share price is justified by the earnings the business is producing today and is expected to sustain.
If you are comparing Novo Nordisk with similar opportunities connected to medical breakthroughs, it can be useful to evaluate it alongside 35 healthcare AI stocks.
Is Novo Nordisk a Bargain on Earnings?
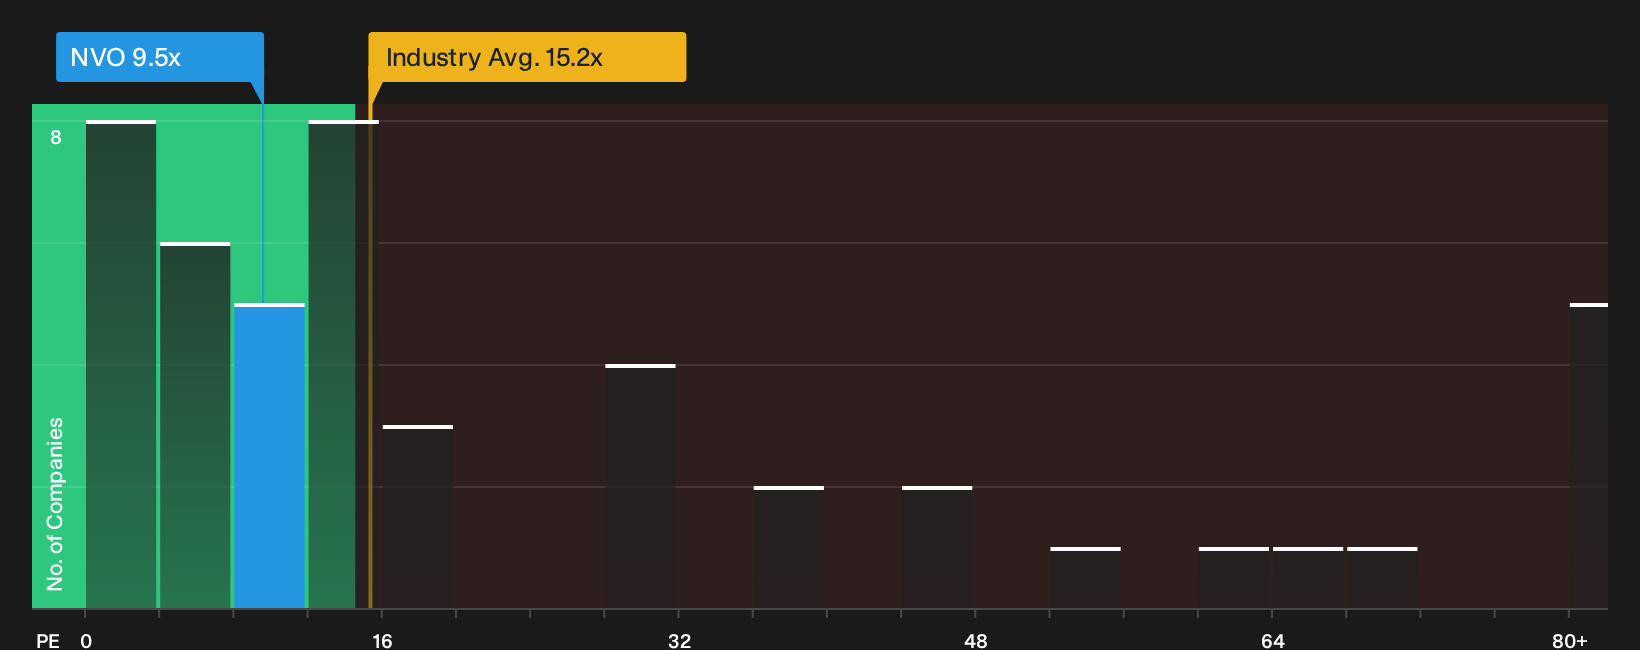
The P/E ratio is a useful way to see how much investors are paying today for Novo Nordisk's current earnings stream. On this measure, Novo Nordisk trades at about 9.5x earnings, which is well below the Pharmaceuticals industry average of roughly 15.2x and far under the broader peer group near 48.0x.
The fair value model suggests a P/E that would usually be higher once Novo Nordisk's profitability, scale and risk profile are taken into account, so the current 9.5x sits below that tailored benchmark and screens as undervalued on this lens. Because the long term growth targets and semaglutide patent concerns have weighed on sentiment, the low multiple implies the market is already pricing in a meaningful hit to future earnings relative to peers. That gap leaves the question of whether the current discount compensates for those risks or points to an opportunity. Explore the numbers behind Novo Nordisk's P/E valuation.
The Novo Nordisk Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Novo Nordisk leaves off, spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price. Each narrative treats Novo Nordisk's estimated fair value as a thesis about the business that you can watch over time rather than a single static number. These narratives are available on Simply Wall St's Community page.
One of the top community narratives on Novo Nordisk: 61% undervalued
"Current sentiment has swung deeply negative, but expectations are now low, and the embedded upside is material..."
Discover why this Narrative puts Novo Nordisk at 61% undervalued.
Novo Nordisk’s valuation still leaves one key issue unresolved
All the earnings multiples and fair value work only matter if the underlying business checks hold up, and Simply Wall St’s research has flagged specific concerns that deserve your attention next. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com