
Discover 3 European Growth Stocks With Significant Insider Ownership
As European markets navigate a complex landscape of improving growth prospects and potential monetary tightening due to high energy prices, investors are keenly observing sectors that may benefit from these shifts. In this context, companies with strong growth trajectories and significant insider ownership can offer unique insights into confidence levels among those closest to the business.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| MilDef Group (OM:MILDEF) | 10.3% | 32.5% |
| Kuros Biosciences (SWX:KURN) | 25.9% | 60.3% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| Clavister Holding AB (publ.) (OM:CLAV) | 20.5% | 41.1% |
| CD Projekt Red (WSE:CDR) | 35.2% | 53.9% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 30.2% |
Let's take a closer look at a couple of our picks from the screened companies.
eDreams ODIGEO (BME:EDR)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: eDreams ODIGEO S.A. is an online travel company operating in France, Southern Europe, Northern Europe, and internationally with a market cap of €437.17 million.
Operations: The company's revenue is primarily derived from its Prime segment, generating €509.58 million, and its Non-Prime segment, contributing €151.83 million.
Insider Ownership: 11%
Return On Equity Forecast: 22% (2029 estimate)
eDreams ODIGEO is leveraging its Prime subscription platform to drive growth, recently expanding into Poland, a key market within its international strategy. Despite recent earnings showing a decline in net income to €0.23 million from €13.57 million year-on-year, the company remains focused on scaling operations and enhancing transaction capabilities through strategic alliances with Visa. Although revenue growth is moderate at 6.7% annually, eDreams trades at a significant discount to its estimated fair value and offers competitive relative value compared to peers.
- Take a closer look at eDreams ODIGEO's potential here in our earnings growth report.
- Our valuation report here indicates eDreams ODIGEO may be undervalued.

Kuros Biosciences (SWX:KURN)
Simply Wall St Growth Rating: ★★★★★★
Overview: Kuros Biosciences AG focuses on the commercialization and development of biologic technologies for musculoskeletal care across the USA, EU, and internationally, with a market cap of CHF747.84 million.
Operations: Revenue Segments (in millions of $): null
Insider Ownership: 25.9%
Return On Equity Forecast: 24% (2029 estimate)
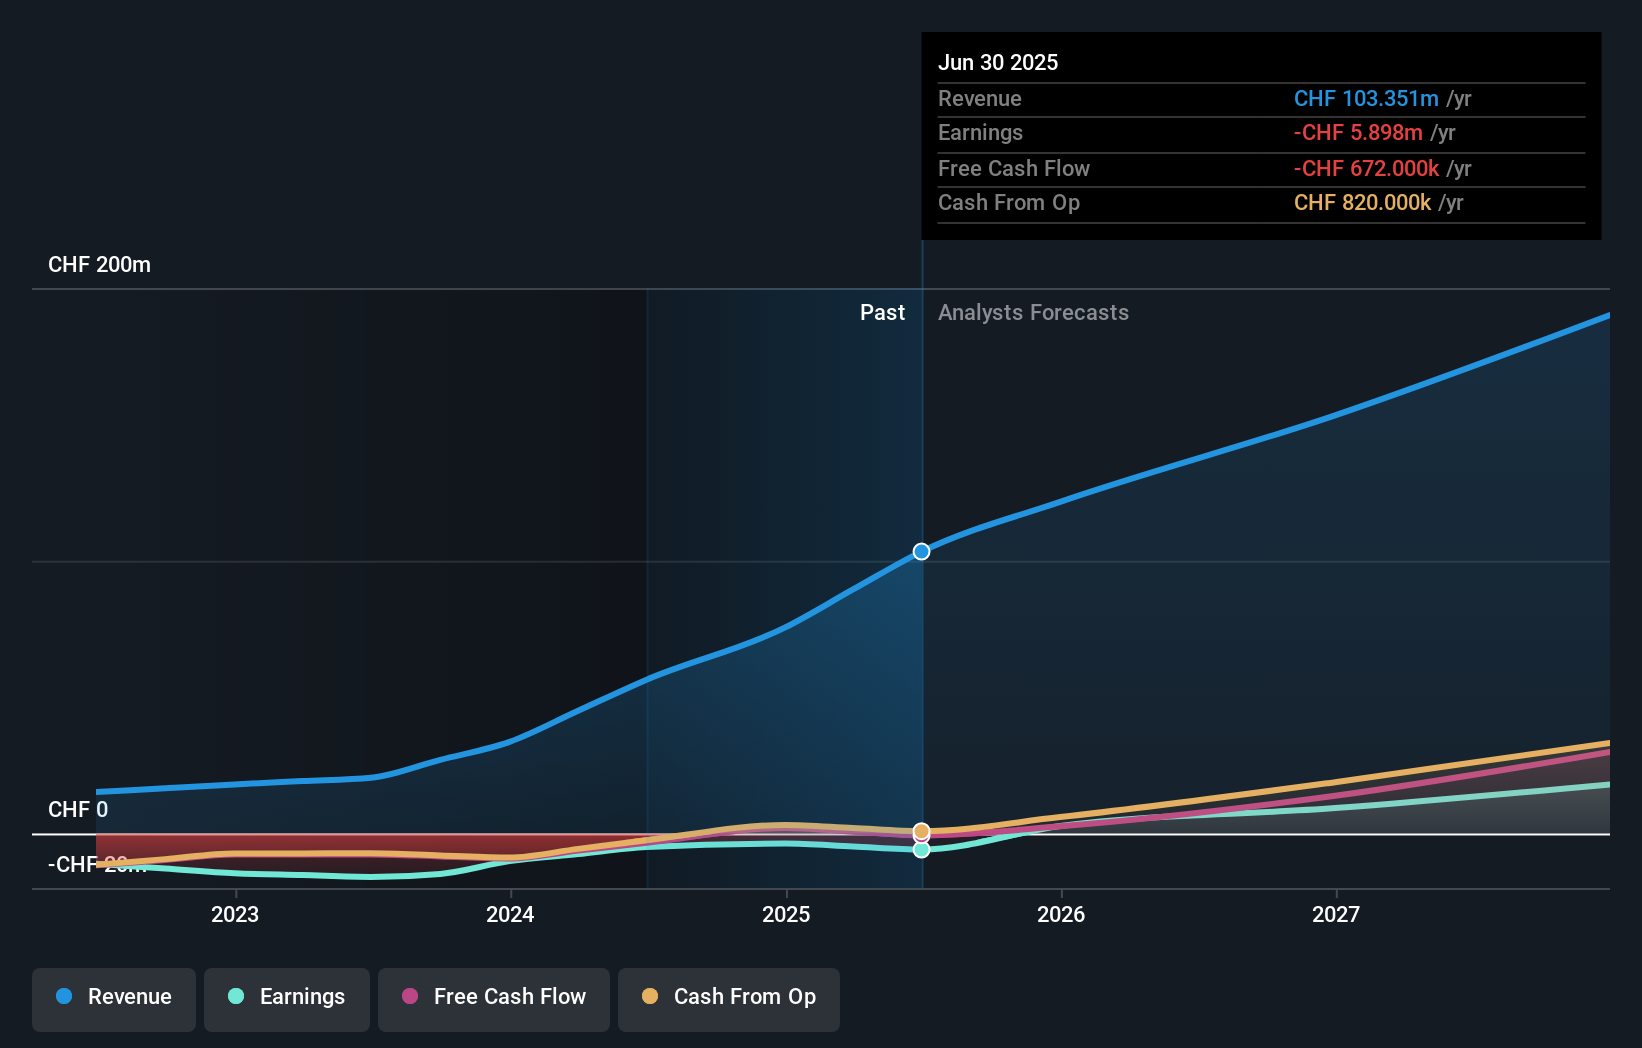
Kuros Biosciences has shown promising financial performance, becoming profitable this year with revenue for the first half of 2026 at US$92.35 million, up from US$63.48 million a year ago. Earnings are projected to grow significantly at 60.3% annually, surpassing Swiss market averages. Despite high share price volatility, Kuros trades at a substantial discount to its estimated fair value and analysts predict an 81.9% stock price increase, supported by confirmed sales growth guidance through 2028.
- Navigate through the intricacies of Kuros Biosciences with our comprehensive analyst estimates report here.
- Upon reviewing our latest valuation report, Kuros Biosciences' share price might be too pessimistic.
VAT Group (SWX:VACN)
Simply Wall St Growth Rating: ★★★★★☆
Overview: VAT Group AG, along with its subsidiaries, specializes in developing, manufacturing, and selling vacuum and gas inlet valves, multi-valve modules, motion components, and edge-welded metal bellows; it has a market capitalization of CHF20.39 billion.
Operations: The company's revenue segments consist of Valves at CHF897.08 million and Global Service at CHF213.77 million.
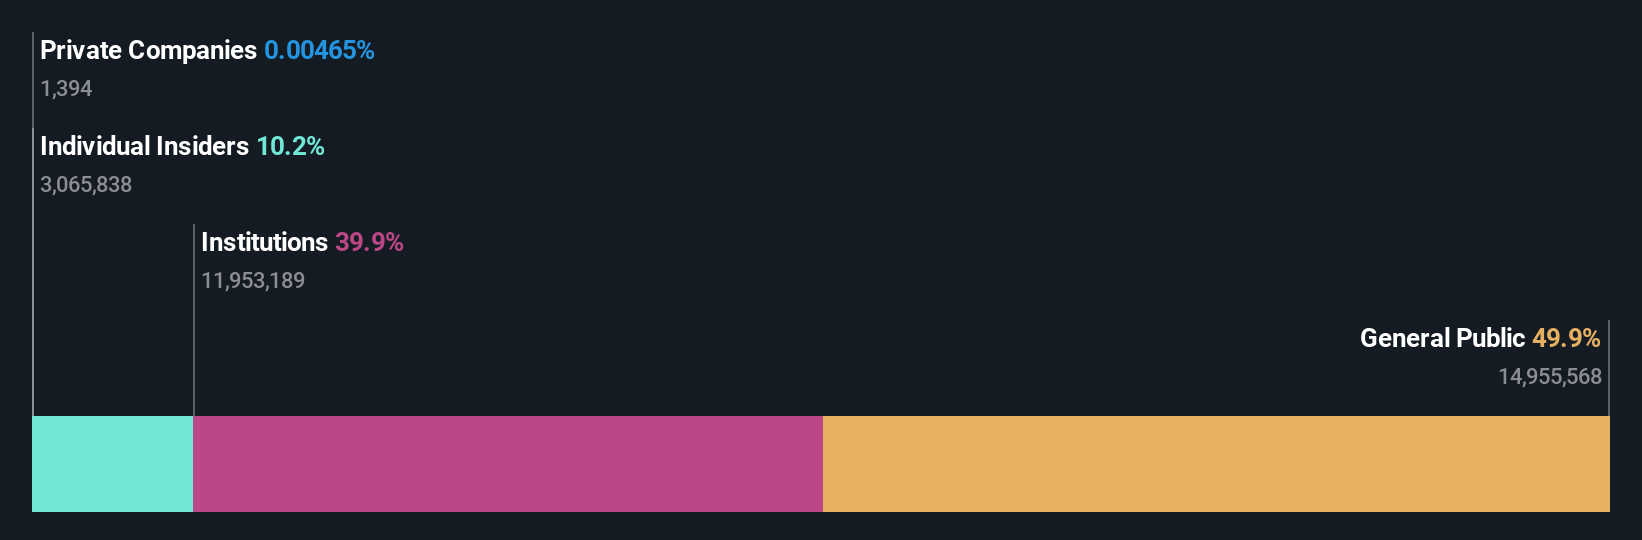
Insider Ownership: 10.2%
Return On Equity Forecast: 47% (2029 estimate)
VAT Group, headquartered in Switzerland, is poised for growth with significant insider ownership and a projected earnings increase of 25.1% annually over the next three years, outpacing the Swiss market. Despite recent volatility and a slight decline in first-half 2026 sales to CHF 511.89 million, VAT maintains strong revenue forecasts and confirmed full-year guidance. The company also expanded its partnership with Hockey Club Davos, enhancing brand visibility through arena naming rights and jersey sponsorships.
- Get an in-depth perspective on VAT Group's performance by reading our analyst estimates report here.
- Upon reviewing our latest valuation report, VAT Group's share price might be too optimistic.
Make It Happen
- Unlock our comprehensive list of 214 Fast Growing European Companies With High Insider Ownership by clicking here.
- Looking For Alternative Opportunities? Uncover 26 companies that survived and thrived after COVID and have the right ingredients to survive Trump's tariffs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com