
Store Expansion Could Be A Game Changer For Hornbach Holding KGaA (XTRA:HBH)
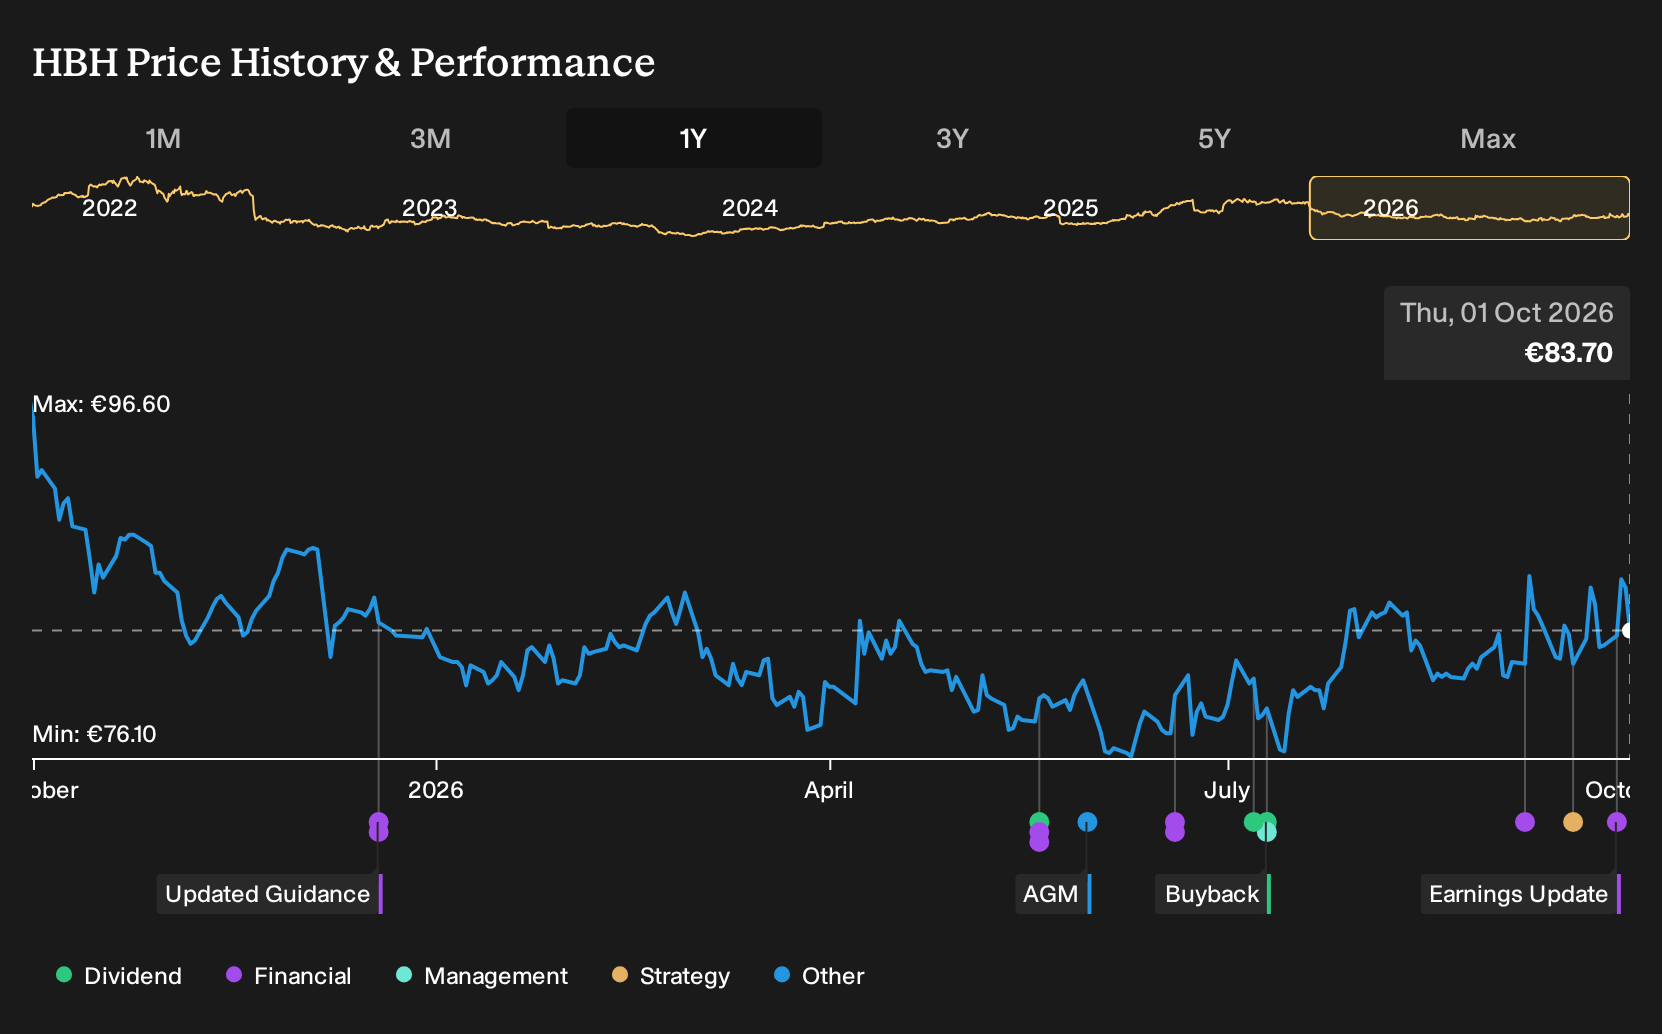
- HORNBACH Holding KGaA reported second quarter sales of €1,813.7 million and net income of €74.9 million, alongside six-month figures of €3,816.2 million in sales and €174.7 million in net income, while also outlining expansion into new DIY store locations across Germany and other European markets.
- The combination of higher earnings per share from continuing operations and the planned takeover of former Hellweg sites indicates that HORNBACH Holding KGaA is using its current profitability to support a larger physical footprint and deepen its project-focused retail offering in several European countries.
- We will now examine how HORNBACH Holding KGaA's expansion into former Hellweg locations relates to the existing investment narrative.
Scan how HORNBACH Holding KGaA's expansion story compares with other retailers pursuing physical growth and solid fundamentals by reviewing the hand-picked list of solid balance sheet and fundamentals (207 results).
HORNBACH Holding KGaA Investment Narrative Recap
To own HORNBACH Holding KGaA, you need to believe in a steady, project focused DIY retailer that can keep stores busy even when sentiment in Germany is soft. The latest half year numbers, with €3,816.2 million in sales and €174.7 million in net income, suggest the business is operating from a position of relative stability.
The key short term swing factor now is execution on expansion while protecting margins that already feel the strain of higher salary expenses. New stores and pre opening costs can pressure earnings if demand disappoints or ramps slowly, so macro weakness and cost creep still sit as the biggest near term risk.
The Hellweg related expansion plan is the most relevant move for this catalyst story. Six new German locations, plus further openings across Austria, the Netherlands and Serbia, would push HORNBACH Holding KGaA closer to the 200 megastore mark and increase fixed costs before any customer traffic actually shows up.
Those sites, scheduled to transfer in December 2026 and reopen in spring 2027, extend the existing bet on physical scale and project oriented assortments. For you as an investor, the focus now is on how well management controls pre opening spending, trains staff quickly and integrates these stores without eroding the profitability underpinning the current investment case.
HORNBACH Holding KGaA's current analyst storyline points to revenues of €7.0b and earnings of €159.2 million by 2029, based on revenue growth of 2.2% a year and a move from €132.4 million in earnings today to that 2029 consensus level. This represents an earnings increase of about €26.8 million over the period.
Uncover why HORNBACH Holding KGaA's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into HORNBACH Holding KGaA's expansion angle. Before this earnings and Hellweg news, they were pencilling in around €6.9b of revenue and €189.5 million of earnings by 2029. That is a much punchier story than consensus and could shift again once these fresh numbers are fully digested.
Explore 3 other HORNBACH Holding KGaA fair value estimates, including one that suggests up to 180% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your HORNBACH Holding KGaA research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for HORNBACH Holding KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HORNBACH Holding KGaA's overall financial health at a glance.
Looking For More Investment Ideas Beyond HORNBACH Holding KGaA?
If HORNBACH Holding KGaA has helped sharpen your thinking, it can be useful to compare that thesis with other companies that share traits like solid finances, income potential, or mispriced quality. The Simply Wall St screener gives you a quick way to surface those candidates without getting buried in raw data.
- For investors who care most about balance sheet strength and resilient fundamentals, start with this curated list of solid balance sheet and fundamentals (207 results) that filters for companies with robust financial footing.
- If your priority is finding mispriced quality, take a look at the carefully selected 190 high quality undervalued stocks that focuses on businesses where fundamentals and current pricing appear out of sync.
- For those building a portfolio around income, consider the targeted 159 dividend fortresses that highlights companies offering yields above 5% with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com