
Higher Annual Profit Might Change The Case For Investing In KBC Ancora Stock (ENXTBR:KBCA)
- KBC Ancora reported full year results for the period to 30 June 2026, with revenue of €0.006776 million and net income of €389.37 million compared with €315.43 million a year earlier.
- The holding company generated almost unchanged revenue while posting a much higher profit figure. This highlights how earnings for KBC Ancora depend far more on underlying investment outcomes and financial items than on recurring operating income.
- We will now look at how KBC Ancora's higher net income shapes the broader investment narrative around this Belgian holding vehicle.
Spot opportunities that mirror KBC Ancora's investment driven earnings profile by scanning our hand picked 617 high quality undiscovered gems with similar strong fundamentals that are hidden behind low headline revenue.
What Is KBC Ancora's Investment Narrative?
The big belief with KBC Ancora is simple. You have to be comfortable owning a pure holding vehicle whose fate is tied to its stake in KBC Group rather than to its own operations. The latest full year figures underline that reality. Revenue stayed around €0.0068 million while net income reached €389.37 million, so your thesis lives or dies on capital allocation, balance sheet discipline and what happens inside the underlying banking investment, not on growing a traditional business.
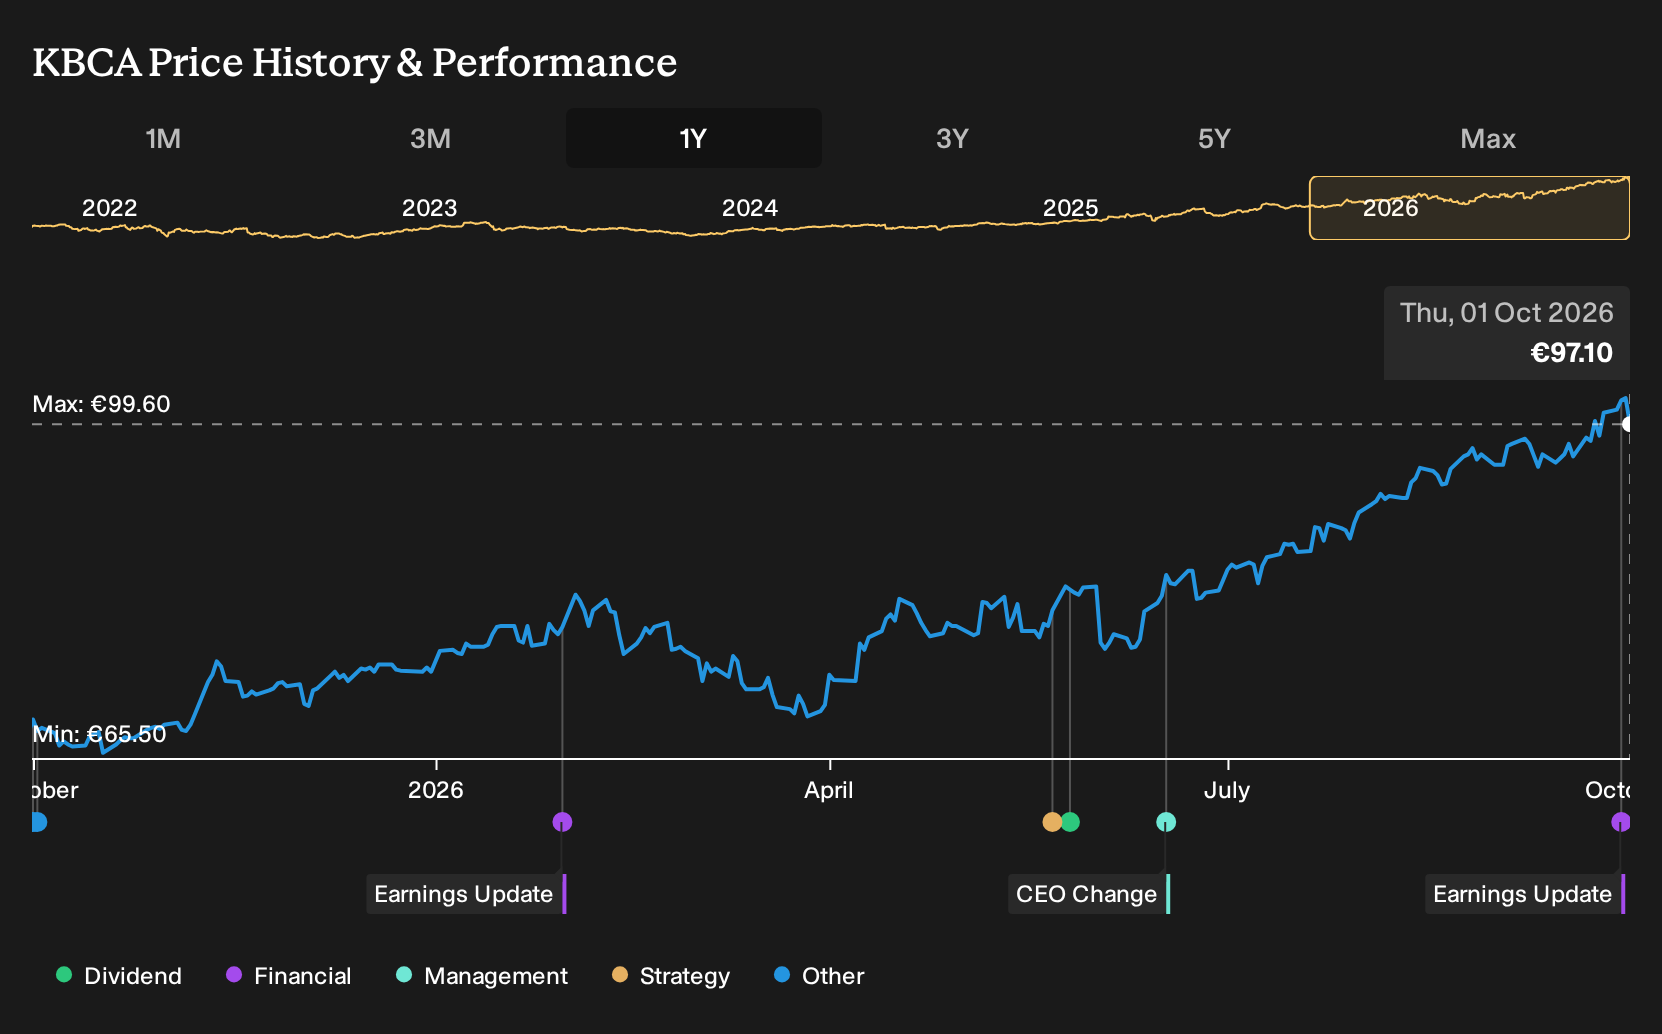
In the short term, this profit outcome feeds directly into key catalysts investors tend to watch. That includes the scope for distributions, the sustainability of that record and how much leverage is sensible given funding relies fully on external borrowing. The share price has risen strongly over 1 year and the stock now trades on a P/E of 19.2x, above peer and fair value estimates. That combination makes execution on payouts and debt policy more important than this single earnings print.
Yet beside the appealing earnings story and recent share price strength, there is an awkward wrinkle that sits in the background of KBC Ancora's setup.
There's only one way to know the right time to buy, sell or hold KBC Ancora. Head to Simply Wall St's company report for the latest analysis of KBC Ancora's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly €77.56 to €112 per share, so private investors already price KBC Ancora with a wide margin of opinion. Because these views predate the June 2026 earnings, you should treat the fresh profit figure as a test of those earlier assumptions.
Explore another KBC Ancora fair value estimate, including one that suggests as much as 20% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your KBC Ancora research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for KBC Ancora. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KBC Ancora's overall financial health at a glance.
Looking For More Investment Ideas Beyond KBC Ancora?
Once you have a view on KBC Ancora, it can help to widen the lens and compare it with other companies that have different balance sheet profiles, income sources and risk levels. The Simply Wall St Screener lets you do exactly that by filtering the market down to a focused list that matches what you care about most.
- If you want a cushion against shocks and prefer financially sturdy businesses, start with a list of solid balance sheet and fundamentals (207 results) that can better handle tough conditions.
- If your priority is limiting downside risk while still staying invested, narrow the field to a 224 resilient stocks with low risk scores that score well on stability and volatility.
- If you are hunting for strong fundamentals that have not yet drawn much attention, scan a 617 high quality undiscovered gems that combine quality metrics with relatively low visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com