
Is Enerflex (TSX:EFX) Fully Priced After Its Data Center Win?
Enerflex has been on a powerful run in recent years, and with the share price now well above where it traded a few years ago, the key question is whether that move is justified by the earnings that support it.
- Over the past 3 years the stock has delivered a very large gain, which puts real pressure on the current earnings stream to carry that kind of market value.
- Winning a long lead time contract tied to data center power and reshaping the portfolio through Asia Pacific divestitures may support different expectations for future profit levels, timing and reinvestment needs.
- Your read on Enerflex is one view; the desks covering it have another. See what analysts think Enerflex's shares could be worth.
The stock's next move may depend on whether Enerflex's current earnings profile can reasonably support the price investors are paying today.
If you are weighing Enerflex against other ways to play large, capital intensive themes like data centers and energy infrastructure, it can help to scan 39 power grid technology and infrastructure stocks
Is Enerflex Getting Expensive on Earnings?
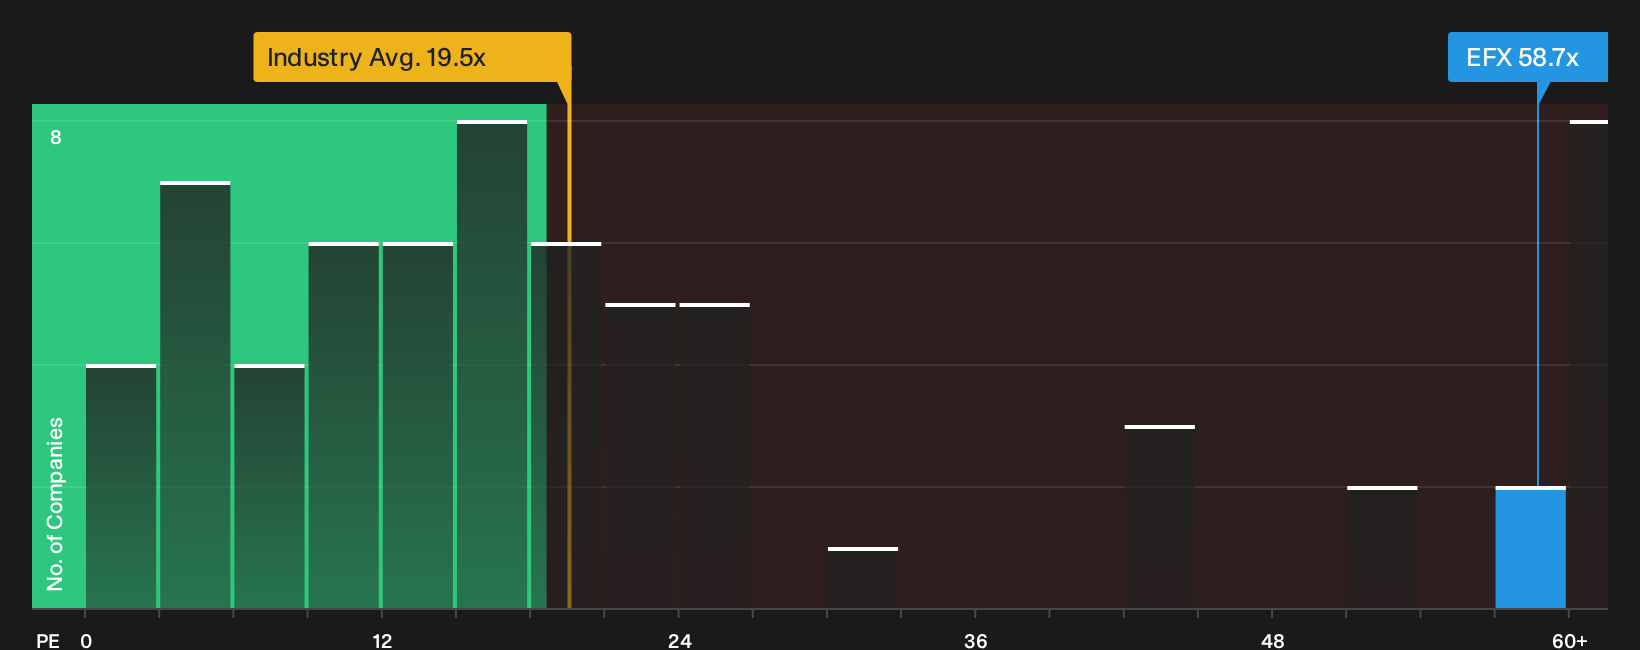
The P/E lens fits Enerflex because earnings are now a key driver of how investors frame the business. Enerflex trades on a P/E of about 58.7x, which is well above the Energy Services industry average near 16.0x and ahead of the peer group around 18.5x. That is a rich price tag for each dollar of current profit.
On this framework, the tailored fair P/E that lines up with Enerflex's size, profitability profile and risk points to a lower figure than the current multiple, so the stock screens as overvalued on earnings. Recent headlines about the large data center power contract and record backlog help explain why investors are willing to pay up. However, the valuation already bakes in a lot of optimism about how those projects convert into lasting earnings. If you are comparing Enerflex with other energy infrastructure and data center suppliers, it is worth asking how much earnings resilience you need to see to stay comfortable with a P/E this high relative to sector norms. Explore the numbers behind Enerflex's P/E valuation.
The Enerflex Narrative: What Would Justify Today's Price?
Enerflex Narratives on Simply Wall St pick up where the valuation puzzle leaves off by spelling out what would need to happen to future growth, margins and earnings for the stock to be worth materially more or less than it is today. They sit on the Community page so you can see how other investors frame those possibilities. Each one sets out the assumptions behind its view of fair value in plain terms so you can line those up against actual results as Enerflex reports them.
One of the top community narratives on Enerflex: 14% undervalued
"Bearish analysts may question whether Enerflex’s margin and growth ambitions fully justify higher price targets, especially if they see limited room for error…"
Discover why this Narrative puts Enerflex at 14% undervalued.
Before acting on Enerflex's valuation, there is one more piece to check
Price tags and profit metrics only tell part of the story for Enerflex, because the people steering the business and the way their rewards are structured can heavily influence how those numbers evolve over time. See who runs Enerflex and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com