
3 UK Penny Stocks With Market Caps Up To £400M
The United Kingdom's stock market has recently faced challenges, with the FTSE 100 index closing lower due to weak trade data from China, which has affected companies closely tied to its economic fortunes. Despite these broader market pressures, there remains potential for investors in smaller or newer companies known as penny stocks. Although the term may seem outdated, penny stocks can still offer value by focusing on those with solid financial foundations and growth potential.
Here's a peek at a few of the choices from the screener.
Impax Asset Management Group (AIM:IPX)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Impax Asset Management Group Plc is a publicly owned investment manager with a market cap of £132.68 million.
Operations: Impax Asset Management Group does not report specific revenue segments.
Market Cap: £132.68M
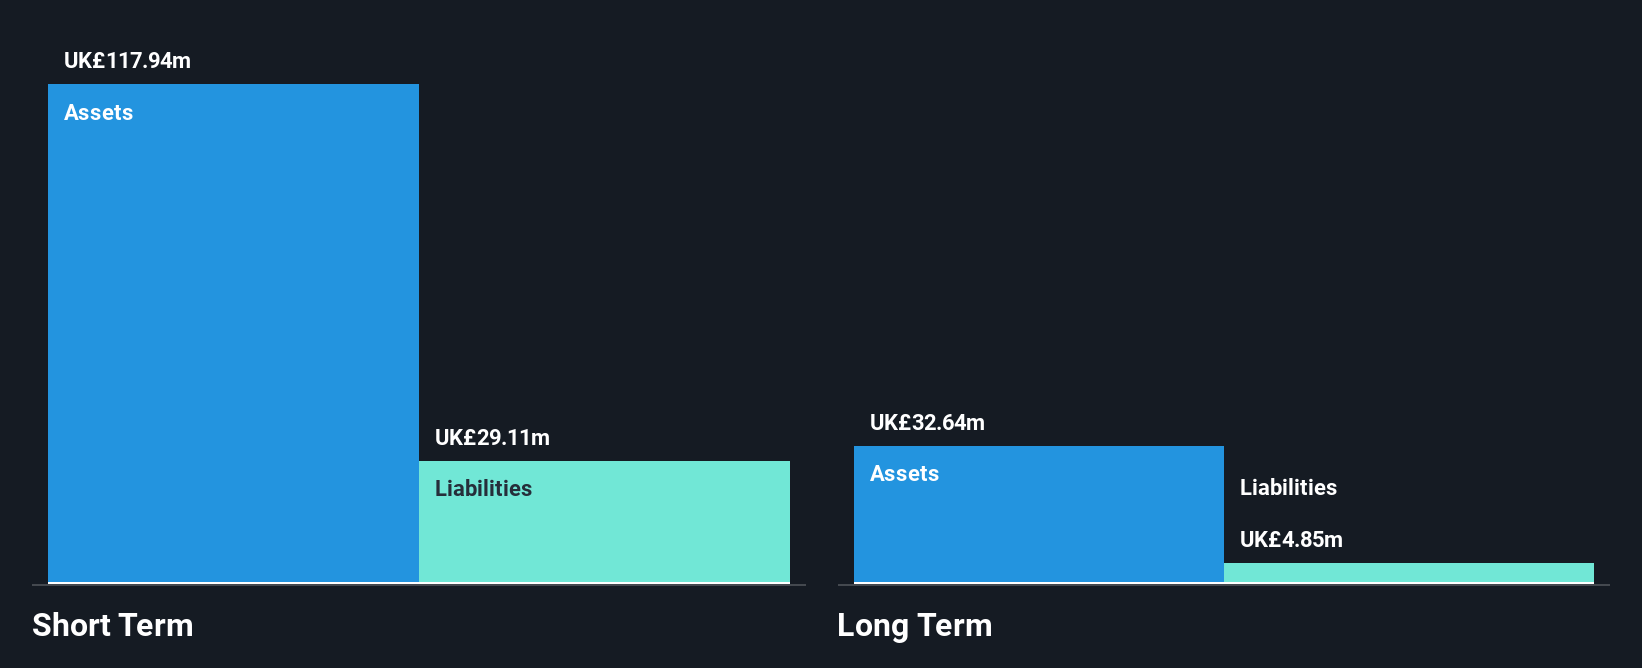
Impax Asset Management Group, with a market cap of £132.68 million, presents a mixed picture for investors interested in penny stocks. While the company is debt-free and has stable short-term assets exceeding liabilities, its earnings have declined by 12.7% annually over the past five years and experienced negative growth of 57.2% last year. The company's profit margins have also narrowed from 19.2% to 10.6%. Despite trading at good value compared to peers, Impax's share price has been highly volatile recently, and its dividend yield of 10.99% is not well covered by earnings due to large one-off losses impacting financial results.
- Click to explore a detailed breakdown of our findings in Impax Asset Management Group's financial health report.
- Gain insights into Impax Asset Management Group's outlook and expected performance with our report on the company's earnings estimates.
CAB Payments Holdings (LSE:CABP)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: CAB Payments Holdings plc operates in business-to-business cross-border payments and foreign exchange services across multiple regions including the Americas, UK, Europe, Africa, the Middle East, and Asia with a market cap of approximately £213.25 million.
Operations: The company's revenue segment includes Unclassified Services, generating £84.43 million.
Market Cap: £213.25M
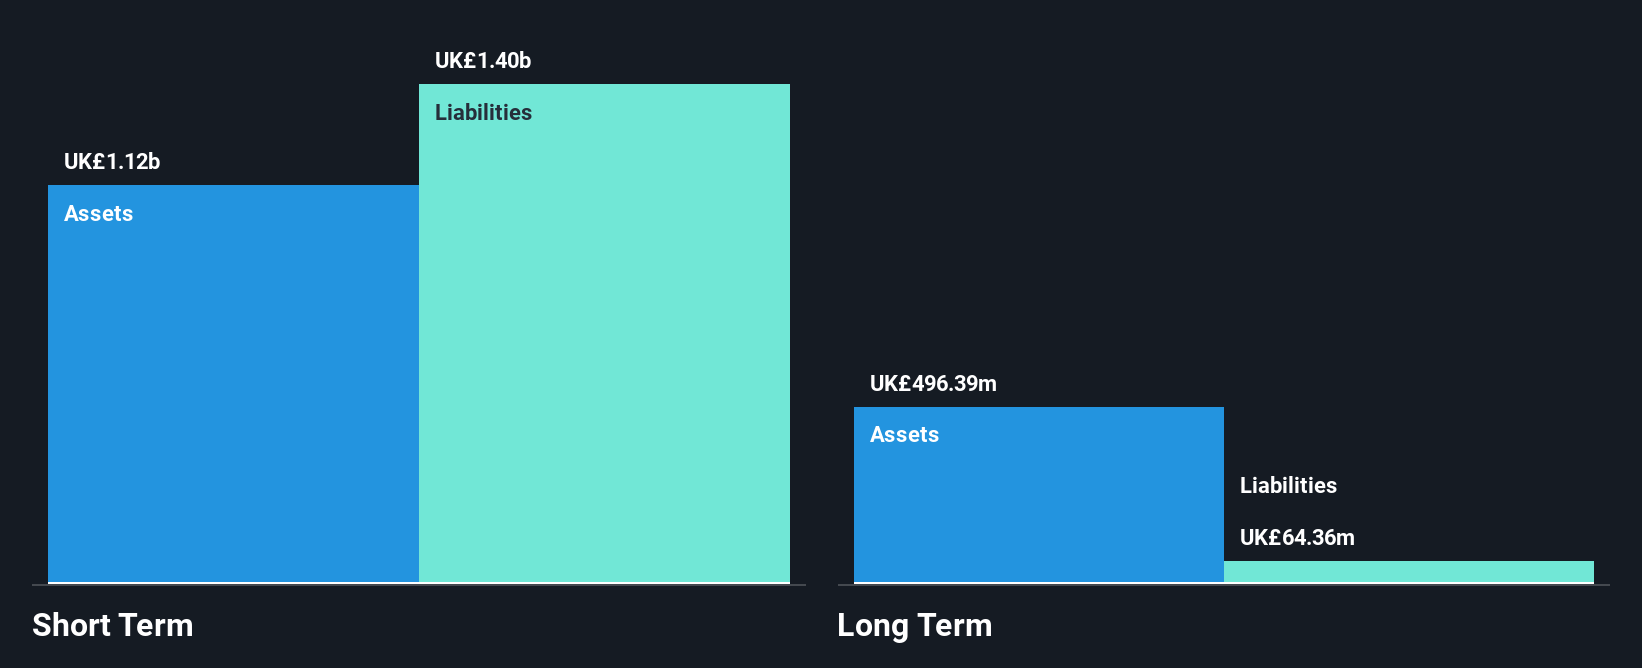
CAB Payments Holdings, with a market cap of £213.25 million, offers a complex investment landscape for penny stock enthusiasts. The company reported robust earnings growth of 230.5% over the past year, significantly surpassing industry averages and improving net profit margins from 7.1% to 24.6%. Despite being debt-free and having high-quality earnings, CAB Payments faces challenges such as short-term liabilities exceeding assets by £800 million and significant insider selling recently. Additionally, its dividend yield of 5% is not well covered by free cash flows, raising sustainability concerns despite the recent inaugural dividend announcement.
- Jump into the full analysis health report here for a deeper understanding of CAB Payments Holdings.
- Review our growth performance report to gain insights into CAB Payments Holdings' future.
McBride (LSE:MCB)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: McBride plc, with a market cap of £303.03 million, manufactures and sells private label household and personal care products to retailers and brand owners across the United Kingdom, Europe, the Asia-Pacific region, and internationally.
Operations: The company's revenue is primarily derived from its Liquids segment at £526 million, followed by Unit Dosing at £226.3 million, Powders at £88.7 million, Aerosols at £67.3 million, and the Asia Pacific region contributing £25.9 million.
Market Cap: £303.03M
McBride plc, with a market cap of £303.03 million, presents a mixed investment case. The company has shown significant earnings growth over the past five years but experienced negative earnings growth of -9.6% in the last year, underperforming the household products industry average. Recent strategic partnerships aim to boost contract manufacturing revenues by GBP 170 million annually by 2028, though this will increase net debt by up to GBP 25 million. While McBride's short-term assets exceed liabilities and interest payments are well covered by EBIT, high net debt levels remain a concern for potential investors in this volatile penny stock space.
- Click here to discover the nuances of McBride with our detailed analytical financial health report.
- Assess McBride's future earnings estimates with our detailed growth reports.

Key Takeaways
- Get an in-depth perspective on all 255 UK Penny Stocks by using our screener here.
- Curious About Other Options? The end of cancer? These 35 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com