
UK Stocks Estimated To Be Trading Below Fair Value In October 2026
As the FTSE 100 and FTSE 250 indices experience downward pressure due to weak trade data from China, the London markets face challenges amid global economic uncertainties. In such an environment, identifying stocks that are potentially trading below their fair value can offer investors opportunities for growth by focusing on companies with strong fundamentals that may be temporarily undervalued due to broader market conditions.
Top 10 Undervalued Stocks Based On Cash Flows In The United Kingdom
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Telecom Plus (LSE:TEP) | £7.97 | £13.51 | 41% |
| Stelrad Group (LSE:SRAD) | £1.46 | £2.48 | 41.1% |
| Smiths News (LSE:SNWS) | £0.742 | £1.46 | 49.2% |
| Smith & Nephew (LSE:SN.) | £9.824 | £17.41 | 43.6% |
| Property Franchise Group (AIM:TPFG) | £4.11 | £7.51 | 45.3% |
| Polar Capital Holdings (AIM:POLR) | £8.30 | £14.58 | 43.1% |
| LSL Property Services (LSE:LSL) | £2.50 | £4.66 | 46.3% |
| Gamma Communications (LSE:GAMA) | £10.98 | £20.15 | 45.5% |
| Distribution Finance Capital Holdings (AIM:DFCH) | £0.75 | £1.37 | 45.3% |
| Autotrader Group (LSE:AUTO) | £4.604 | £7.69 | 40.2% |
Below we spotlight a couple of our favorites from our exclusive screener.
Cohort (AIM:CHRT)
Overview: Cohort plc operates in the defense, security, and related markets across multiple regions including the UK, Germany, Portugal, Australia, the Americas, Asia Pacific, Africa, and other European countries with a market cap of £549.62 million.
Operations: The company's revenue is primarily derived from its Sensors and Effectors segment, which generated £147.46 million, and its Communications and Intelligence segment, contributing £159 million.
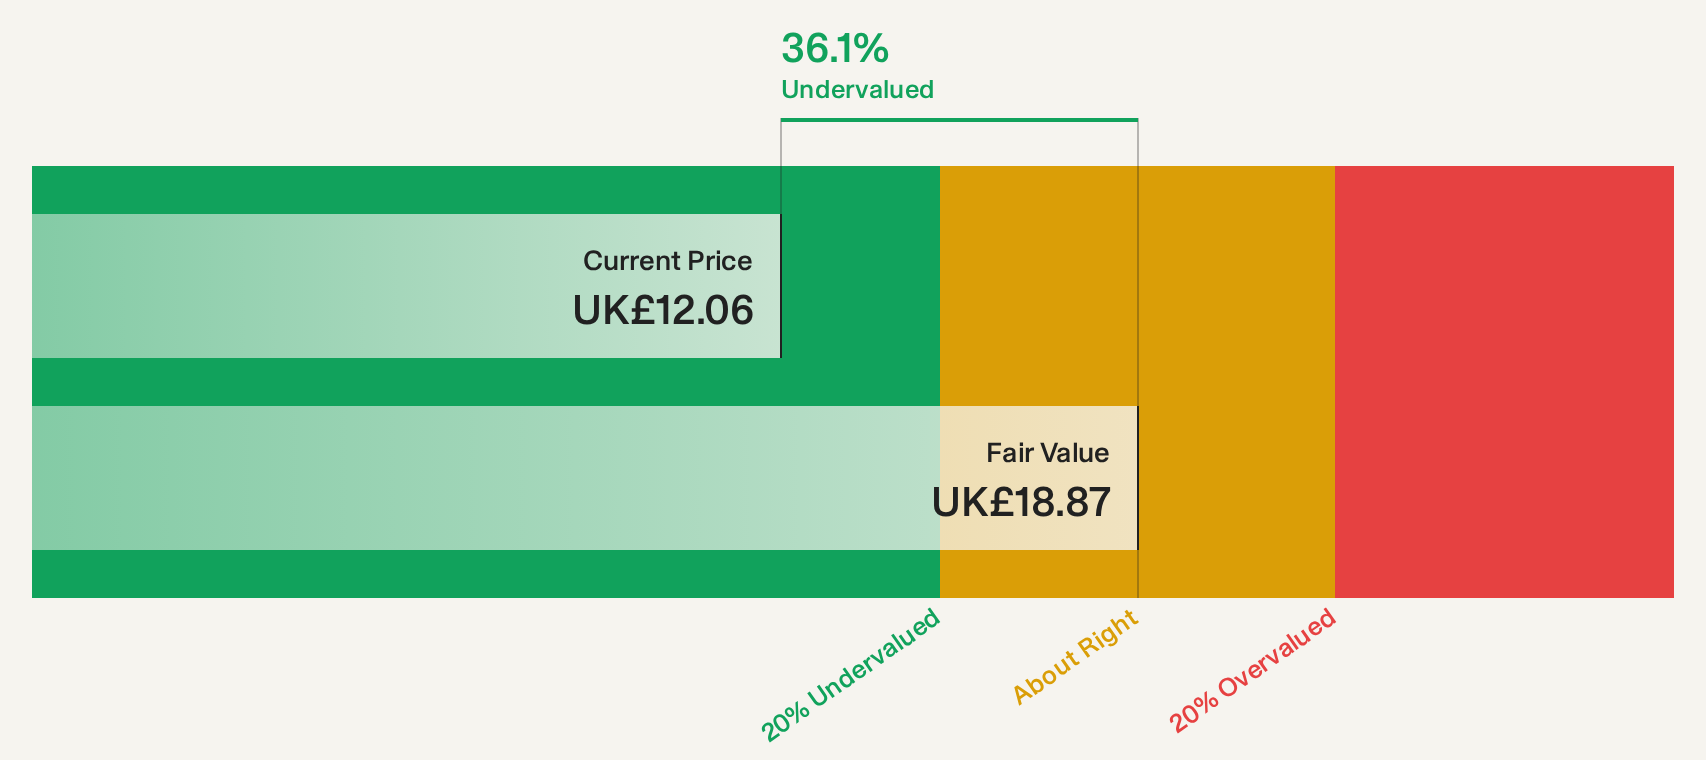
Estimated Discount To Fair Value: 36.8%
Cohort is trading at £11.94, significantly below its estimated future cash flow value of £18.89, suggesting it may be undervalued. The company's earnings grew by 24.2% last year and are forecast to grow 14.4% annually, outpacing the UK market's 11.1%. Despite slower revenue growth of 6.9%, Cohort's sales rose to £306.39 million from £270.04 million last year, with net income increasing to £23.9 million from £19.25 million amidst recent insider selling concerns.
- According our earnings growth report, there's an indication that Cohort might be ready to expand.
- Dive into the specifics of Cohort here with our thorough financial health report.
Funding Circle Holdings (LSE:FCH)
Overview: Funding Circle Holdings plc operates online lending platforms in the United Kingdom and internationally, with a market cap of approximately £530.53 million.
Operations: The company generates revenue through its online lending platforms, with £50.50 million from Flexipay and £199.70 million from Term Loans.
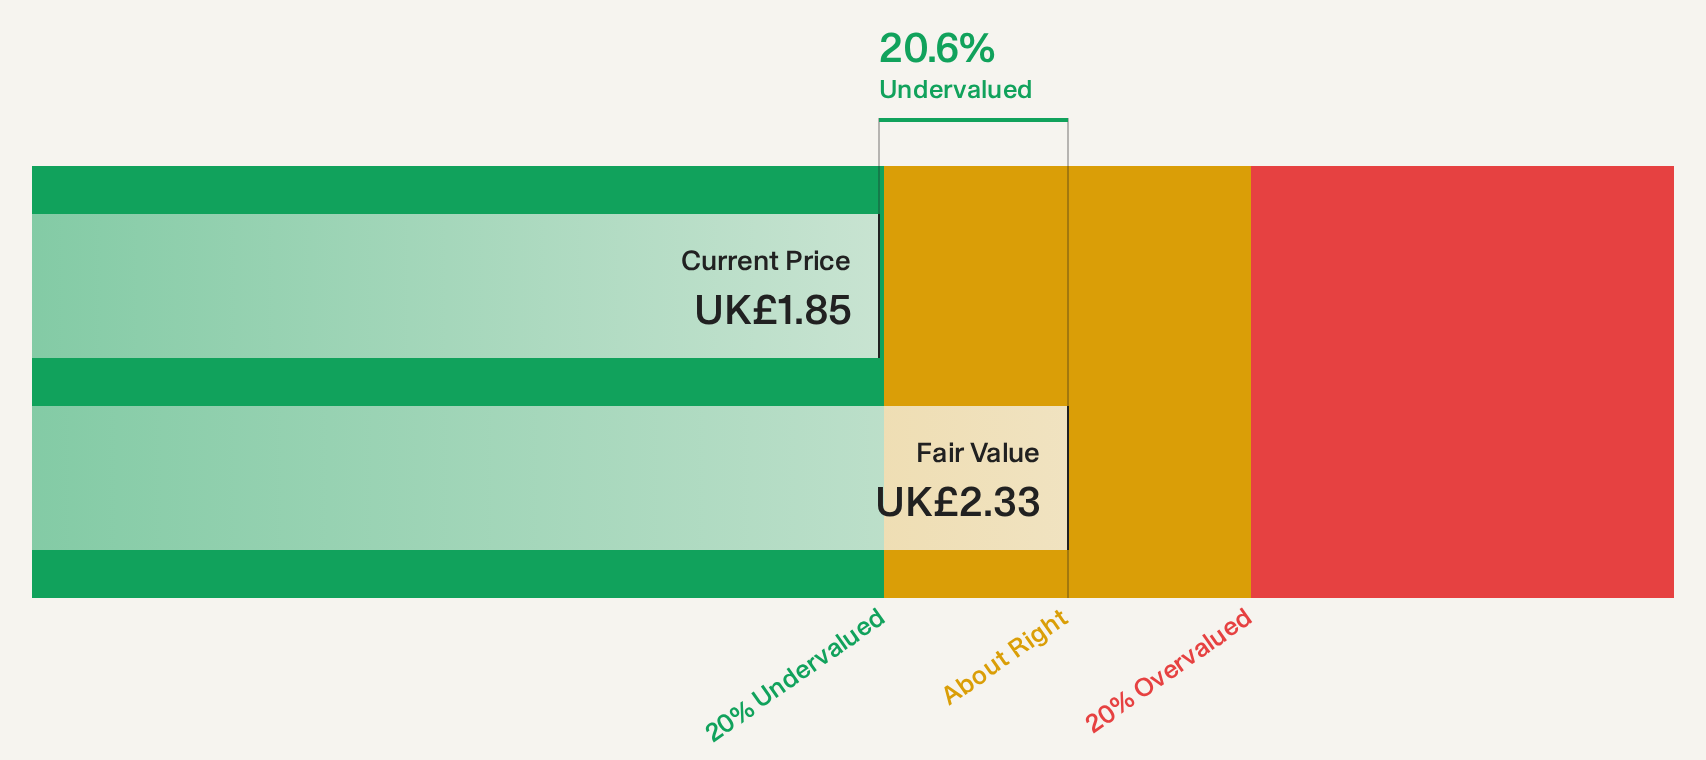
Estimated Discount To Fair Value: 21.4%
Funding Circle Holdings is trading at £1.83, well below its estimated future cash flow value of £2.33, highlighting potential undervaluation. The company reported a substantial rise in earnings to £22.6 million for H1 2026 from £5.8 million the previous year, driven by revenue growth to £138.2 million from £92.3 million. Despite high share price volatility and slower forecasted earnings growth compared to the UK market, it remains an intriguing prospect based on cash flows and recent buybacks totaling 4.64% of shares for £22.3 million.
- Our earnings growth report unveils the potential for significant increases in Funding Circle Holdings' future results.
- Click here to discover the nuances of Funding Circle Holdings with our detailed financial health report.
International Consolidated Airlines Group (LSE:IAG)
Overview: International Consolidated Airlines Group S.A. operates passenger and cargo transportation services across various global regions, including the North Atlantic, Latin America, and Asia Pacific, with a market cap of £19.03 billion.
Operations: The company's revenue segments include British Airways (€17.34 billion), Iberia (€8.10 billion), IAG Loyalty (€3.04 billion), Vueling (€3.29 billion), and Aer Lingus (€2.50 billion).
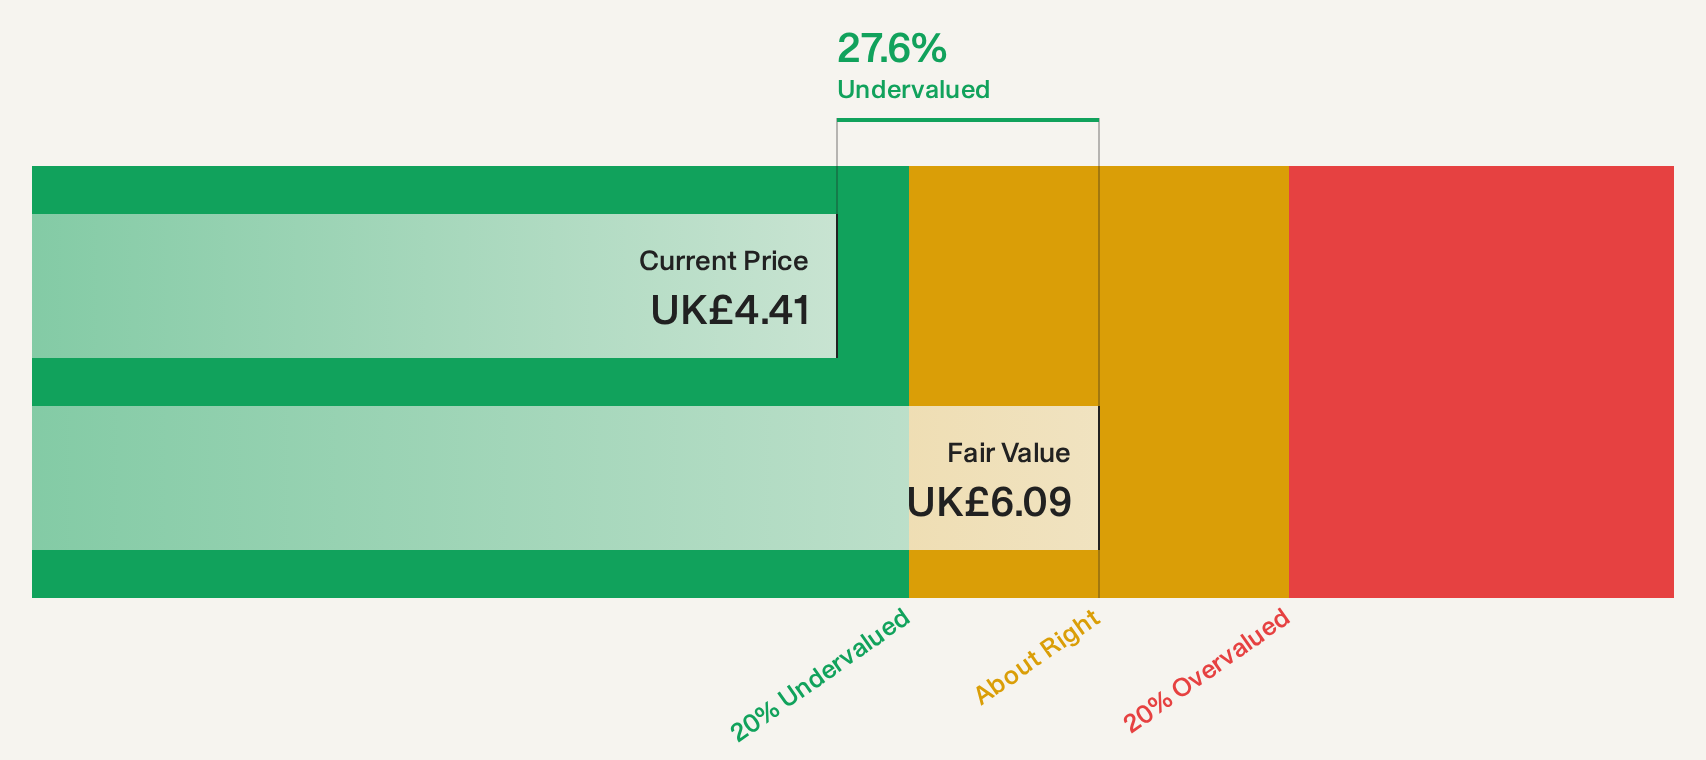
Estimated Discount To Fair Value: 28.9%
International Consolidated Airlines Group is trading at £4.32, significantly below its estimated future cash flow value of £6.08, suggesting potential undervaluation. Recent index inclusions highlight its market presence despite a decline in net income to €1.03 billion for H1 2026 from €1.3 billion the previous year. While earnings growth forecasts of 8.57% annually lag behind the UK market average, it offers good relative value compared to peers and industry benchmarks based on discounted cash flow analysis.
- Upon reviewing our latest growth report, International Consolidated Airlines Group's projected financial performance appears quite optimistic.
- Navigate through the intricacies of International Consolidated Airlines Group with our comprehensive financial health report here.
Summing It All Up
- Explore the 29 names from our Undervalued UK Stocks Based On Cash Flows screener here.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com