
Did Digital Bank Approval Just Shift VEON's (VEON) Investment Narrative?
- VEON Ltd. reported that its joint venture with Square Group received a digital bank license from Bangladesh Bank, extending Banglalink’s Mukto Pay payments footprint into full digital banking backed by an initial US$250 million commitment under the Invest in Bangladesh NOW partnership.
- The tie up combines VEON’s digital finance technology with Square Group’s on the ground distribution reach. This development could affect how investors assess execution risk, capital needs and monetisation potential in Bangladesh’s underbanked population.
- We will now explore how VEON’s investment narrative could be reshaped by the move into licensed digital banking through the Bangladesh joint venture.
VEON Investment Narrative Recap
To own VEON, you need to believe its telecom base in Pakistan, Ukraine, Kazakhstan, Uzbekistan and Bangladesh can keep supporting a larger digital ecosystem, especially in finance. The big near term catalyst is execution in these higher value services while keeping capex tight. The new Bangladesh digital bank license adds optionality but does not reduce core market or currency exposure.
The largest risk still sits on the balance sheet. Gross debt of US$4.63b and interest costs that are not well covered by current earnings mean any capital intensive push, including the US$250m Bangladesh commitment, raises the bar on delivery. Weak net margins at 1.2% only sharpen that pressure.
The digital bank approval links most directly to VEON’s wider push into fintech and super app style services across its footprint. Management already runs mobile money, cloud, entertainment and neobank offerings on top of 4G networks. A regulated bank in Bangladesh deepens that stack and could influence how investors frame future fee income against telecom style economics.
This sits beside other potential catalysts that analysts have highlighted, such as eventual monetisation of fintech assets like JazzCash or listings of units such as Kyivstar. Each move would test whether VEON can turn digital scale into better earnings quality while dealing with structurally lower EBITDA margins in these services and the need to support high expected earnings growth of 28.3% a year.
VEON's narrative projects US$6.2b revenue and US$730.9m earnings by 2029. This assumes 9.2% yearly revenue growth and an earnings increase of about US$671.9m from US$59.0m today.
Uncover why VEON's fair value indicates an 18% potential upside to its current price that could narrow quickly.
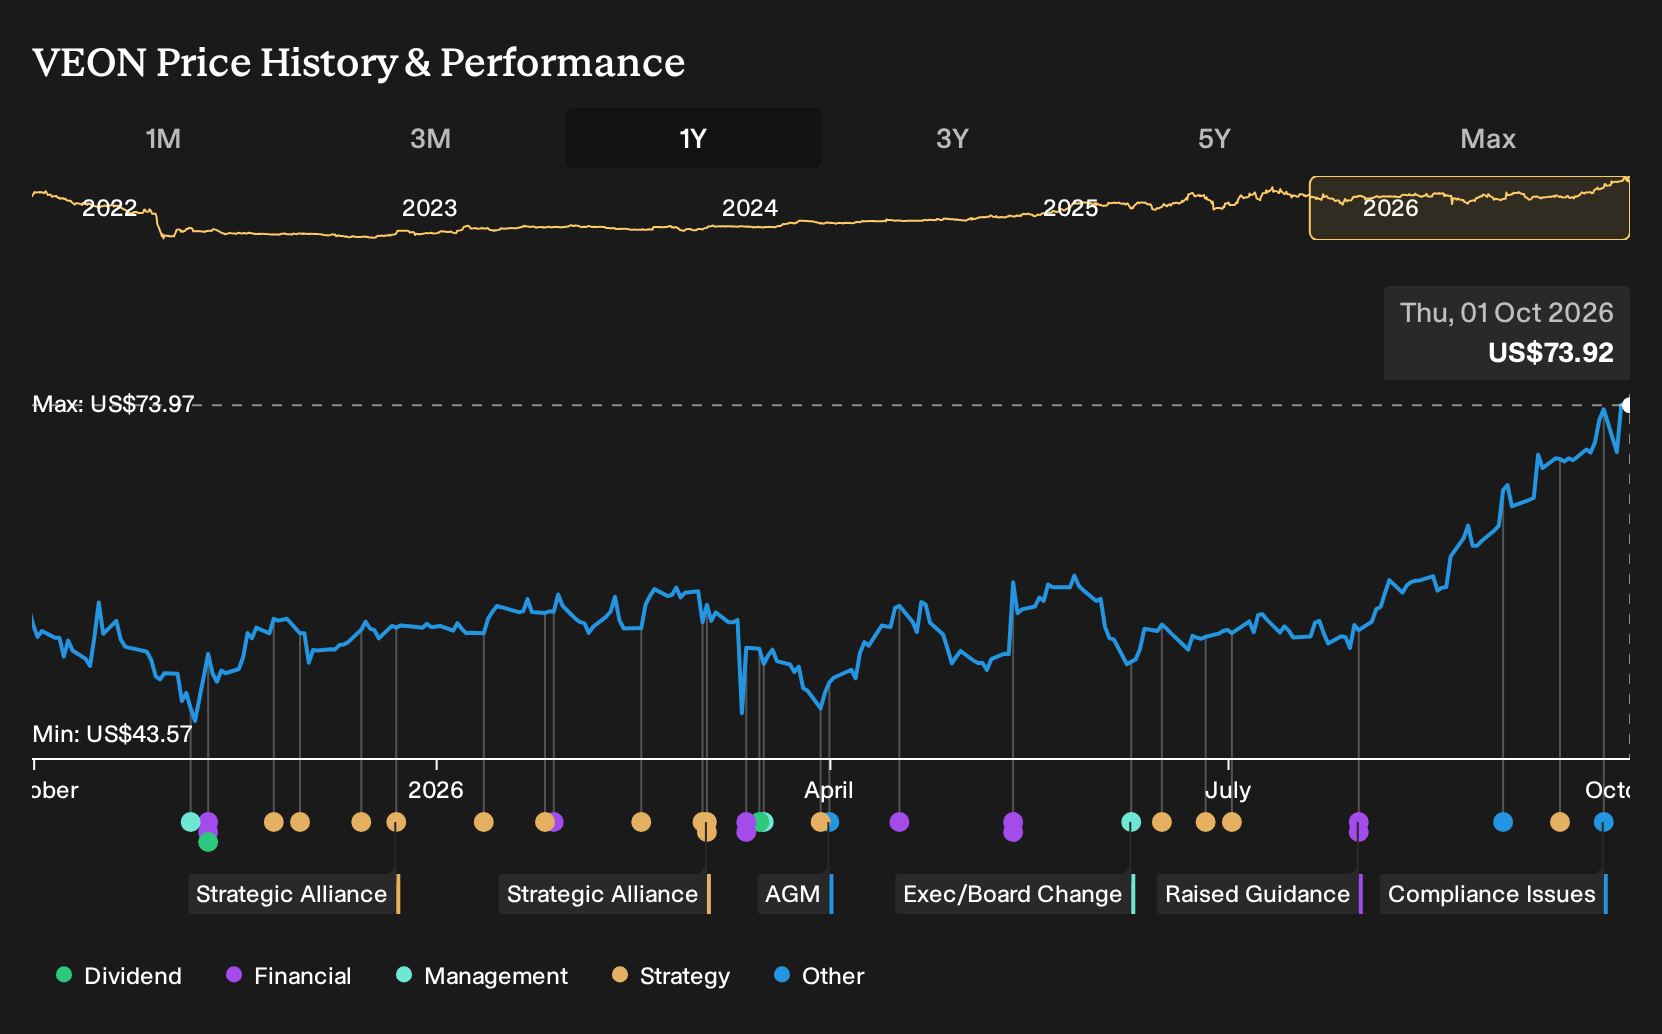
Exploring Other Perspectives
You might see this Bangladesh digital bank approval very differently if you focus on currency and political risk. The lowest VEON analysts were already cautious, working off 6.8% annual revenue growth to about US$5.6b and earnings of roughly US$567.6m by 2029. Those views predate the license, so opinions may evolve and it is worth exploring both sides yourself.
Explore 4 other VEON fair value estimates, including one that suggests as much as 31% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your VEON research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for VEON. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate VEON's overall financial health at a glance.
Looking for more ideas beyond VEON?
If VEON has you thinking more broadly about telecoms, fintech and balance sheet risk, it can help to line it up against other listed businesses with different financial profiles. The Simply Wall St Screener lets you do that quickly by filtering for specific traits such as balance sheet strength, lower risk scores or under followed opportunities with solid fundamentals.
- For investors who care about financial resilience first, start with a list of solid balance sheet and fundamentals (25 results) that can help you compare VEON with peers that have stronger liquidity and leverage metrics.
- If you prefer companies that aim to reduce downside risk, scan a 31 resilient stocks with low risk scores and see which stocks score well on volatility, financial health and earnings quality checks.
- To round out your watchlist with opportunities that are less crowded, consider a 19 high quality undiscovered gems that highlights businesses with robust fundamentals that are not heavily followed by the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com