
Is Trial Failure Altering The Investment Case For Immunovant Stock (IMVT)?
- Immunovant reported topline data from a 57-patient proof-of-concept trial in cutaneous lupus erythematosus in which IMVT-1402 did not reach statistical significance on the primary CLASI A endpoint at Week 12, leading the firm to discontinue development for this indication.
- The decision to halt CLE work concentrates Immunovant’s resources on autoimmune indications such as difficult-to-treat rheumatoid arthritis and Graves’ disease, where management is already planning larger, potentially registrational trials as core value drivers.
- We will now examine how Immunovant's long-term autoimmune investment narrative interacts with this CLE program shutdown and accompanying resource shift.
Explore how Immunovant’s strategic pivot fits into the broader autoimmune opportunity set by comparing it with our hand picked 35 healthcare AI stocks that are also targeting complex immune disorders.
Immunovant Investment Narrative Recap
To own Immunovant, you need to believe IMVT-1402 can translate into a meaningful autoimmune drug franchise in rheumatoid arthritis and Graves’ disease despite the company having no current revenue and ongoing losses. The CLE miss trims optionality but does not materially change the near term focus. That focus still hinges on clean execution in the lead autoimmune studies.
The key near term catalyst remains the difficult to treat rheumatoid arthritis data and continued progress toward the planned 2027 Graves’ disease readout. The biggest risk stays the same. Any efficacy or timing setback in IMVT-1402, combined with future funding needs and dilution, could weaken the long term earnings story implied by current expectations.
The CLE proof of concept readout is the most relevant recent announcement here. IMVT-1402 did not reach statistical significance on the primary CLASI A endpoint at Week 12 in a 57 patient trial, and Immunovant is halting CLE development. That removes one indication from the pipeline and modestly narrows where the FcRn asset is being tested.
For catalysts, this CLE decision effectively concentrates operational effort and capital on indications that management already flagged as central, difficult to treat rheumatoid arthritis and Graves’ disease. The operational risk now leans even more on those programs. With Immunovant still pre revenue and unprofitable, trial quality, timelines, and future financing terms remain the core things to watch.
Immunovant's current analyst narrative points to forecast revenue of US$559.3 million and projected earnings of US$101.9 million by 2029. That profile implies revenue growth from a zero base and an earnings swing of roughly US$640 million from a loss of US$538.2 million today to the forecast profit level.
Uncover why Immunovant's fair value indicates a 43% potential upside to its current price that could narrow quickly.
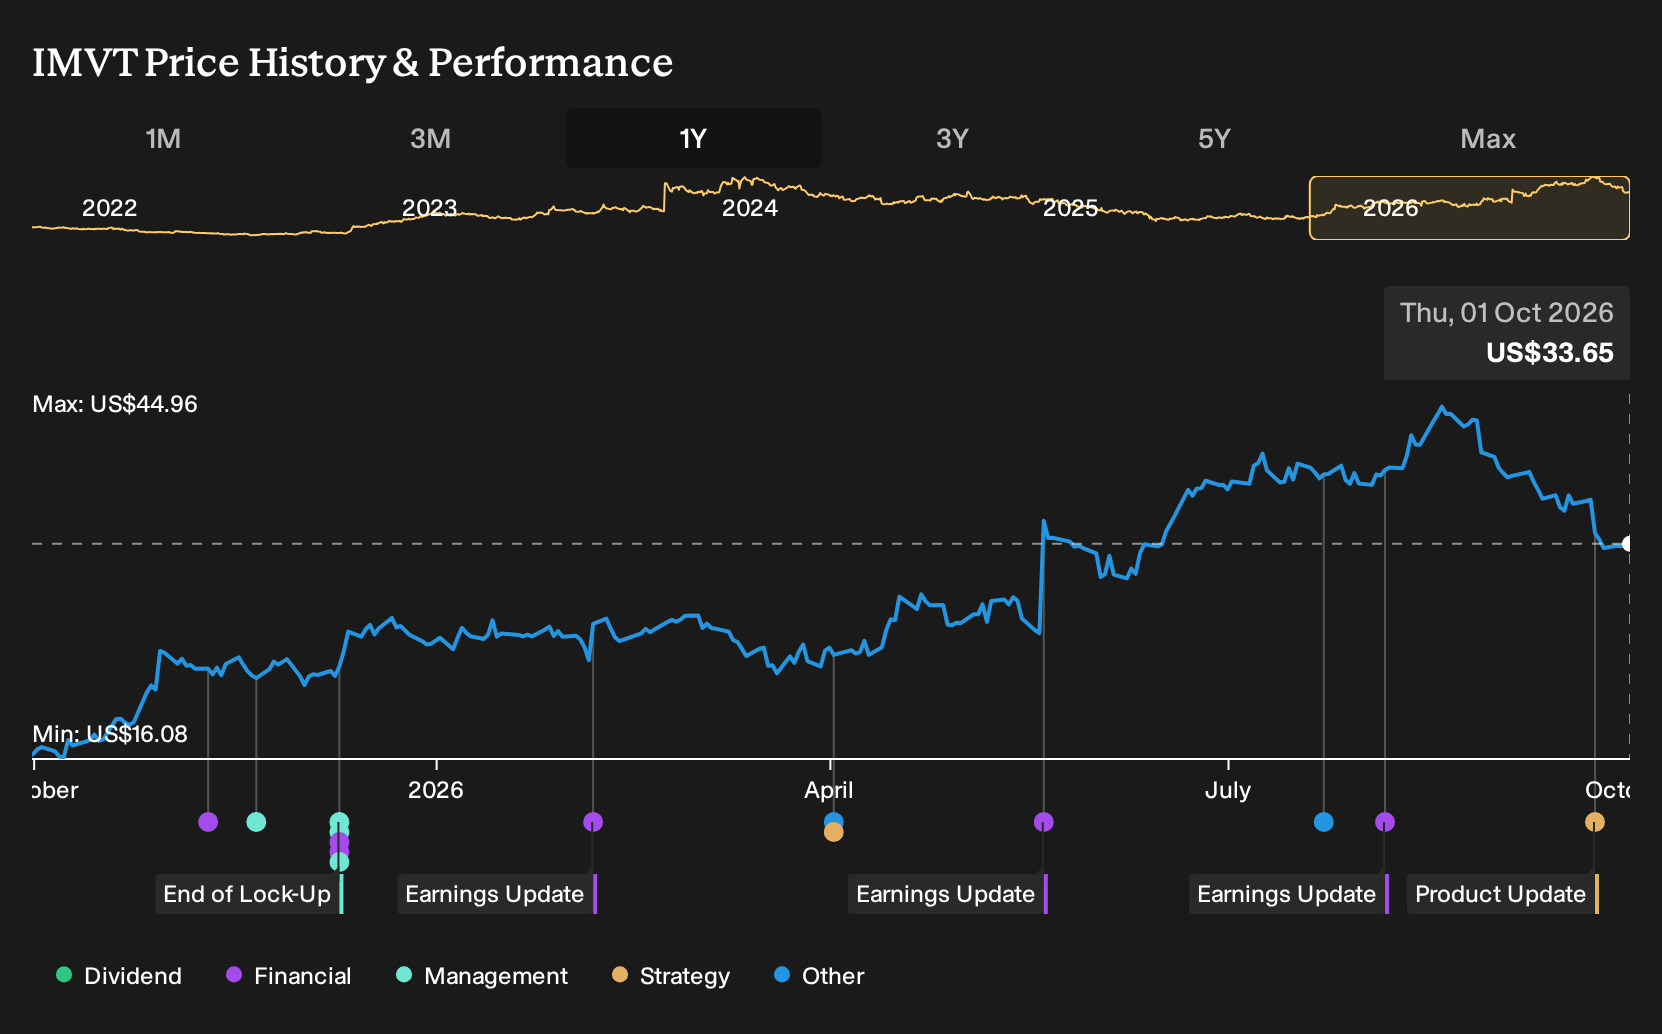
Exploring Other Perspectives
Some of the most bullish analysts on Immunovant lean hard into the D2T RA catalyst. Before this CLE setback, they were penciling in revenue of about US$955.6 million and earnings of roughly US$180.8 million by 2029. That is far more optimistic than consensus, and views like this may shift as fresh data rolls in, so compare several angles before you decide anything.
Explore another Immunovant fair value estimate, including one that suggests up to 45% potential increase from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Immunovant research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Immunovant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Immunovant's overall financial health at a glance.
Looking For More Ideas Beyond Immunovant?
Once you have a view on Immunovant, it can help to widen the lens and compare it with other opportunities that match your risk profile and income goals. The Simply Wall St Screener is a quick way to surface stocks that fit the type of portfolio you are trying to build.
- If you care most about resilient balance sheets and steady fundamentals, start with this curated list of solid balance sheet and fundamentals (25 results) that can help you focus on financial strength first.
- For investors hunting for mispriced quality, use our 28 high quality undervalued stocks to spot companies where fundamentals and market pricing appear out of sync.
- If you want ideas with strong cash generation and income potential, check the 7 dividend fortresses and compare those payouts with the rest of your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com