
Akeso (SEHK:9926) Could Be 31% Undervalued As Phase III Trial Hits Key Goals
Akeso (SEHK:9926) just put fresh clinical data at the center of its story. The company reported that its Phase III HARMONi-GI1 trial for advanced biliary tract cancer hit key survival goals.
Akeso shares have reacted quickly to the HARMONi-GI1 headlines, with a 1-day share price return of 2.26% and a 7-day move of 15.76%. This has built on a 30-day gain of 26.91%, yet the shares are still sitting on a year-to-date share price decline of 4.06% and a 1-year total shareholder return down 22.25%. This contrasts with a much stronger 3-year total shareholder return of about 3x and a 5-year total shareholder return of around 2.7x, which hints at long term believers staying engaged despite recent volatility.
Spot 617 high quality undiscovered gems that, like Akeso, are pushing late stage clinical programs and could be setting up their next big move in oncology.Bulls see Akeso as a discounted oncology platform with fresh Phase III validation. Bears point to ongoing losses and a volatile chart. Which story do the current valuation markers lean toward?
Most Popular Narrative: 31% Undervalued
Against Akeso's last close at HK$108.70, the most followed narrative pins fair value closer to HK$158. This frames recent clinical wins as part of a much bigger earnings and cash flow story built around bispecific antibodies and antibody drug conjugates.
The company's strong R&D pipeline, including advanced bispecific antibodies and ADC candidates, provides a foundation for long-term growth, setting the stage for potential increases in net margins as products move from development to commercialization.
See why 3 investors see Akeso as 31% undervalued.
Result: Fair Value of HK$158.28 (UNDERVALUED)
Still, Akeso depends heavily on a few key oncology products. Ongoing operating losses mean any setback in trials or pricing could quickly pressure the whole thesis.
Find out about the key risks to this Akeso narrative.
Another View: What Multiples Say About Akeso
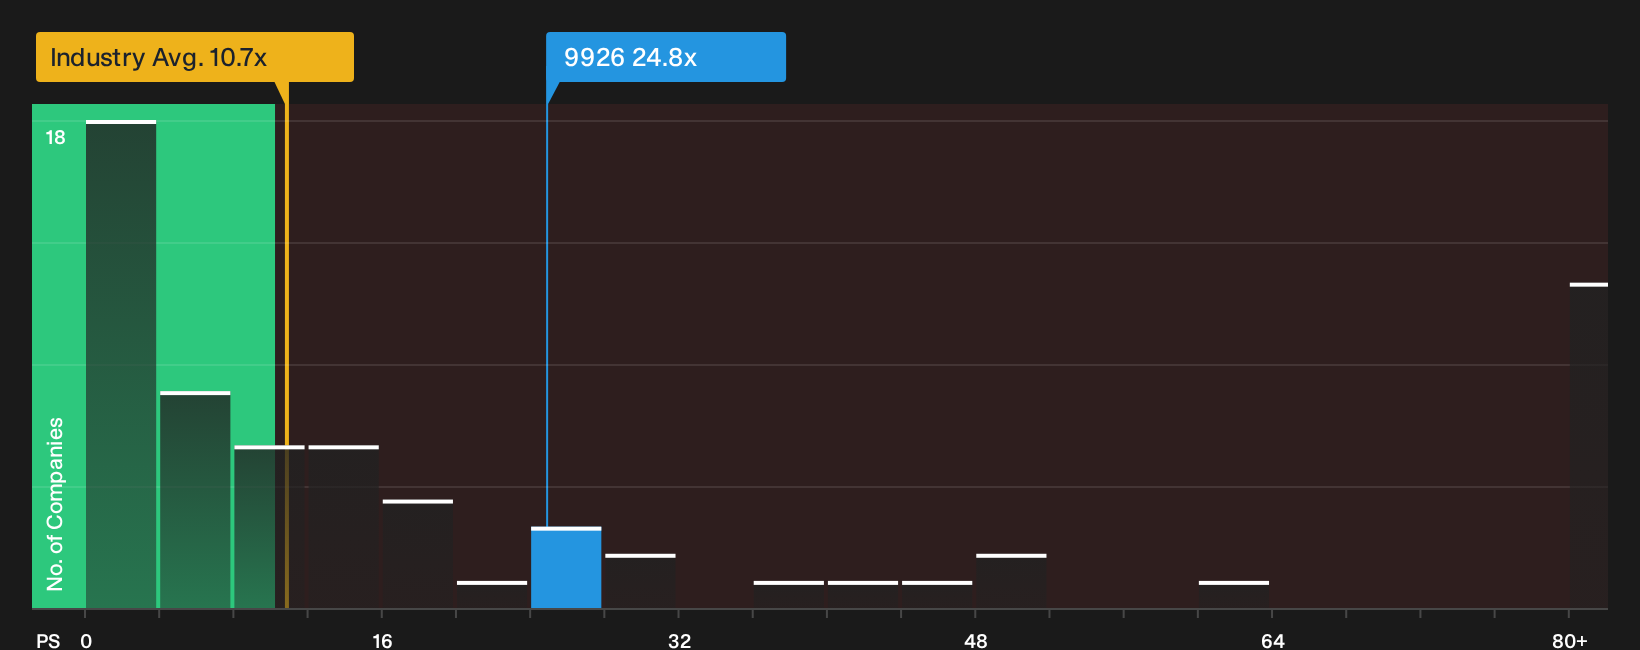
Akeso might look inexpensive compared with a HK$158 fair value line. However, the current P/S of 24.8x is far above the Hong Kong biotechs average of 10.7x and well above its own fair ratio of 13.1x. That gap suggests notable valuation risk if sentiment or growth expectations cool.
Investors considering these conflicting signals may want to examine what the numbers imply if the market moves closer to that fair ratio, and how that would change the risk reward trade off for Akeso. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
After all this, does the current Akeso mood feel too hot or too cautious to you? Act while the data is fresh and pressure test your thesis with the 2 key rewards
Looking for more ideas beyond Akeso?
If Akeso has sharpened your focus on opportunity and risk, do not stop here. Cast the net wider and pressure test your thinking across fresh candidates.
- Target potential mispricing by scanning for companies that combine quality fundamentals with attractive valuations using the 190 high quality undervalued stocks.
- Secure your downside first and hunt for resilience across businesses with stronger financial footing through the 224 resilient stocks with low risk scores.
- Spot future leaders early by reviewing the 116 elite penny stocks with strong financials before those stories become crowded.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com