
PBF Energy (PBF) Cuts Debt Sharply, Is The Rally Already Priced In?
PBF Energy (PBF) has drawn fresh attention after cutting net term debt by more than $1.4b, tightening its balance sheet while keeping capital spending disciplined and supporting expectations for strong earnings.
Recent trading shows how quickly sentiment around PBF Energy has shifted, with a 6.99% 1 day share price return feeding into a 14.52% 7 day move and a 90 day share price return of 72.22% as investors respond to lower leverage, strong asset utilization, and expectations for upbeat earnings.
Scan other balance-sheet-focused opportunities that are moving on cleaner leverage profiles and disciplined spending with our 31 resilient stocks with low risk scores curated to surface resilient businesses first.
PBF Energy has already moved sharply, and the balance sheet reset is in plain sight. The real task now is sizing up whether today’s price already reflects that progress or still leaves a margin of appeal.
Most Popular Narrative: 13.5% Overvalued
The latest narrative fair value for PBF Energy sits at $72.54, below the last close of $82.34. This puts the recent rally up against a more cautious long term view built on tempered revenue and earnings assumptions.
Analysts expect earnings to reach $1.2 billion (and earnings per share of $10.89) by about September 2029, down from $1.4 billion today. The analysts are largely in agreement about this estimate.
See why 15 investors see PBF Energy as 14% overvalued.
Result: Fair Value of $72.54 (OVERVALUED)
Still, PBF Energy’s heavy exposure to regulated coastal markets and ongoing reliability questions at Martinez could quickly challenge the current consensus on fair value.
Find out about the key risks to this PBF Energy narrative.
Another View: PBF Energy Through The Earnings Lens
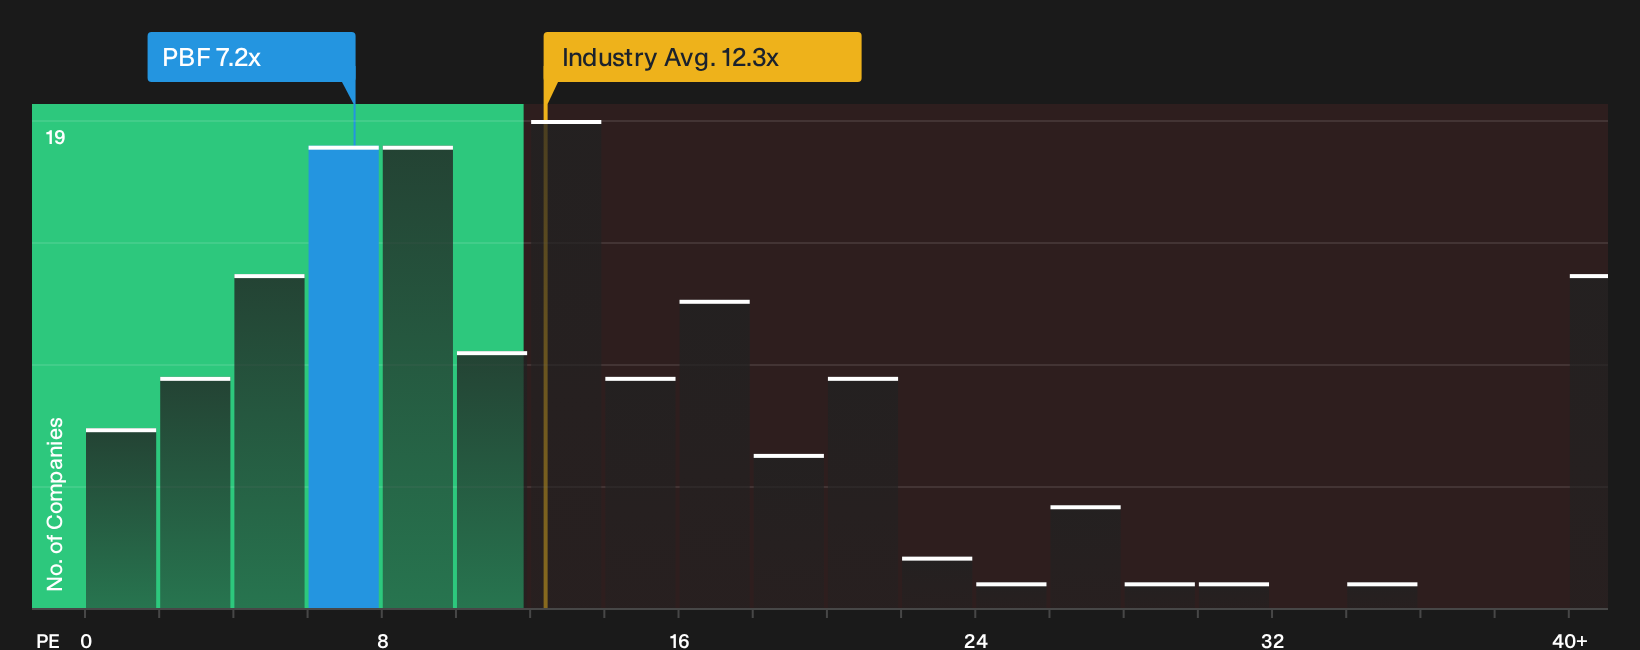
The narrative fair value paints PBF Energy as 13.5% overvalued at $82.34 against $72.54. The earnings based view tells a different story. At a P/E of 7.2x versus an estimated fair ratio of 9.4x and a peer average of 31.6x, the stock screens as cheap rather than stretched. So is the risk that expectations are too low, not too high.
That gap in multiples can cut both ways. It can signal a cushion if sentiment cools, or it can flag that the market still doubts how durable today’s profitability really is. Which side of that trade do you think you are on when you look across your portfolio, and the wider US Oil and Gas group.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling the push and pull in the PBF Energy story. Act quickly, review the assumptions behind both the risks and the upside, then weigh the 3 key rewards and 3 important warning signs.
Looking for more PBF Energy style ideas?
If PBF Energy has sharpened your focus, do not stop at a single ticker. Use the Simply Wall St screener to uncover fresh opportunities aligned with your approach.
- Target resilient opportunities by zeroing in on companies with lower perceived risk using the 31 resilient stocks with low risk scores.
- Hunt for potential mispricings by reviewing the 28 high quality undervalued stocks that combine stronger balance sheets with healthier cash flows.
- Stack your income stream by scanning the 7 dividend fortresses that offer higher yields with a focus on staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com