
How Investors Are Reacting To Pembina Pipeline (TSX:PPL) National Interest Approval
- Pembina Pipeline, alongside the Governments of Alberta and Canada and Trans Mountain Corporation, recently marked a key milestone as the Pacific Link oil pipeline was listed as a Project of National Interest under the Building Canada Act. This gives the proposal a clearer federal review path while work continues on environmental, regulatory and engineering streams.
- The arrangement limits Pembina Pipeline’s risk during development, since the company has no at-risk capital before a final investment decision and holds a 10% economic interest during construction, with an option to lift that stake to as much as 20% once Pacific Link is in commercial service.
- We will now look at how Pembina Pipeline’s investment narrative could be affected by Pacific Link’s Project of National Interest status.
Scan beyond Pembina Pipeline and identify other energy infrastructure plays that are progressing through major build outs with our hand picked 39 power grid technology and infrastructure stocks for long term capital project exposure.
Pembina Pipeline Investment Narrative Recap
To own Pembina Pipeline, you need to be comfortable with a regulated, capital intensive midstream model that leans on long life assets, fee based contracts and exposure to Western Canadian energy activity. The Pacific Link news gives the story an additional long haul growth option, but the short term swing factor still looks more tied to execution on existing pipelines, terminals and marketing volumes.
The biggest near term risk remains pressure on margins from toll resets, competition and the company’s high leverage and dividend coverage. Pacific Link’s Project of National Interest status improves process clarity but does not remove regulatory or policy uncertainty around big hydrocarbon projects, so it does not fundamentally change those core risks today.
The most relevant development to set beside Pacific Link is the ongoing push into export oriented projects such as Cedar LNG and the Prince Rupert LPG terminal. Together with a potential new West Coast oil route, Pembina Pipeline is building more direct links between Western Canadian production and overseas buyers, particularly in Asia Pacific.
For you, that clusters the catalysts in one place: execution on multiple large builds, toll and rate outcomes on existing systems, and the balance between committed growth capex and already elevated debt. If Pacific Link moves ahead on the streamlined review timeline, it slots into an already full project queue where funding, schedule control and regulatory follow through matter most.
Analyst expectations for Pembina Pipeline currently indicate CA$8.9b in revenue and CA$2.2b in earnings by 2029, based on an assumed 4.0% annual revenue growth rate and an increase in earnings of about CA$500m from approximately CA$1.7b today.
Uncover why Pembina Pipeline's fair value indicates a 13% potential upside to its current price that could narrow quickly.
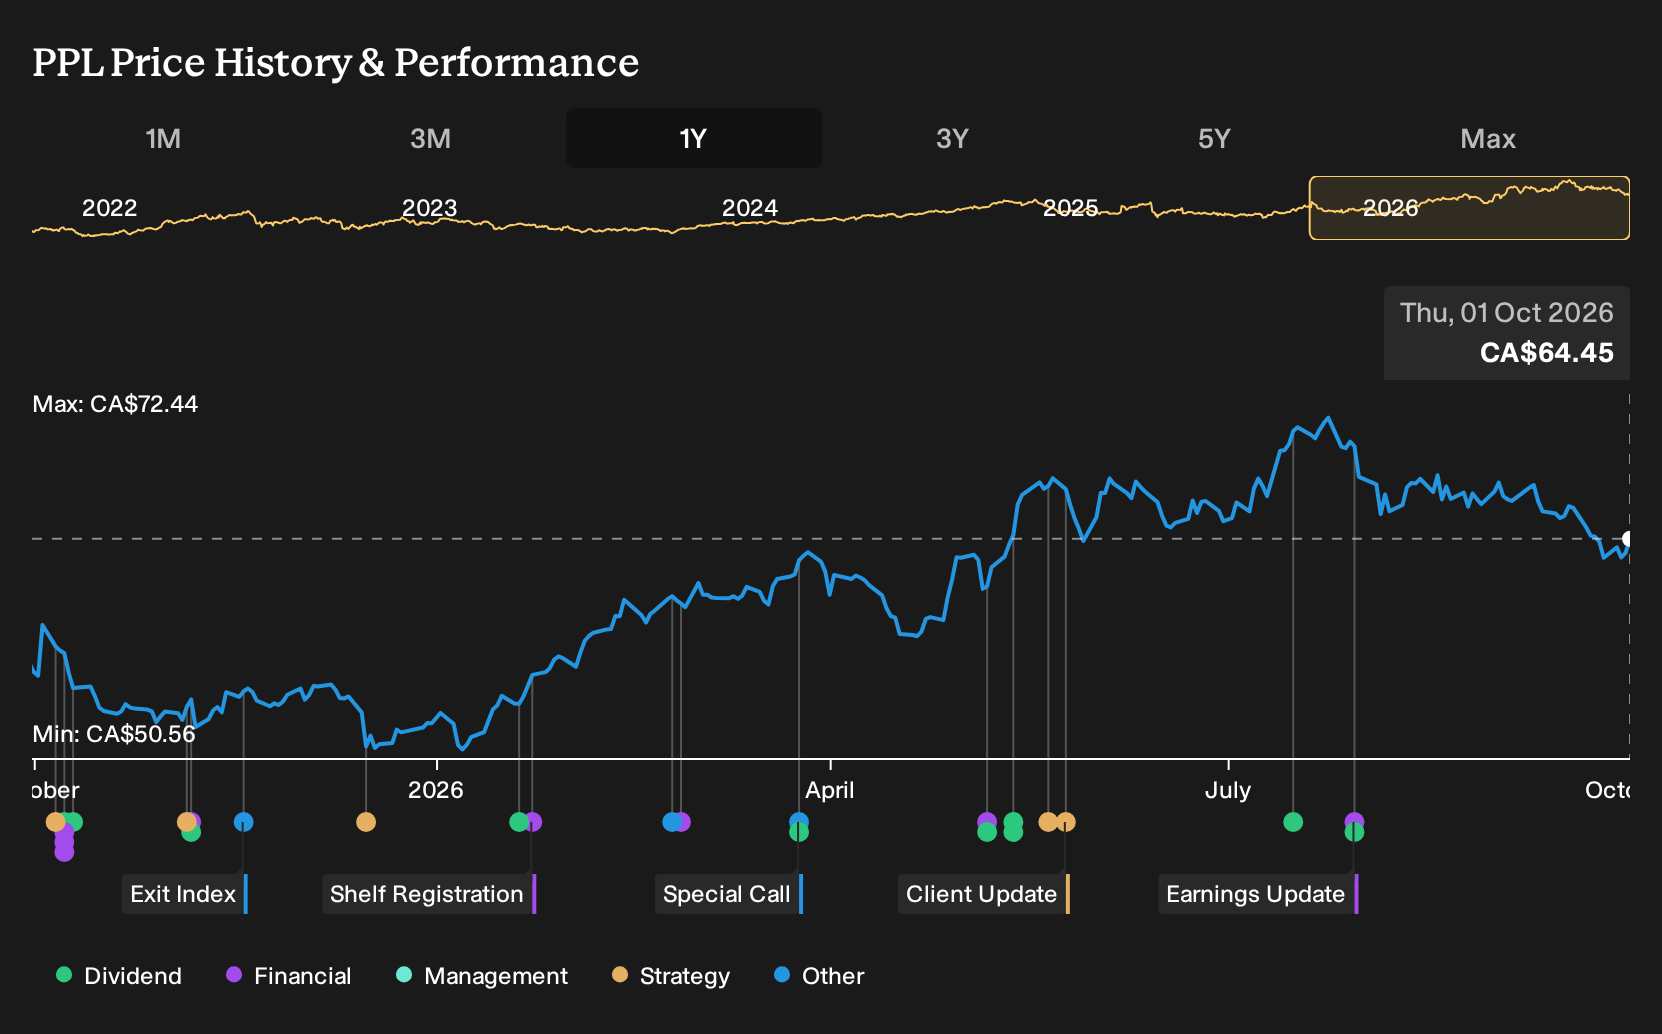
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly CA$72.72 to CA$239.41 per share, so retail opinions on Pembina Pipeline are already far apart. When you factor in the pre Pacific Link risks around toll resets, competition and heavy project spending, you get a wide field of views worth exploring before deciding where you stand.
Explore 2 other Pembina Pipeline fair value estimates, including one that suggests as much as 271% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Pembina Pipeline research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pembina Pipeline. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pembina Pipeline's overall financial health at a glance.
Looking For More Ideas Beyond Pembina Pipeline?
If the Pacific Link story has you thinking about how Pembina Pipeline fits into a broader portfolio, it can help to line it up alongside other opportunities with different cash flow profiles, balance sheets and risk levels. The Simply Wall St Screener gives you a quick way to do that without getting buried in spreadsheets.
Below are a few angles you can use to widen your watchlist and pressure test your thesis on Pembina Pipeline against other options.
- If you want to focus on resilient businesses, start by checking out a group of companies screened for lower risk profiles through the 9 resilient stocks with low risk scores and see how their volatility and fundamentals compare to what you are seeing with Pembina Pipeline.
- If income is a priority, line up Pembina Pipeline against a curated set of higher yielding options by scanning the 1 dividend fortresses and checking how those payouts stack up on coverage and consistency.
- If you are hunting for opportunities that are not yet heavily followed, broaden your research with a focused 9 high quality undiscovered gems that highlights businesses with solid fundamentals which may not be on every investor’s radar yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com