
Wayfair (W) Launches Wayfair Delivers, Is The Stock Still Undervalued?
Wayfair Delivers campaign puts brand and customer experience in focus
Wayfair (W) has rolled out its new “Wayfair Delivers” brand platform, tying quality, value and logistics into a single message that now sits in front of millions of NFL viewers.
The campaign leans on a Stafford family spot during Monday Night Football and additional placements across ABC, ESPN, CBS and NBC. For investors, the move highlights how management is choosing to spend marketing dollars and what it wants shoppers to remember about the business.
Wayfair’s campaign lands at a moment when the share price has climbed 7.98% over the past month and 7.27% over 90 days, yet remains down 4.87% on a year to date share price basis. At the same time, the 1 year total shareholder return of 17.39% and 3 year total shareholder return of 84.14% point to momentum that has played out over a longer horizon than the latest advertising push.
See how Wayfair compares with other potential breakout opportunities by reviewing our curated list of 28 high quality undervalued stocks.
Wayfair’s recent run and fresh brand push put you at a fork in the road. Is this the moment to lean in, or does the current price argue for patience while the valuation case is unpacked next?
Most Popular Narrative: 18% Undervalued
Wayfair’s most followed valuation narrative puts fair value at $123.34 against a last close of $101.37. This frames the current ad push against expectations for profitability and cash generation, not just brand buzz.
Wayfair's proprietary logistics network, CastleGate, is expected to provide a meaningful growth unlock by improving efficiency and customer experience, which can positively impact revenue growth through higher conversion rates and potentially improved net margins. The launch of Wayfair Verified and new merchandising initiatives like personalized promotions are aimed at enhancing customer trust and user experience, potentially driving higher sales and revenue per unit through increased customer engagement and conversion rates.
See why 15 investors see Wayfair as 18% undervalued.
Result: Fair Value of $123.34 (UNDERVALUED)
Still, Wayfair’s reliance on heavy advertising spend and a soft housing market could pressure margins and limit demand if consumer appetite for big ticket home goods weakens.
Find out about the key risks to this Wayfair narrative.
Another View on Wayfair’s Valuation
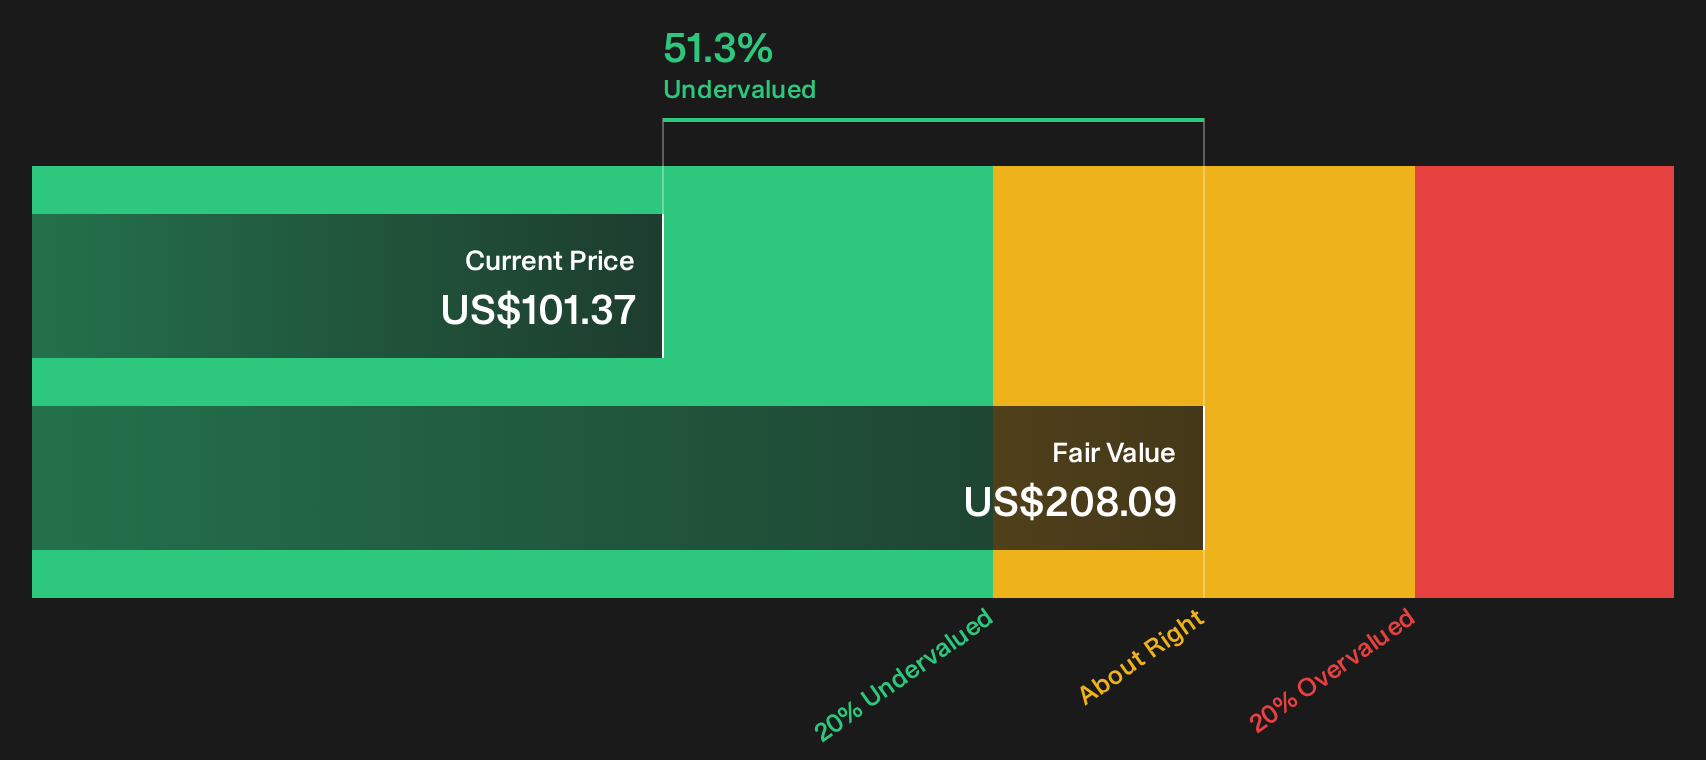
Wayfair screens as good value on future cash flows, with our DCF model putting fair value at $208.09 against a share price of $101.37. That gap points to a wide modeled upside, but it also raises a question: Are you comfortable with how much of that story depends on long range assumptions?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the mixed tone of Wayfair’s story so far leaves you torn, review the information while it is still current and form your own judgment using the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Wayfair?
If Wayfair has sharpened your appetite for opportunities, do not stop here. Spread your research across other potential setups that could fit your style and risk profile.
- Target growth potential in smaller companies by scanning the 8 elite penny stocks with strong financials and see which ones meet your return and risk tolerance rules.
- Strengthen your watchlist with businesses priced below their estimated worth by reviewing the 28 high quality undervalued stocks before the crowd catches up.
- Focus on financial durability and lower volatility by filtering through the 31 resilient stocks with low risk scores so you are not caught off guard when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com