
Dynatrace (DT) Draws Fresh Activist Attention, Is The Stock Fully Valued?
Investor Activism Sparks Fresh Focus on Dynatrace
Pictet Asset Management’s new engagement with Dynatrace (DT) on September 25, 2026, has drawn fresh attention to how the software group manages its business practices and long term shareholder value.
Investors have already been leaning into Dynatrace ahead of Pictet’s engagement. The company has a 90-day share price return of 32.37% and a year-to-date share price gain of 39.93%. Meanwhile, the 1-year total shareholder return of 18.81% and the 5-year total shareholder return, which declined 17.53%, show that recent momentum contrasts with a tougher longer track record.
Spot emerging peers that could see similar engagement to Dynatrace by scanning our hand picked 31 resilient stocks with low risk scores.Bulls see Pictet’s engagement and recent gains as a sign that Dynatrace is only now catching up to its potential, while bears point to the weaker 5 year record. Which story does the current valuation back up?
Most Popular Narrative: 1% Undervalued
The most followed narrative pegs Dynatrace’s fair value at $59.71, which is close to the last close of $59.26, and uses an 8.61% discount rate to weigh long term cash flows against today’s price.
The company's unified platform approach, particularly the growing success of Grail-powered log management (over 100% YoY log consumption growth and targeting $100M in annualized consumption), is driving multi-product adoption and higher customer stickiness. This is expected to support net retention rates, recurring revenue, and long-term earnings predictability.
See why 52 investors see Dynatrace as 1% undervalued.
Result: Fair Value of $59.71 (UNDERVALUED)
Still, this hinges on Dynatrace keeping its AI edge, fending off heavyweight cloud rivals, and managing the revenue hit if large enterprise deals get delayed.
Find out about the key risks to this Dynatrace narrative.
Another View: Dynatrace Looks Pricey On Earnings Multiples
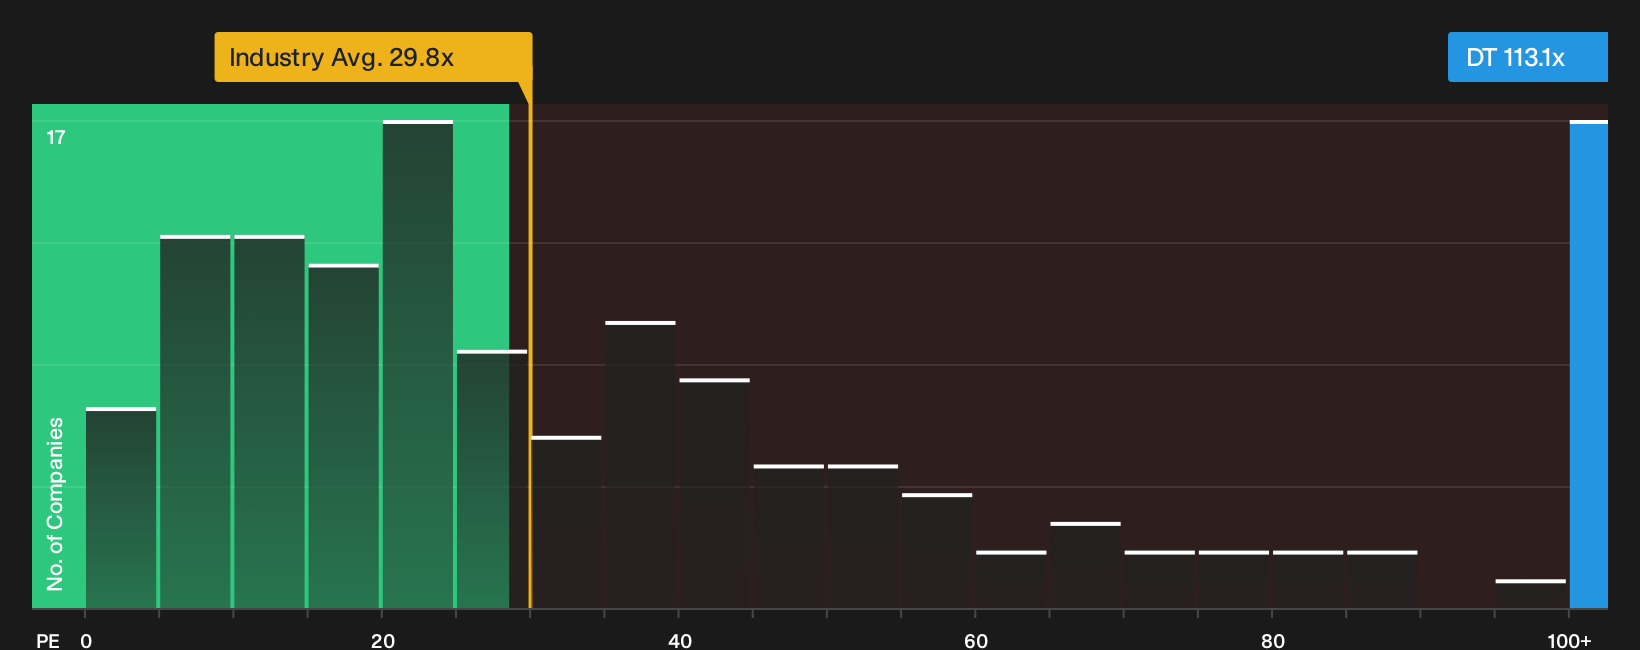
The DCF-based fair value narrative paints Dynatrace as modestly undervalued, yet the earnings multiple tells a much sharper story. Dynatrace trades on a P/E of 113.1x, versus 29.8x for the US Software industry, 33.7x for peers, and a fair ratio of 35.9x.
That spread implies investors are paying a hefty premium for future execution, with limited room for disappointment if growth or margins fall short. The question is whether you see that premium as disciplined conviction or valuation risk that is hard to ignore.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Dynatrace can feel messy, yet that is exactly when your own work matters most. Take a closer look at both sides of the debate and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Dynatrace?
If Dynatrace has your attention, do not stop there. Use this momentum to scan for other opportunities that fit your risk, return, and income goals.
- Target potential mispricings by running through a curated set of companies that screen as quality yet potentially overlooked using the 28 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with cleaner balance sheets and sturdier fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Lock in potential cash flow from equities that emphasise income by checking companies that pass the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com