
Is Veracyte (VCYT) Still Undervalued After New Prostate Test Data?
Veracyte has delivered a very strong 107.0% share price gain over the past three years, which naturally raises a question for anyone looking at the stock today. Is the current US$44.19 price still grounded in the cash flows the business is expected to generate, especially as new clinical data rolls in?
- The share price rise of 107.0% over three years puts a lot more weight on whether the underlying cash generation can eventually catch up with what the market is paying.
- Fresh data around the Decipher Prostate Genomic Classifier, including phase III results and multiple upcoming studies, can influence expectations for future test adoption, and with it the timing and scale of cash flows that might be available to equity holders.
- If you'd rather focus on earnings, this one's for you. See why Veracyte's 31.0x P/E tells a different valuation story.
The issue now is whether the cash flows implied by Veracyte's current business and pipeline are sufficient to justify the price that investors are being asked to pay today.
If you want more ideas built around cash flow and clinical pipelines rather than just one ticker, a focused screen of 35 healthcare AI stocks can be a useful next step.
Is Veracyte Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) approach used here focuses on the cash Veracyte can return to shareholders over time and then discounts that back to today. Veracyte generated about $165.9 million of free cash flow over the last twelve months, and the model assumes this pool of cash continues growing rather than shrinking, with projections stepping up through the next decade.
Based on that cash profile, the DCF output points to an estimated intrinsic value that is substantially above the current US$44.19 share price. Because recent phase II and phase III data around the Decipher prostate test add more visibility on potential test usage and pricing, the market reaction so far helps explain why the price still sits below what the cash flow model implies. Find out what Veracyte could be worth using our Discounted Cash Flow (DCF) estimate.
The Veracyte Narrative: What Would Justify Today's Price?
Narratives for Veracyte pick up where the cash flow puzzle leaves off, by spelling out the specific combinations of growth, profitability and earnings power that would need to hold for the shares to be worth meaningfully more or less than today. Each one treats Veracyte's fair value as a thesis about how the business might develop over time. This allows you to see how that story holds up as new data and results appear on Simply Wall St's Community page.
One of the top community narratives on Veracyte: 22% undervalued
"Expanding cancer diagnostics portfolio and clinical evidence are driving greater physician adoption, market penetration, and long-term top-line growth…"
Discover why this Narrative puts Veracyte at 22% undervalued.
One more piece of the Veracyte puzzle to check
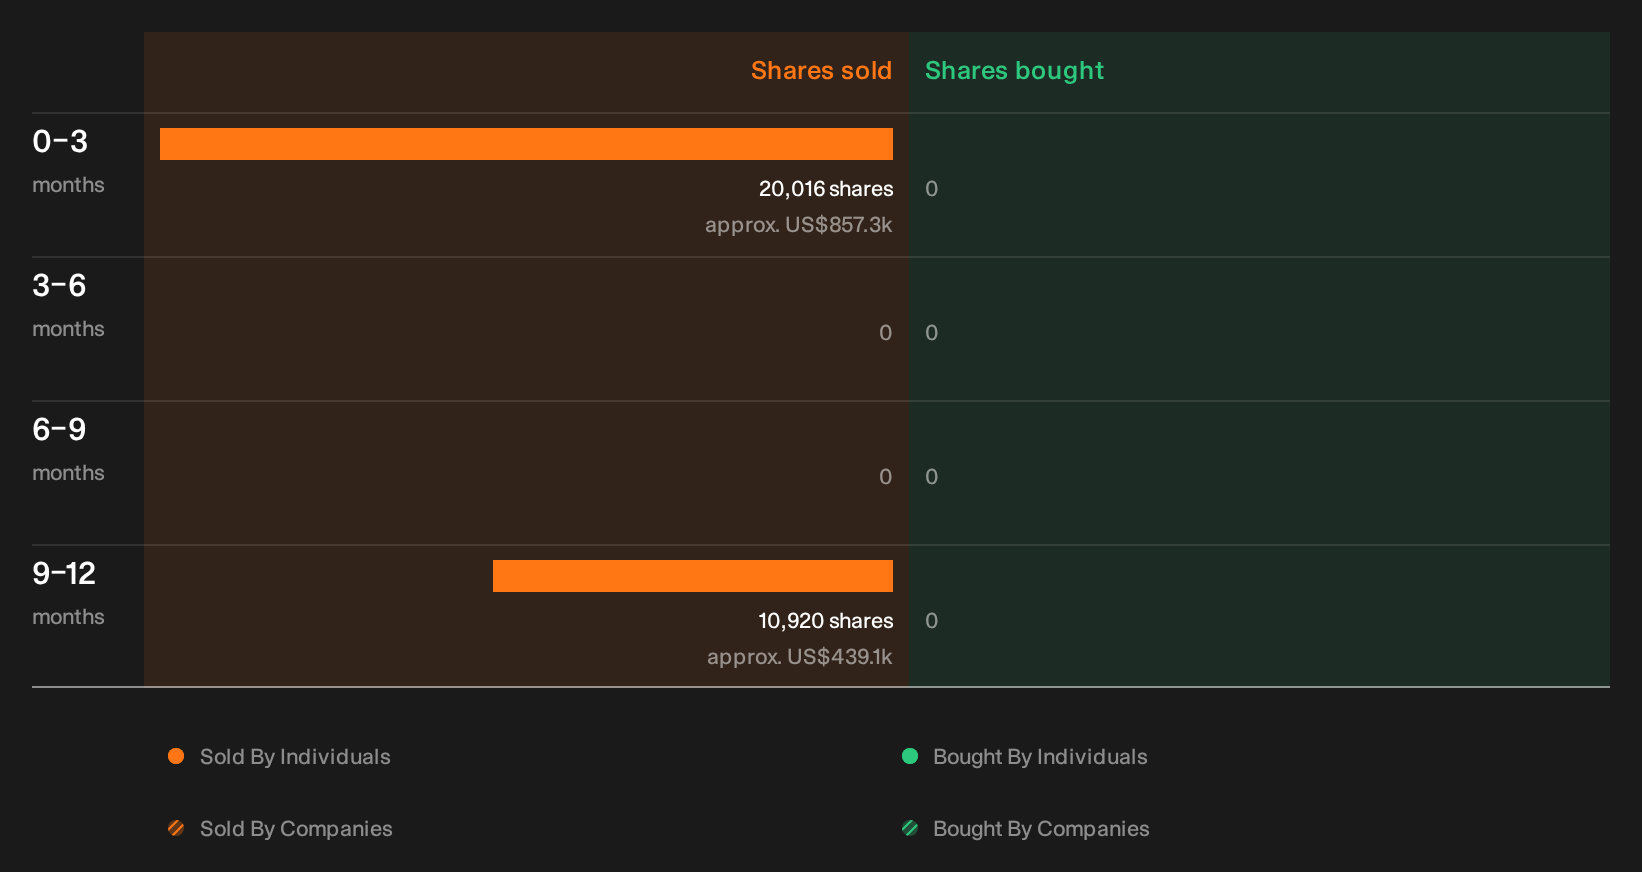
Before you put too much weight on any valuation work for Veracyte, it is worth knowing that internal share transactions have triggered a separate flag, with the decision makers, size of sales and possible takeaways still sitting in the detail. See the recent insider selling flagged for Veracyte.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com