
How Investors May Respond To AltaGas (TSX:ALA) Closing $750 Million Notes Offering
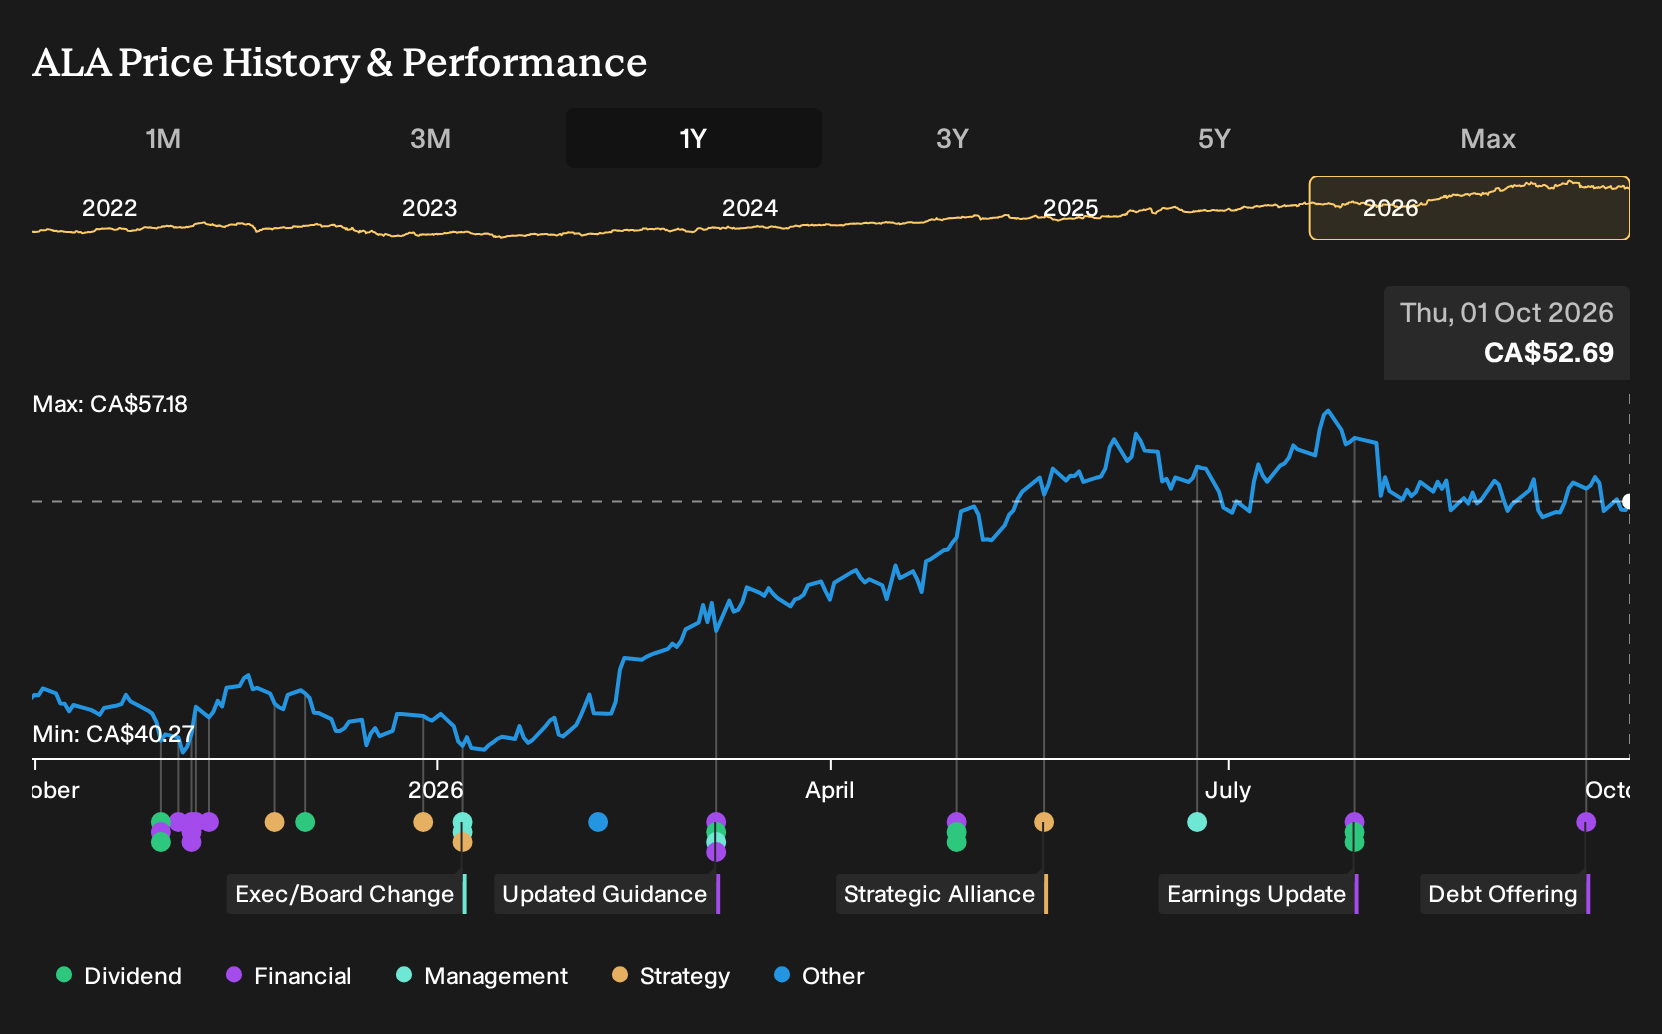
- AltaGas, through its U.S. subsidiary, recently completed a US$750 million issue of 5.75% senior unsecured notes due 2031, fully guaranteed by the parent and earmarked for general corporate purposes including refinancing existing debt.
- The refinancing focus suggests AltaGas is prioritizing balance sheet flexibility and interest cost management rather than funding new growth projects with this US$750 million tranche.
- We will now look at how AltaGas's investment narrative could shift as it layers on US$750 million of new senior unsecured notes.
Scan how AltaGas's balance sheet moves compare with peers by checking a curated list of list of solid balance sheet and fundamentals (7 results) that may handle refinancing pressure in their own way.
AltaGas Investment Narrative Recap
To own AltaGas, you need to be comfortable with a utility and midstream business that leans on long lived infrastructure, regulated returns, and an LPG export platform tied to Asian demand. The key near term swing factor is execution on utility modernization and exports, without letting costs and regulatory friction erode earnings. The fresh US$750 million in senior unsecured notes mostly reflects refinancing activity rather than a change in the operating story.
The biggest risk many investors will watch is still leverage and interest coverage, especially with interest payments currently not well covered by earnings and the dividend not fully backed by free cash flow. This debt issue does not remove that concern. It simply resets some maturities and keeps AltaGas funded while it pursues grid upgrades, LPG export capacity, and potential capital recycling.
The most relevant development here is the closing of the US$750 million 5.75% senior notes due 2031, fully guaranteed by AltaGas and ranking equally with existing senior unsecured obligations. Proceeds are earmarked for general corporate purposes, including paying down the credit facility and possibly redeeming or repurchasing medium term notes, so the primary operational levers remain utilities and midstream execution.
For you as a shareholder or potential buyer, this matters mainly because it supports continued access to capital for utility modernization and export projects that analysts often associate with earnings potential. It also keeps refinancing risk in focus. Interest costs, regulatory outcomes on rate recovery, and how efficiently AltaGas recycles capital into higher return projects remain central to whether the current balance between rewards and risks appears acceptable.
AltaGas' current investment setup is based on analyst expectations that revenues will reach CA$16.4b and earnings will reach CA$1.0b by 2029. This implies 6.2% yearly revenue growth and an earnings increase of about CA$385.0m from CA$615.0m today.
Uncover why AltaGas' fair value indicates a 14% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$60 to US$92 per share, which already shows how far apart retail estimates on AltaGas can sit. These opinions pre date the new 5.75% notes, so you should weigh them against refinancing needs, policy risk, and export exposure, then explore more viewpoints.
Explore another AltaGas fair value estimate, including one that suggests as much as 74% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AltaGas research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AltaGas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AltaGas' overall financial health at a glance.
Looking For More Investment Ideas Beyond AltaGas?
Once you have a handle on AltaGas, it can help to line it up against other potential opportunities using a consistent framework. The Simply Wall St Screener lets you compare balance sheets, income profiles, and risk factors across a wide set of businesses so your watchlist is built on evidence rather than hunches.
- If capital preservation is high on your list, start with companies that show resilient financial profiles by checking a 9 resilient stocks with low risk scores that may hold up better when conditions get tougher.
- For investors focused on returns backed by strong fundamentals, broaden your search with a 9 high quality undiscovered gems that combines quality metrics with solid underlying cash flows.
- If income is the priority, focus on cash generators that pay out meaningfully by scanning a curated group of 1 dividend fortresses that currently yield 5% or more.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com