
Does Mario Giannini Retirement Change The Bull Case For Hamilton Lane Stock?
- Hamilton Lane announced that long-time leader and current Executive Co-Chairman Mario Giannini will retire on March 31, 2027, after more than three decades shaping the firm's strategy, expansion and 2017 IPO.
- Giannini's planned exit removes one of private markets' most influential data-focused voices and raises practical questions about Hamilton Lane's leadership continuity and decision-making culture beyond his 2027 Market Overview.
- We will look at how Hamilton Lane's investment narrative interacts with Giannini's planned retirement and the leadership continuity it implies.
Compare Hamilton Lane's leadership transition with other asset managers by scanning a hand picked set of list of solid balance sheet and fundamentals (25 results) that may weather executive changes with fewer surprises.
Hamilton Lane Investment Narrative Recap
To own Hamilton Lane, you need to be comfortable with a private markets specialist that leans heavily on fee earning assets, evergreen vehicles and technology enabled solutions. The big swing factor in the near term is how fundraising and net inflows hold up, especially after a year where the share price is down sharply and 1 year returns trail both the US market and the Capital Markets industry.
Mario Giannini's retirement looks well telegraphed and follows the move to co CEOs in 2023, so the headline itself does not obviously change near term business drivers. The more immediate risk still sits with regulatory complexity, fee pressure and rising competition as Hamilton Lane scales customized and global products, which can lift costs faster than revenue if execution slips.
The most relevant backdrop to this leadership change is the firm's push into evergreen and specialized funds, plus technology and data offerings that already generate revenue and support client stickiness. Those are the areas investors often watch as practical catalysts, since they influence fee related earnings and how predictable cash flows feel when markets are choppy.
Giannini stepping away in 2027 puts more focus on how Juan Delgado Moreira, Erik Hirsch and the broader team keep that product pipeline and distribution build out on track. If regulatory demands or operational complexity tied to global expansion grind higher, the concern is less about the transition headline and more about whether margins, fundraising momentum and execution around new vehicles can hold up without his influence in the room.
Hamilton Lane's narrative projects US$1.1b revenue and US$496.8 million earnings by 2029. This assumes 13.9% yearly revenue growth and an earnings increase of about US$247.6 million from US$249.2 million today.
Discover how Hamilton Lane's fair value points to a 46% potential upside from its current price before the gap begins to close.
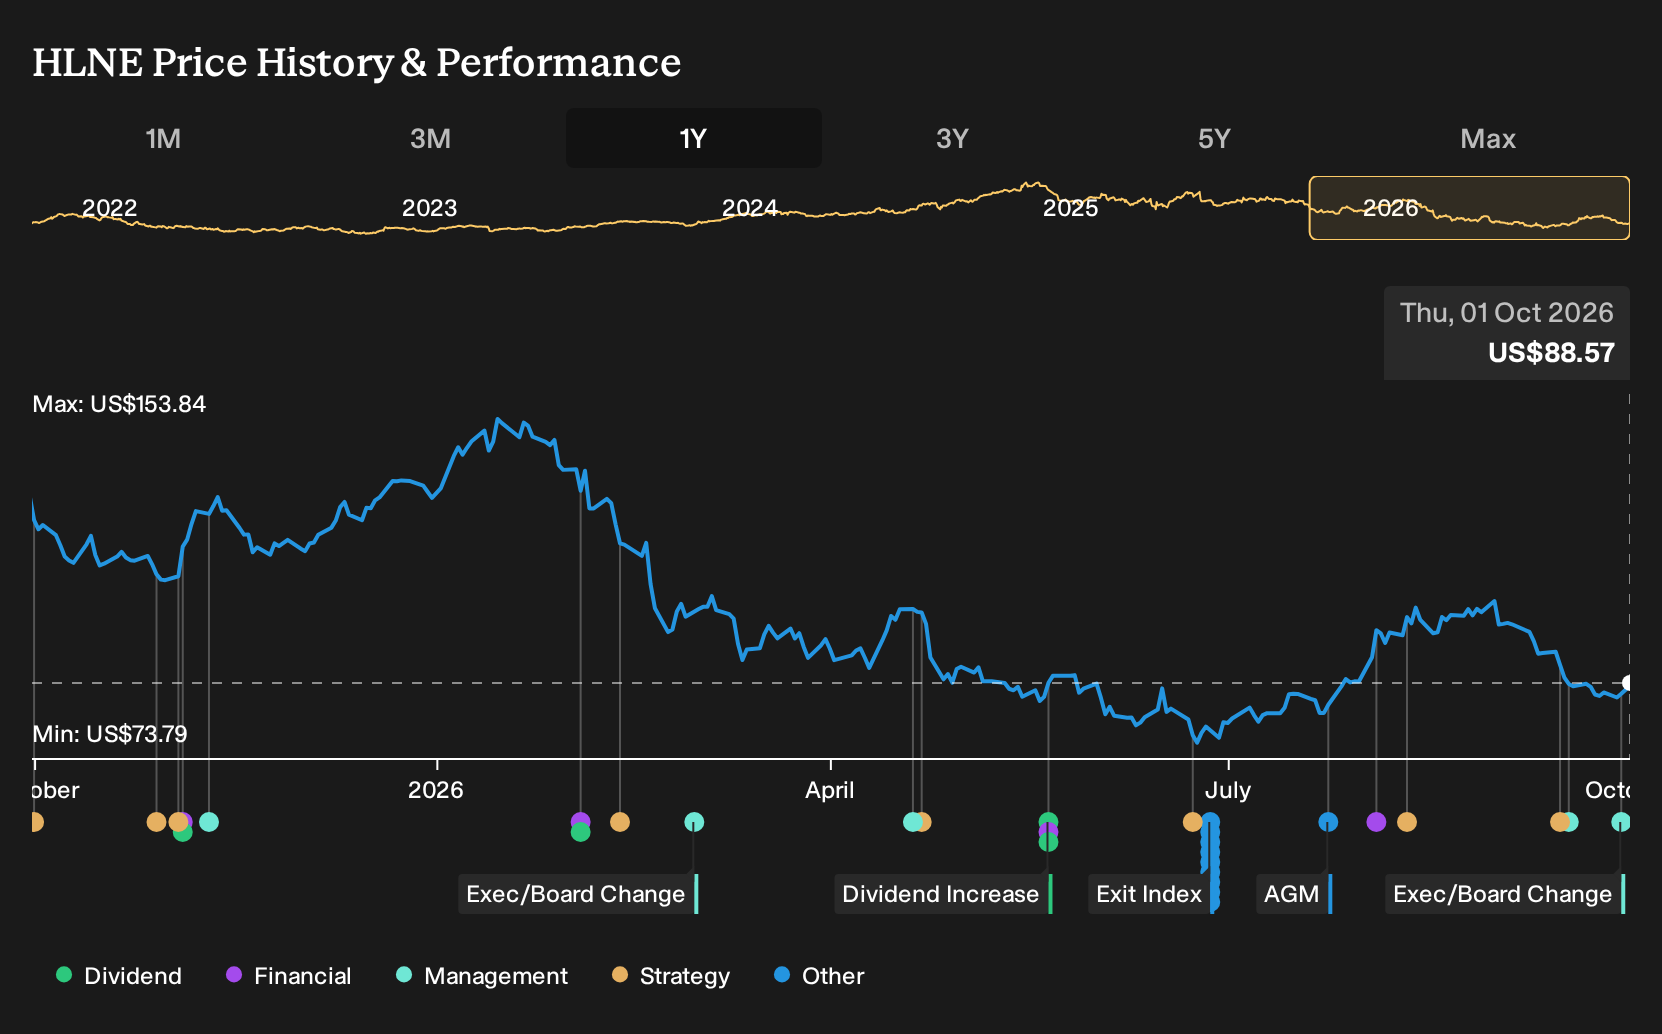
Exploring Other Perspectives
For Hamilton Lane, the sharpest contrast comes from the more pessimistic view that Evergreen and specialized funds could see choppier flows, which might squeeze fee related earnings if liquidity needs rise. The lowest analysts were penciling in about US$1.2b of 2029 revenue and US$520.8 million of earnings before this retirement news, so their narrative may still evolve.
Explore 8 other Hamilton Lane fair value estimates, including one that suggests as much as 18% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Hamilton Lane research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hamilton Lane. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hamilton Lane's overall financial health at a glance.
Looking for more investment ideas beyond Hamilton Lane?
Once you have a view on Hamilton Lane, it often helps to line it up against a wider watchlist so you can see where the risk and income profile really suits you best.
- If you want potential mispricing combined with solid fundamentals, scan our curated set of 28 high quality undervalued stocks that share strong cash generation and balance sheet support.
- For investors who prioritize income, review a targeted group of 7 dividend fortresses that focus on higher yields with an emphasis on resilience.
- If capital preservation and a smoother ride matter most, filter for a curated pool of 31 resilient stocks with low risk scores that aim to keep volatility and business risk contained.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com