
Afya (AFYA) Stock Looks Cheap Following A Fresh Merger Agreement
Afya has been under pressure for a while, and the latest merger agreement with Yduqs Participações S.A. puts a fresh spotlight on whether the current share price lines up with what the business is earning. With the stock drifting lower in recent years, the key issue for investors is how much of Afya's earnings power is already baked into today's valuation.
- Afya's share price has fallen 34.2% over the past 5 years, which raises a clear question about how the market is weighing its earnings profile against the risks in the business.
- The planned merger with Yduqs may reshape Afya's future earnings mix and capital structure, which can change how investors think about the durability and timing of its profit stream.
- The analysts covering Afya have run their own numbers. See what analysts think Afya's shares could be worth.
The issue now is whether Afya's recent share price, after years of weaker returns and a pending merger, is appropriately reflecting the earnings that the combined business can generate.
To understand how Afya's earnings setup compares with other opportunities, it can be helpful to compare it with 28 high quality undervalued stocks.
Does Afya Look Undervalued on Earnings?
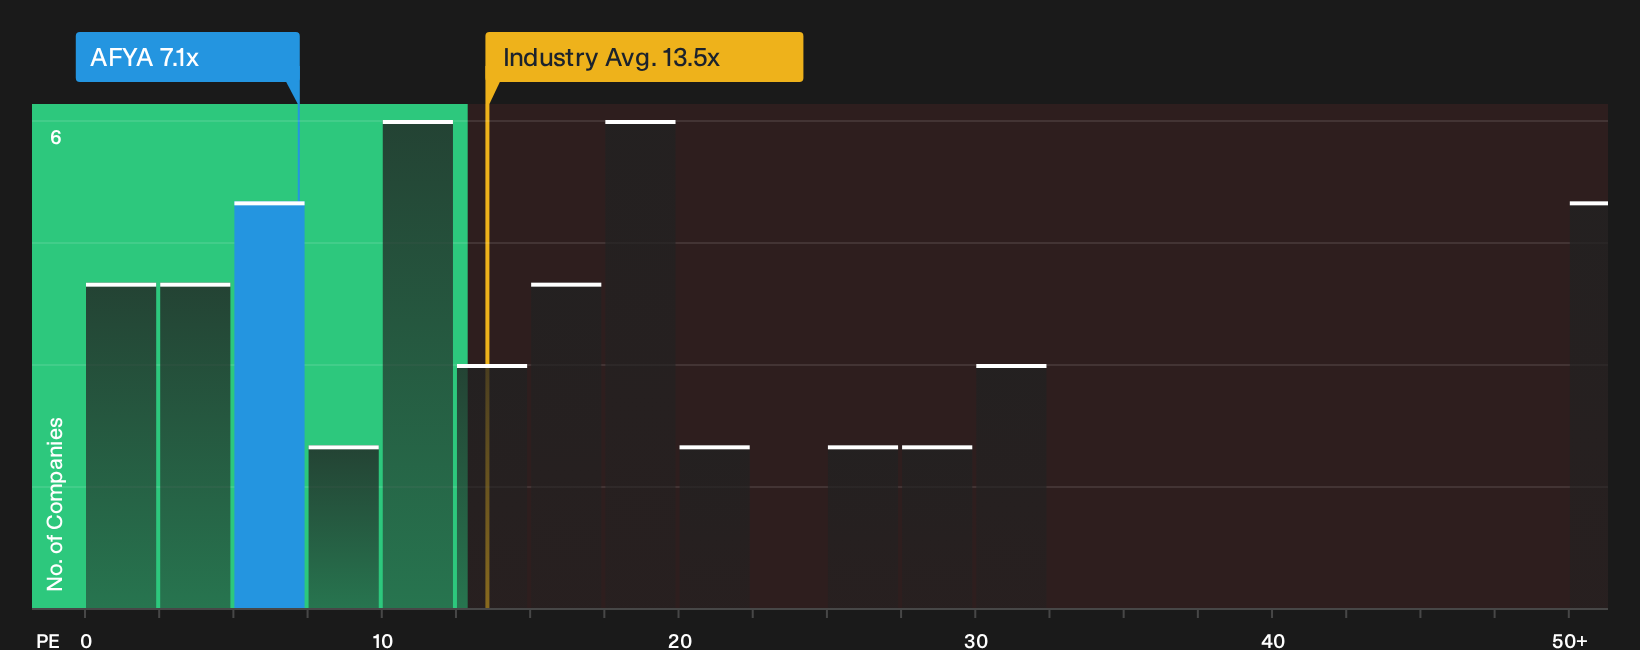
The P/E ratio is a natural fit for Afya because earnings are a central anchor for how this education group is being valued around the merger story. Afya trades on roughly 7.1x P/E, which is well below the Consumer Services industry average of about 13.5x and also under the peer group around 21.3x. On the model that looks at Afya’s own growth profile, margins, size and risk, that gap points to the shares pricing in a discount versus what the business characteristics alone would suggest.
Because the merger with Yduqs would move the combined entity to a single listing on B3 in Brazil, this depressed P/E implies that, despite the announced transaction, the market is still applying a cautious earnings multiple to Afya relative to sector and peer benchmarks. For anyone weighing the merged group’s prospects, the current P/E leaves room to question whether that caution is too strong or simply a reflection of the execution and integration risks that come with a deal of this kind. Explore the numbers behind Afya's P/E valuation.
The Afya Narrative: What Would Justify Today's Price?
Afya’s valuation puzzle sets up the role of Simply Wall St Narratives, which map out the kind of future on growth, margins and earnings that would need to play out for the stock to be worth materially more or materially less than it trades for today, and they sit on the company’s Community page. Instead of giving a single output like one P/E based estimate, Narratives unpack the earnings path behind that figure so you can later judge whether Afya’s actual progress is matching the story or drifting away from it.
One of the top community narratives on Afya: 18% undervalued
"Rapid growth of AI-powered and online education threatens Afya's traditional offerings, increasing competition and risking erosion of market share and pricing power..."
Discover why this Narrative puts Afya at 18% undervalued.
One more Afya check that sits alongside the earnings multiple
Price ratios only tell you what Afya costs today, while analyst models sketch out where they expect revenue, profit and cash flow to be a few years from now. This gives you a different benchmark to compare against the current tag. Explore where analysts expect Afya to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com