
Has Plug Power (PLUG) Fallen Far Enough To Justify Its Sales Valuation?
Plug Power has been busy signing new electrolyzer deals and expanding its hydrogen footprint, yet the share price has fallen sharply over recent years, which puts a spotlight on whether today's valuation still lines up with its sales base.
- Plug Power shares have fallen 92.8% over the past 5 years, which raises a clear question about how much revenue investors are currently paying for.
- New agreements to supply GenEco electrolyzers to projects in Europe, the Americas and Asia can shape how quickly Plug Power converts its project pipeline into recognized sales and future cash inflows.
- Your read on Plug Power is one view; the desks covering it have another. See what analysts think Plug Power's shares could be worth.
The issue now is whether Plug Power's current share price is justified by the level and trajectory of its sales.
For a broader starting point alongside Plug Power's hydrogen story, you could also run a focused screen across 39 power grid technology and infrastructure stocks.
Is Plug Power Getting Expensive on Sales?
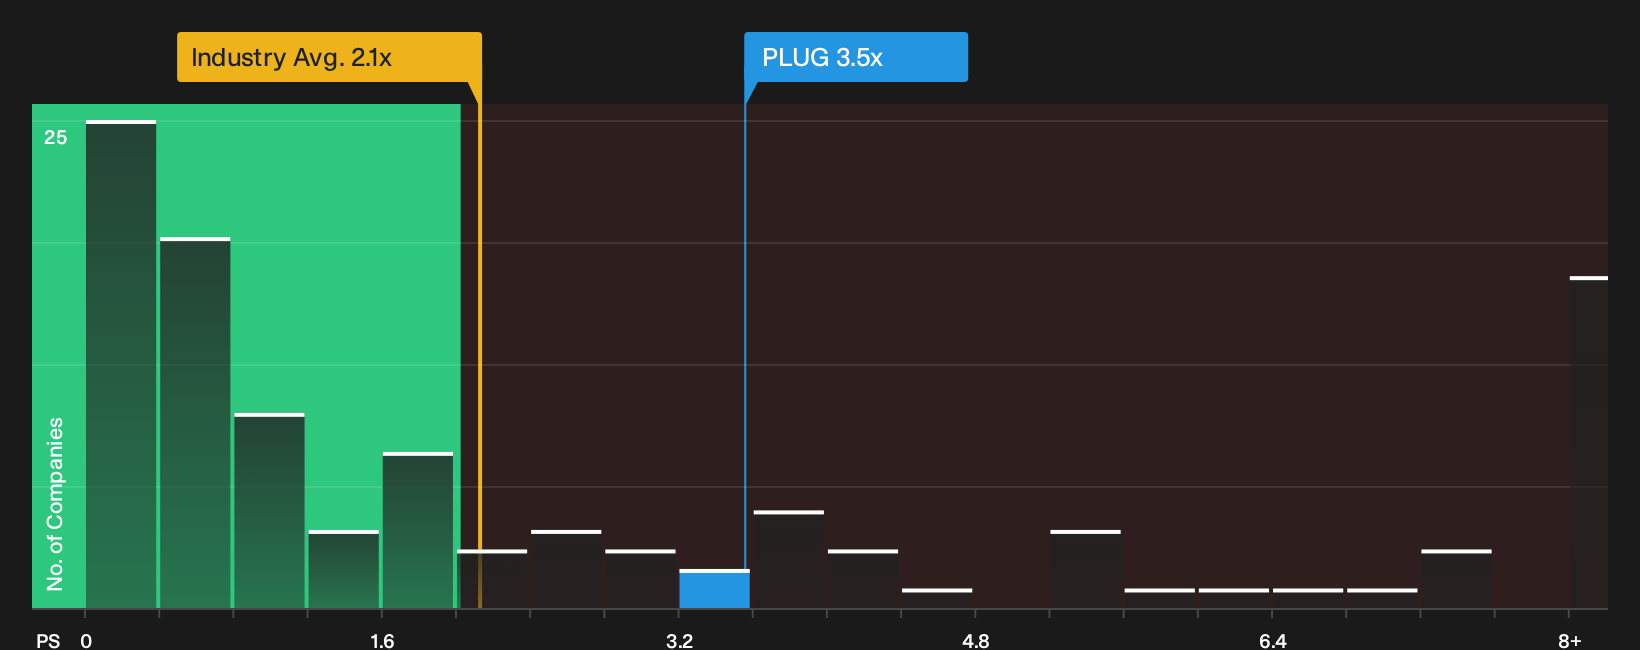
P/S is usually a cleaner yardstick for Plug Power because losses make earnings-based metrics hard to read. On this measure, the stock trades on a P/S of 3.5x, compared with an Electrical industry average of about 2.1x and a peer group around 1.9x. That means the market is currently paying a higher price for each dollar of Plug Power revenue than for many similar businesses.
Plug Power screens overvalued on this framework, since the current P/S sits well above the level suggested by a tailored fair multiple that factors in its margins, risk profile and scale. The gap is large enough that the model is effectively flagging how heavily recent losses and cash burn weigh on the valuation, rather than pointing to a precise target number. Despite new electrolyzer agreements with Arcadia eFuels and Allied Biofuels broadening the project pipeline, the share price still implies a rich tag on existing sales. Explore the numbers behind Plug Power's P/S valuation.
The Plug Power Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Plug Power's valuation question leaves off and spell out which future paths for growth, profitability and earnings would need to play out for the stock to be worth significantly more or less than it is today. All of this is hosted on the Community page.
Each narrative links its implied number to a specific view on how Plug Power's growth, margins and risk profile might change, giving you something concrete to revisit as fresh information comes through.
The Plug Power community is split between a turnaround story fuelled by policy support and execution progress, and a funding risk story focused on dilution and demand uncertainty.
Bull case: 47% undervalued
"Operational improvements such as gross margin enhancements from Project Quantum Leap, restructuring, facility consolidation, and favorable hydrogen supply agreements are already yielding sharply better margins..."
Discover why this Narrative puts Plug Power at 47% undervalued.
Bear case: 152% overvalued
"Persistent negative operating cash flow, high working capital requirements, and the need for repeated access to external debt facilities signal continued risk of shareholder dilution..."
Explore why this Narrative puts Plug Power at 152% overvalued.
One more Plug Power thread that could change your view
Price and narratives only tell part of the Plug Power story. Recent research checks also highlight specific pressure points in the business that deserve your attention before forming a judgment. Take a closer look at 3 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com