
What Technology One (TNE) Holders Had To Swallow, And Where To Look Now
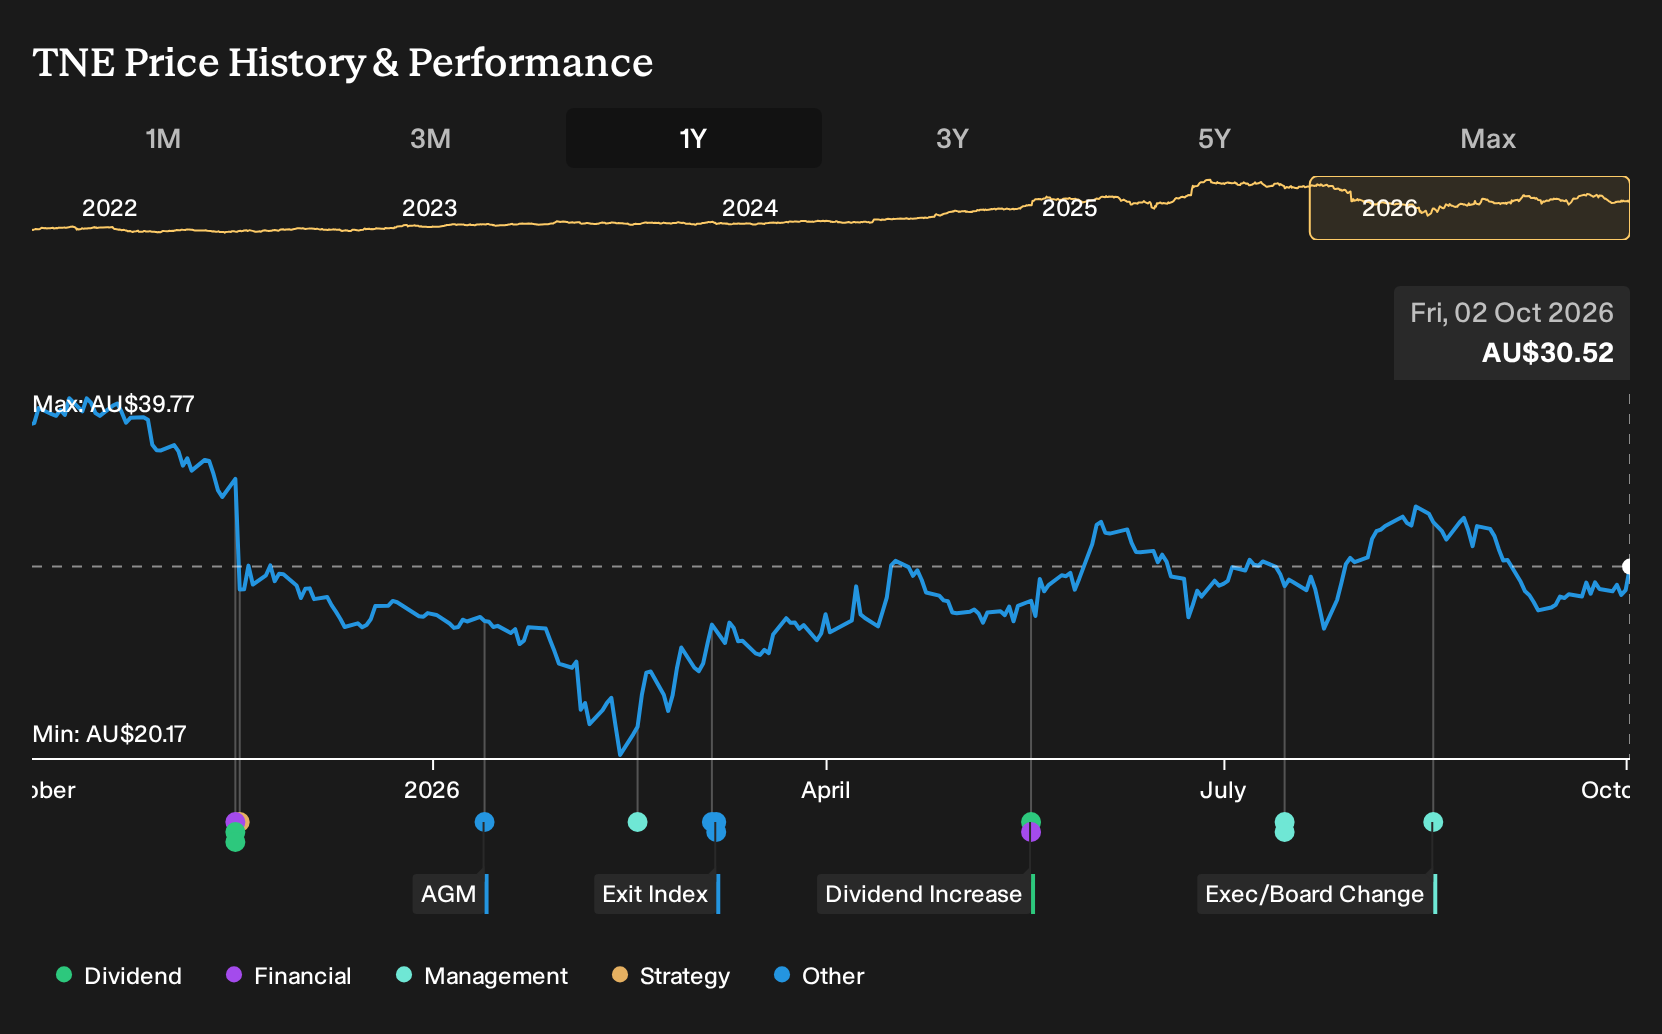
Technology One’s latest half year update looked upbeat on the surface, with record H1 profit, higher revenue, and an increased interim dividend, even as the share price slipped on tech sector weakness and profit taking. Holding Technology One over the past year would have meant a 21.2% loss, including dividends. If you had put money in a year ago on that kind of news and analyst optimism, what exactly did you think you were buying?
Technology One is not the only name tied to this theme. Zero in on 37 profitable AI stocks that aren't just burning cash and compare how each one is priced.
Two Stories Investors Had To Weigh On Technology One
The shares cost A$38.4 at the start of the period, and anyone buying Technology One then had to decide which future felt more reasonable.
The bullish story pointed to a Fair Value of A$45.7, a price that only made sense if rapid SaaS adoption, high net revenue retention, and expanding international markets supported revenue growth of 18.6% a year.
The bearish view anchored on a Fair Value of A$18, with concern that reliance on Australian and New Zealand public sector clients and heavier data regulation would restrain recurring revenue growth and long run margins.
What The Results Changed For Technology One
The clearest fact was Technology One lifting H1 revenue from A$285.7m in 2025 to A$318.4m in 2026 while net income rose from A$63.0m to A$66.8m. That supported the growth-heavy bullish case. Net margin slipped from 22.0% to 21.0%, which challenged the idea of effortless profitability expansion. Overall, the evidence cut both ways.
The lesson is simple. When a story leans on scaling software economics, keep checking whether margin trends match the revenue line, not just whether sales and guidance sound exciting.
What You Would Be Paying For In Technology One Today
Today Technology One trades at A$30.52. The selected Narrative places its Fair Value above that level, tying the case to SaaS adoption, customer stickiness, and execution in public sector and education software.
For the recent fall to look like an opportunity rather than a warning, a buyer must believe SaaS migration and international expansion sustain stronger recurring revenue and margin progress than sceptics expect.
"Analyst consensus highlights rapid ARR and margin expansion from SaaS+ adoption, yet this view may still understate the upside, as Technology One's accelerating implementation speed and deep vertical expertise are expanding net revenue retention to industry-leading levels and fueling even faster recurring revenue and profit growth than peers anticipate."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Go Straight To The Source
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 37% below our estimate - converts additional third party mandates and affiliates into higher fee revenue streams.
- Company 2 - 24% below our estimate - serves increasing prescription volumes while opening new outlets to deepen pharmacy networks.
- Company 3 - 22% below our estimate - integrates acquired gold projects and upgrade programs to enhance mine operating flexibility.
Those are three of them. See every one of the 5 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com