
Alaska Air Group (ALK) Stock Looks Reasonable Against Its Sales Base
Alaska Air Group has had a choppy ride in recent years, and the share price around US$39.49 keeps forcing the same question: Are investors paying a sensible price for the airline's sales, or has the stock drifted away from what its revenue base can reasonably support?
- Over the past 5 years the stock has fallen about 34.4%. This puts the focus squarely on whether the current valuation is still anchored to its underlying sales rather than past share price levels.
- Management's plans to expand services out of Seattle, add more premium seating, grow cargo and revamp the loyalty program may support different expectations for future ticket and ancillary revenue. This matters a lot if you are valuing Alaska Air Group mainly on its top line.
- The analysts covering Alaska Air Group have run their own numbers. See what analysts think Alaska Air Group's shares could be worth.
The issue now is whether the current share price can be justified by Alaska Air Group's sales when judged against the Fair Ratio benchmark.
If you are weighing whether Alaska Air Group's US$39.49 share price lines up with its sales, a focused screen of 28 high quality undervalued stocks.
Is Alaska Air Group a Bargain on Sales?
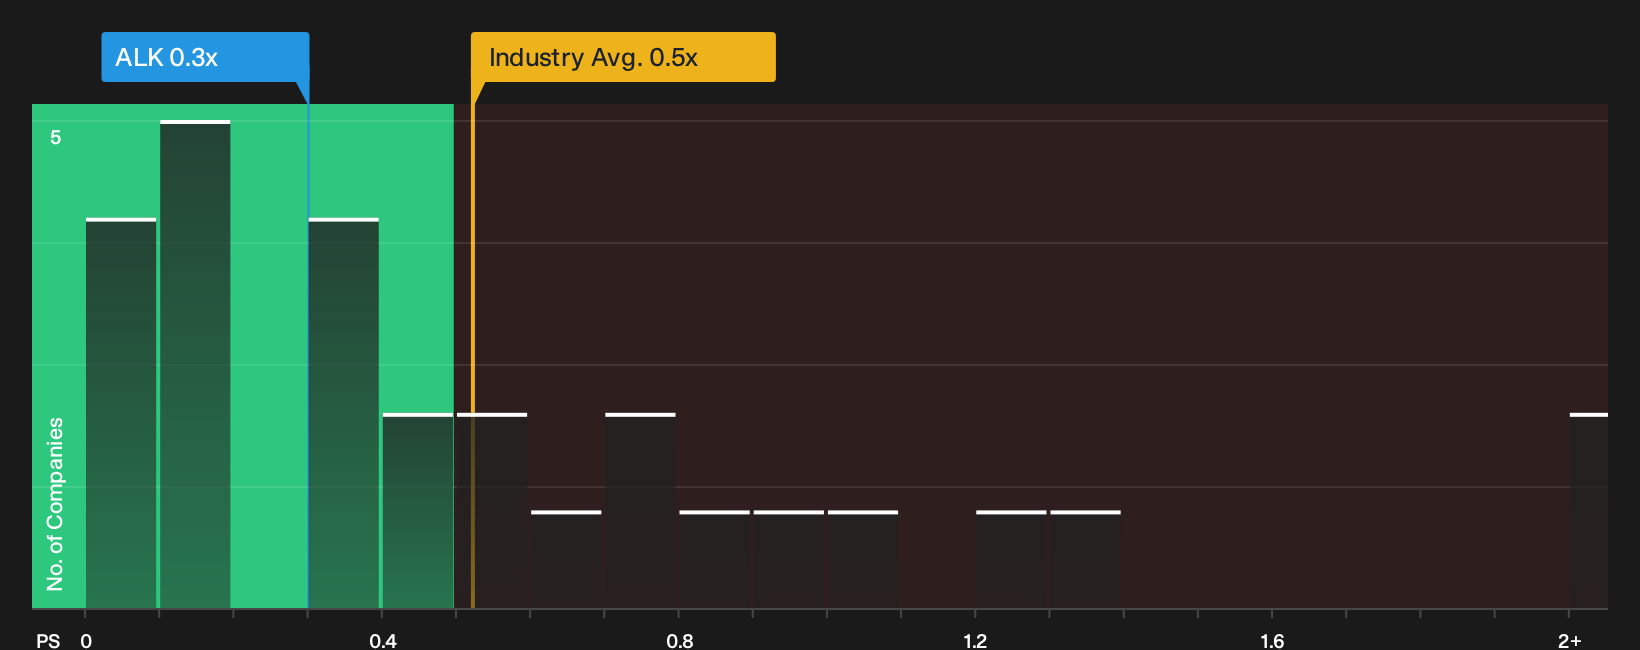
The P/S ratio suits Alaska Air Group because earnings can swing around, while revenue tends to be a steadier anchor for comparison. On this yardstick, the stock trades on a P/S of about 0.3x, which is well below both the airline industry average of roughly 0.5x and the peer group near 0.7x. The Fair Ratio model, which lines up the P/S you might expect given Alaska Air Group's growth profile, margins, size and risk, points to the current multiple sitting below that tailored benchmark, so the shares screen as undervalued on sales.
Because management is planning a sizeable build out of Seattle and Paine Field capacity through 2027, investors seem to be pricing those revenue ambitions cautiously even at this discounted P/S level. The gap between the trading multiple and both sector and peer norms suggests the market is still assigning a relatively low value to each dollar of Alaska Air Group's revenue compared to other airlines. Explore the numbers behind Alaska Air Group's P/S valuation.
The Alaska Air Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Alaska Air Group's P/S puzzle leaves off by spelling out which combinations of future growth, profitability and earnings would need to play out for the stock to be priced meaningfully higher or lower than it is today on the market. Each narrative ties a specific fair value estimate to a clear set of potential catalysts and risks so you can later see which version of Alaska Air Group's story is actually unfolding.
Community views on Alaska Air Group are split between investors who see fuel and cargo as a chance for a re rate and others who think fuel risk already keeps the stock fully valued.
Bull case: 53% undervalued
"The nearly doubled 737 freighter fleet, with additional aircraft based in Alaska and Hawaii, creates room for Alaska Air Group to build a higher margin cargo and small community freight business..."
Discover why this Narrative puts Alaska Air Group at 53% undervalued.
Bear case: 7% overvalued
"Although Alaska Air Group is increasing revenue from premium cabins, loyalty and cargo, recent adjusted net losses of $192 million in Q1 2026 and $102 million in Q2 2026 highlight that a sharp spike in jet fuel costs can outweigh this diversification..."
Explore why this Narrative puts Alaska Air Group at 7% overvalued.
Before acting on Alaska Air Group's valuation, there is one more angle to consider
Price tags rarely tell the whole story for Alaska Air Group, and Simply Wall St's broader checks have flagged specific business risks that deserve a closer look before you place too much weight on the multiples alone. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com