
Theon International (ENXTAM:THEON) Could Be 32% Undervalued Following €50 Million Contract Wins
Theon International (ENXTAM:THEON) has announced contract awards worth about €50 million from European and Middle Eastern customers, including a NATO member order for NYX night vision and ORION fused goggles.
Despite the fresh €50 million in contracts, Theon International’s share price has eased in recent weeks, with a 7‑day share price return of 6.78% and a 30‑day share price return of 12.12%. However, the year‑to‑date share price return of 8.50% contrasts with a 1‑year total shareholder return that declined 11.67%, suggesting short term enthusiasm has not yet fully repaired longer term investor losses.
Scan other defence and security hardware stocks showing contract momentum and expanding order books with the curated list of solid balance sheet and fundamentals (207 results).
Theon International now trades well below both its analyst target and one intrinsic value estimate, even after the latest contract news. Is that discount still justified, or has the share price reset too far?
Price-to-Earnings of 18.5x: Is it justified?
Theon International trades on a P/E of 18.5x, a level that analysts frame as implying the shares are reasonably valued against peers but not outright cheap relative to its own fair ratio.
The P/E ratio compares the current share price to earnings per share, so it effectively shows how much investors are paying today for each euro of Theon International’s profits. For a defence hardware specialist with positive earnings, this is a common yardstick because it links the valuation directly to the bottom line rather than to revenue or assets.
Analysts describe Theon International as good value versus the broader European Aerospace & Defense industry, where the average P/E is 32.4x. That is a strong discount in sector terms and indicates the market is putting a lower price on each euro of earnings than it does for the wider peer group. At the same time, the current 18.5x multiple is described as expensive both versus a peer subset on 15.4x and compared to an estimated fair P/E of 17x.
Explore the SWS fair ratio for Theon International.
Result: Price-to-Earnings of 18.5x (ABOUT RIGHT)
Still, Theon International relies heavily on defence budgets and contract timing, so any slower ordering cycle or delayed awards could quickly challenge today’s valuation narrative.
Find out about the key risks to this Theon International narrative.
Another View on Theon International’s Value
Theon International looks cheaper on earnings, yet the SWS DCF model paints a different picture. At a share price of €28.86 versus a DCF value of €38.13, the stock screens as undervalued on future cash flows. If that cash generation materialises, is the current discount too wide?
Look into how the SWS DCF model arrives at its fair value.
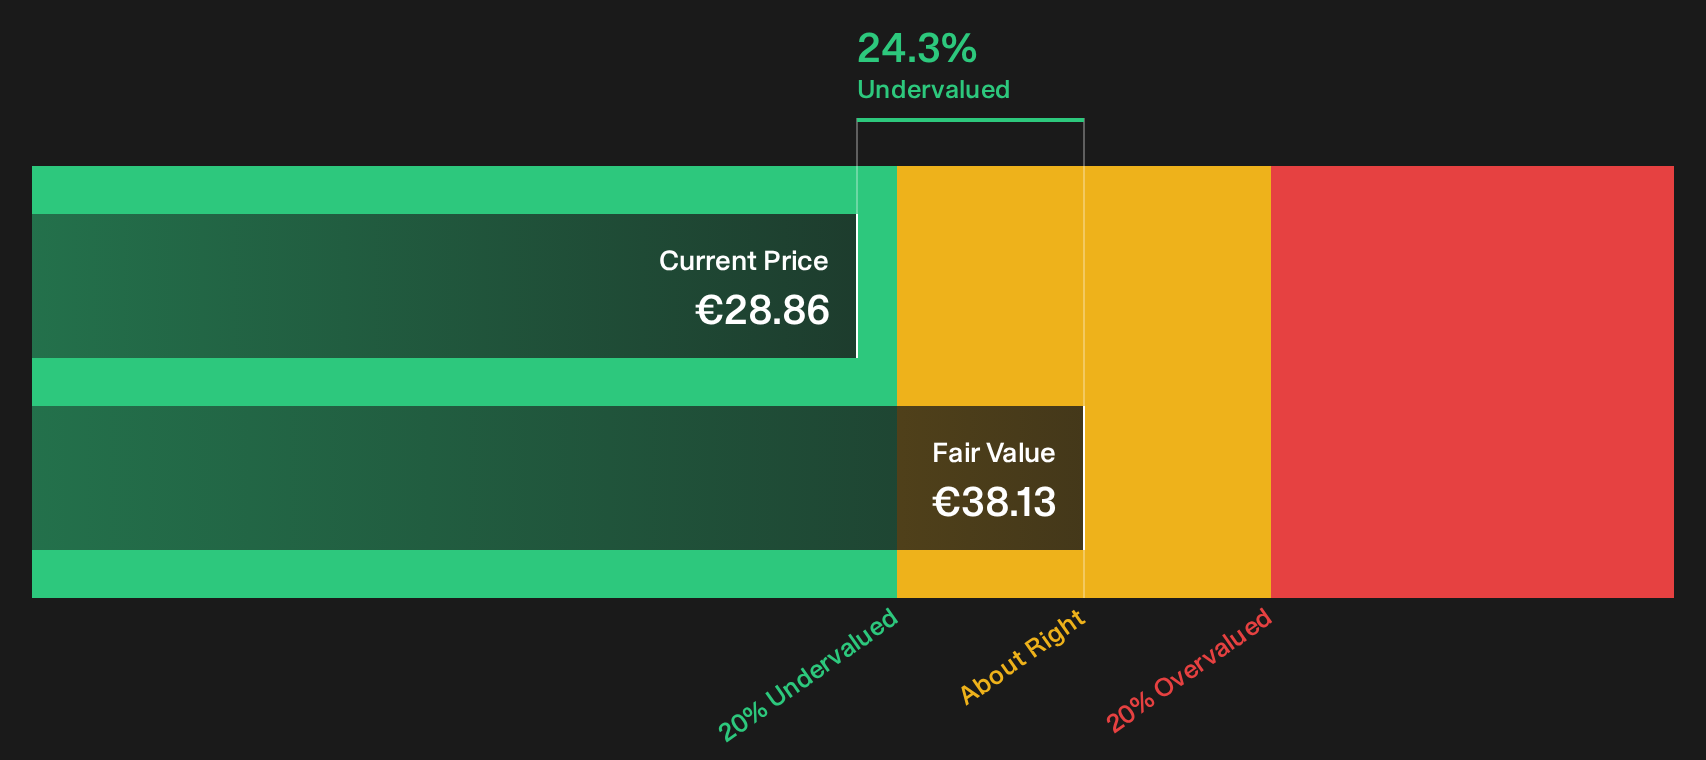
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Theon International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Theon International’s value and contract momentum can feel confusing, so move quickly and review the full risk and reward picture for yourself. The clearest way to pressure test your own view is to weigh both sides of the story through the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Theon International?
If you stop with Theon International, you risk missing other opportunities that fit your style. Use the screeners to widen your field of strong candidates.
- Target stronger balance sheets and steadier fundamentals with the curated list of solid balance sheet and fundamentals (207 results) that filters for financial resilience.
- Hunt for companies where quality and price line up more attractively by scanning the 191 high quality undervalued stocks tailored to value-focused investors.
- Build a portfolio with income at its core by reviewing the 169 dividend fortresses that spotlights higher yielding dividend payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com