
Missed FedEx's 50% Run? The Case That Held Was Not The Easy One
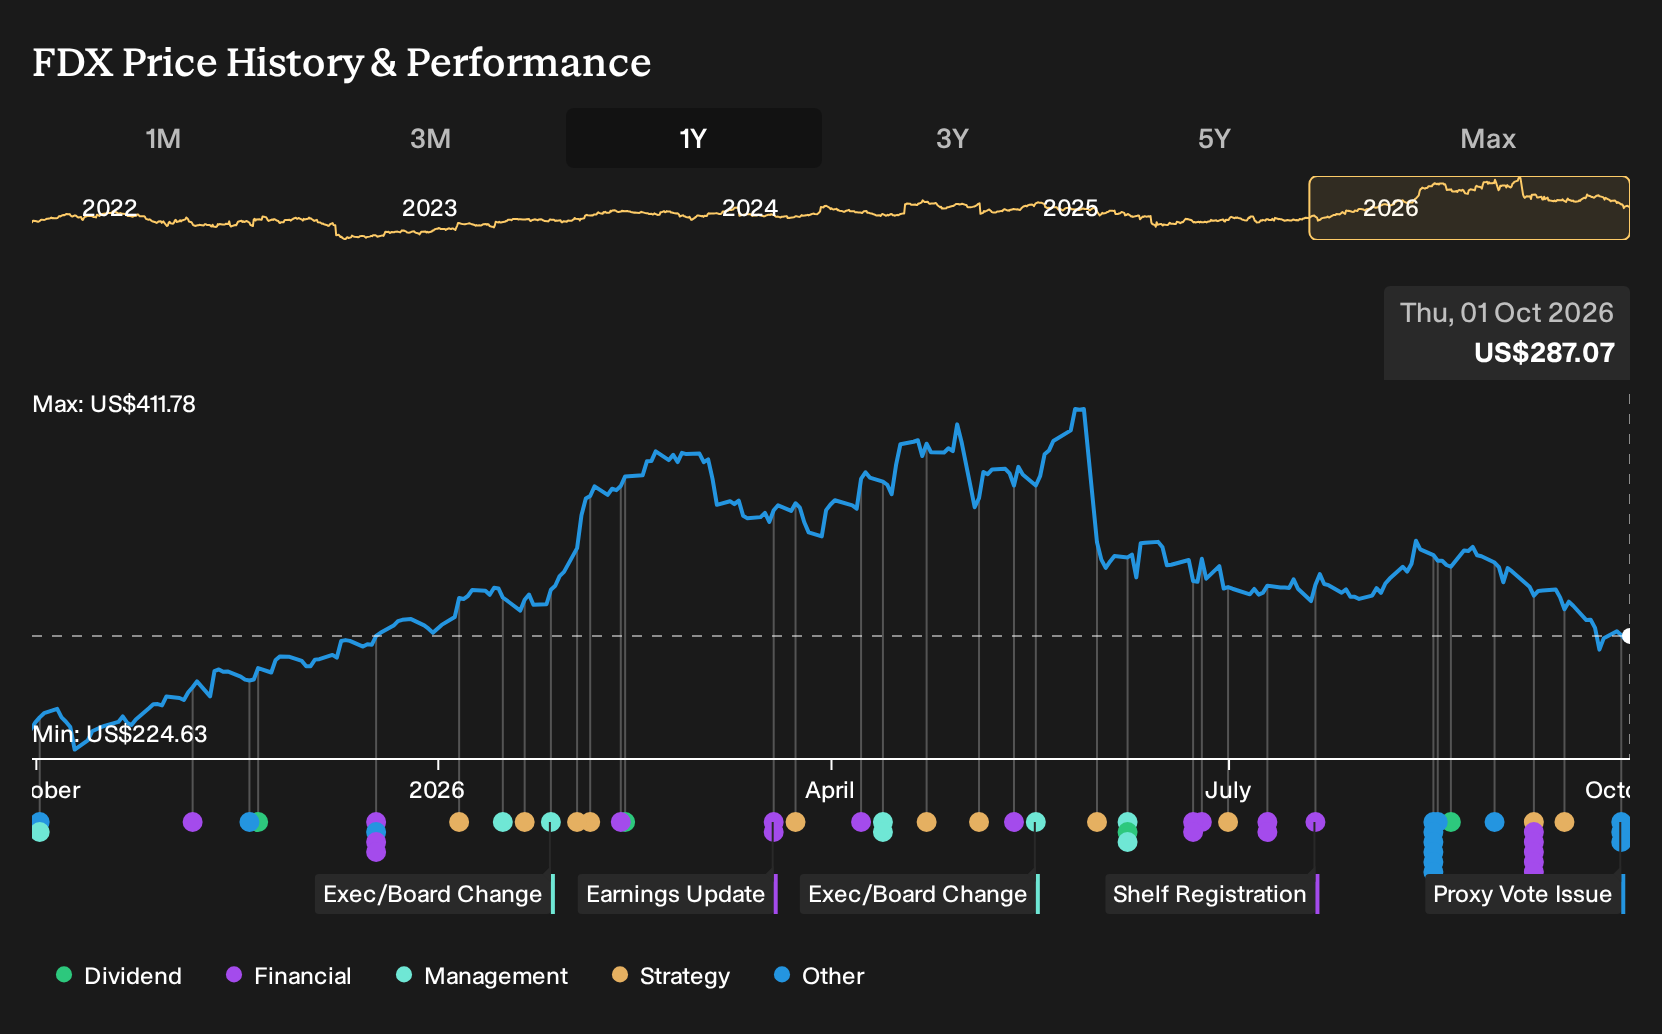
FedEx has spent the year reshaping itself, from spinning off Freight to locking in a rich new pilot contract that lifts labor certainty but also raises long term costs. Investors who held FedEx over the past year are up 49.6%, including dividends. If you were weighing a purchase back on 2025-10-01, what beliefs would you have needed to hold about DRIVE, Network 2.0, and mounting competition from Amazon to support that kind of outcome?
If the move has made FedEx harder to judge, start where the gap is still open and scan 28 high quality undervalued stocks.
The Two FedEx Stories Investors Were Really Arguing About
The shares cost US$240 at the start of the period, and anyone circling FedEx then had to decide which story felt more believable.
On the optimistic side, the DRIVE and Network 2.0 camp saw a Fair Value of US$263. This was a rough guide to what the stock might be worth if revenue grew 2.8% and profit margins reached 5.4% over three years.
The sceptical view pointed to a Fair Value of US$200. This was based on worries that structural parcel volume declines and rising labor and environmental costs would steadily pressure FedEx’s future profitability.
What The FedEx Evidence Actually Tested
The clearest test for FedEx was the Q4 2026 report. Revenue was US$25.0b versus US$22.2b a year earlier, which broadly backed the DRIVE and Network 2.0 optimism on volume and pricing. Net income dipped to US$1,595m from US$1,646m and net margin moved from 7.4% to 6.4%, so the cleaner profitability story stayed unproven. Overall, the evidence was mixed.
The lesson is simple. When a cost program is central to the thesis, treat net margin as the scoreboard and compare it quarter by quarter against the original efficiency claims, not just the top line.
What FedEx's Recent Run Already Prices In
FedEx now trades at US$287, with this Narrative’s Fair Value placed below that level. This implies the authors see the recent 49.6% move over the past year as more than fully reflecting their base case.
The Narrative leans on cost cuts and parcel growth but highlights strain from volume trends, regulation, labor, and e-commerce rivals. Anyone paying today’s price is assuming FedEx can defend pricing power. The open question is how that assumption holds up against those structural cost and competition pressures.
"Key Takeaways: Structural declines in parcel volumes, rising labor and environmental costs, and intensifying price competition threaten long-term revenue growth and margin sustainability. Underperformance in international markets and challenges from e-commerce giants could significantly limit global expansion and erode pricing power."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 39% below our estimate - uses large project backlog to expand capacity for complex e-infrastructure builds.
- Company 2 - 37% below our estimate - turns subsea prospect lists into integrated project awards and extended service arrangements.
- Company 3 - 24% below our estimate - sells GPU-based platforms tied to an entrenched AI software workflow ecosystem.
Those are three of them. See every one of the 25 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com