
Is Loews (L) Undervalued On Its Recent Pullback Or Already Fairly Priced?
Loews (L) has drawn attention after recent price moves left the stock roughly 3% lower over the past month and close to 10% weaker across the past 3 months.
Set against that recent softness, Loews has moved only slightly higher year to date on a share price basis. Its 1-year total shareholder return of 3.56% and 5-year total shareholder return of 87.66% point to momentum that has been built over a longer horizon despite the latest pullback.
Scan how Loews compares with other companies that have come through recent pullbacks with stronger balance sheets and cash flows by reviewing the hand picked 31 resilient stocks with low risk scores.
Loews now trades at a modest intrinsic discount after that pullback, which raises a simple tension: Is the market rightly cautious about the mix of businesses here, or is it underpaying for that diversified earnings base?
Preferred P/E of 12.7x for Loews: Is it justified?
Loews screens as expensive on earnings at a P/E of 12.7x, especially when set against peers and the wider US insurance group, even though the SWS DCF model places fair value slightly above the current $105.05 share price.
The P/E ratio compares what investors are paying today for each dollar of profit. For an insurer led group like Loews, this metric matters because earnings quality and consistency are central to how investors judge the underlying underwriting, pipeline and hotel cash generation.
Profitability trends at Loews offer mixed signals against that richer multiple. Net profit margins are currently 9%, above last year's 7.5%, and earnings have grown 4.2% per year over the past 5 years with 25.1% growth most recently, and the business is flagged as having high quality earnings, yet the 8.9% return on equity is classified as low and short of the 20% threshold often used as a marker for strong capital efficiency.
Compared with similar insurers, that 12.7x P/E is described as expensive versus a 9.8x peer average and also rich relative to the broader US insurance industry at 10.6x. This points to investors paying a clear premium against sector norms despite the modest 4% intrinsic discount implied by the SWS DCF work.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 12.7x (OVERVALUED)
Still, concentrated exposure to commercial property and casualty insurance, as well as the cyclical hotel and pipeline operations, could quickly challenge that premium P/E if conditions turn.
Find out about the key risks to this Loews narrative.
Another View on Loews Using Cash Flows
The earnings multiple paints Loews as pricey, yet the SWS DCF model suggests a different story. On that cash flow view, an estimated fair value of $109.41 versus a $105.05 price points to roughly a 4% discount. So is the current weakness a small opening, or just noise inside a tight valuation band?
Look into how the SWS DCF model arrives at its fair value.
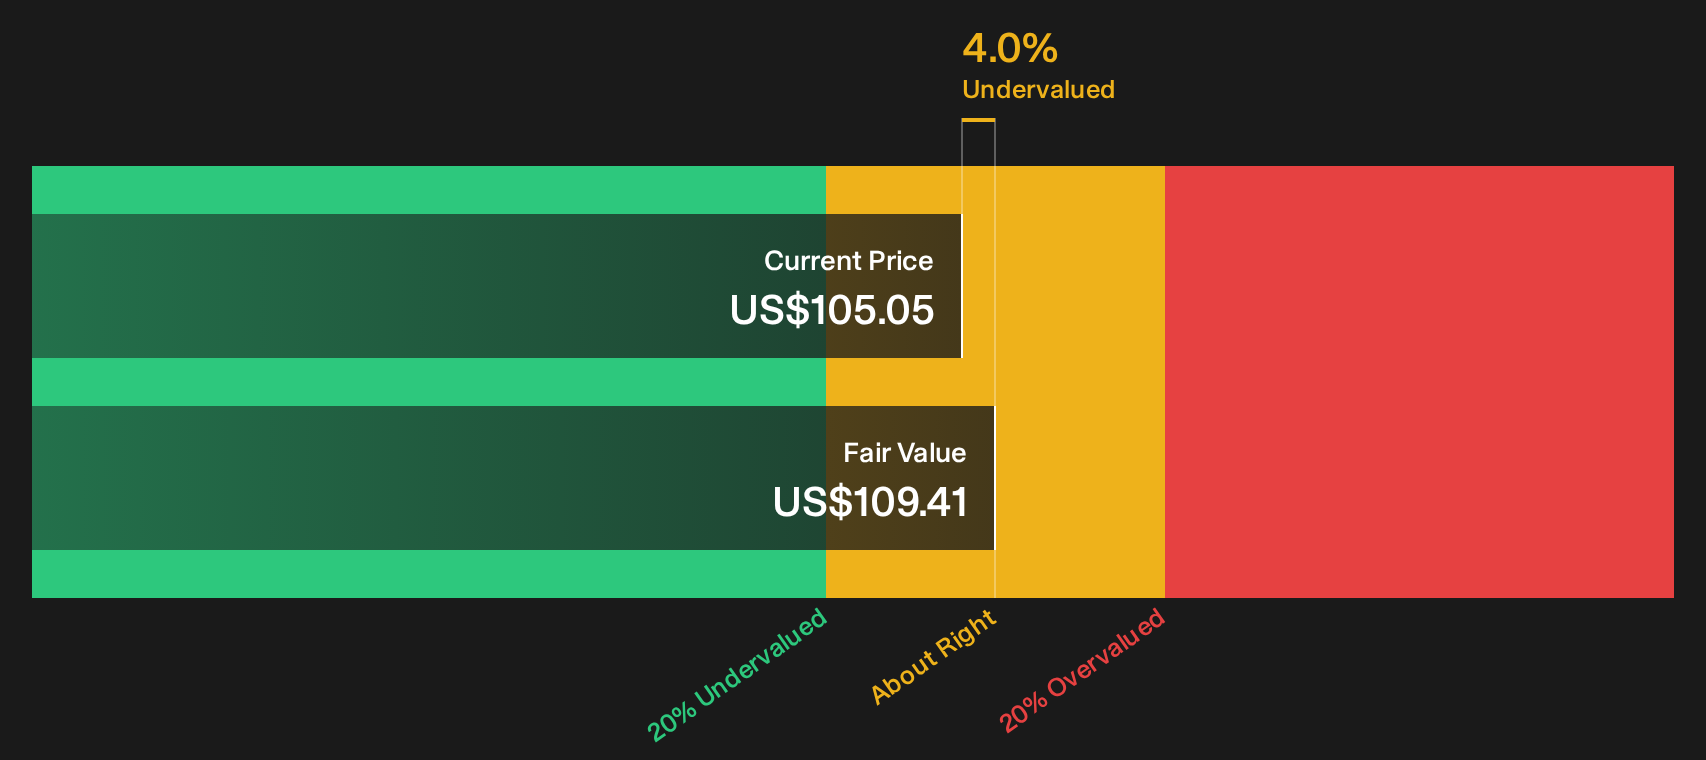
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Loews for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed tone on Loews so far leaves you undecided, consider acting while sentiment is still split and stress test the upside case in the 2 key rewards
Looking for more investment ideas beyond Loews?
If Loews has your attention, do not stop there. Broader opportunities often sit just outside your current watchlist, and skipping them can quietly limit your results.
- Target specific opportunities with tighter risk control by checking companies highlighted in the 31 resilient stocks with low risk scores.
- Look for potential mispricing by reviewing the 28 high quality undervalued stocks.
- Explore options for a steadier income stream by focusing on the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com