
Luckin Coffee (OTCPK:LKNC.Y) Stock Looks Undervalued Following Its 137% 5 Year Run
Luckin Coffee has delivered a very strong 136.7% share price gain over the past 5 years, yet its recent pullback and fresh headlines about overseas expansion leave an obvious question. Are investors paying a fair price today given what the business is actually earning?
- That 136.7% 5 year return puts meaningful pressure on the current valuation because so much of the long term upside case is already reflected in the share chart.
- The push to 100 stores in Singapore, along with a broad local menu and community partnerships, can support expectations for higher earnings over time if the international rollout scales efficiently.
- Your read on Luckin Coffee is one view; the desks covering it have another. See what analysts think Luckin Coffee's shares could be worth.
The issue now is whether the current share price around US$33.35 can be explained by Luckin Coffee's earnings when measured against its Fair Ratio benchmark.
If you are weighing whether Luckin Coffee's 5 year gain of 136.7% still leaves enough upside, it can help to compare it with other 28 high quality undervalued stocks
Is Luckin Coffee Still Cheap on Earnings?
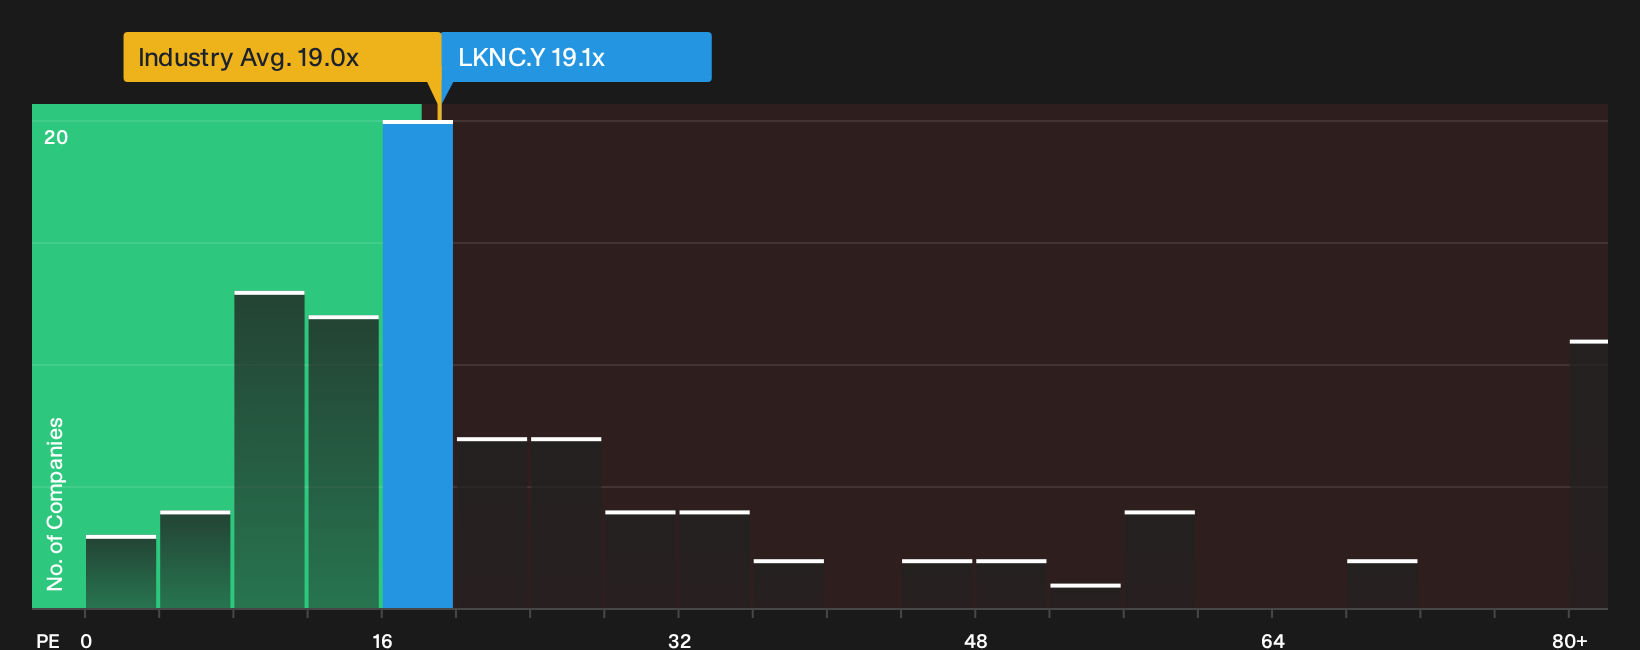
The P/E ratio is a useful lens for Luckin Coffee because the market is clearly anchoring its view on reported earnings rather than dividends. On this measure, the stock trades on about 19.1x earnings, which is very close to the hospitality sector average of 19.0x. Against that broad backdrop, Luckin Coffee does not screen as especially stretched or unusually cheap on headline earnings alone.
Compared with a peer group closer to 48.8x, the current multiple looks lower, and the Fair Ratio model suggests the P/E investors might expect given the business profile would be higher than where the shares trade now. Because the recent push to 100 Singapore stores adds a visible growth story that could justify richer earnings multiples in many investors’ minds, the current P/E sitting below that tailored Fair Ratio points to the stock pricing in some caution rather than exuberance. Explore the numbers behind Luckin Coffee's P/E valuation.
The Luckin Coffee Narrative: What Would Justify Today's Price?
Narratives on Luckin Coffee act as the missing link between the current P/E discussion and the expectations built into the share price, because they lay out in plain terms what path for future growth, profitability and earnings would need to play out for the stock to be worth materially more or less than it is today. Instead of giving a single output from a ratio or model, these scenarios unpack the future that number relies on so you can watch over time whether those conditions actually occur. They are available on Simply Wall St's Community page.
One of the top community narratives on Luckin Coffee: 31% undervalued
"Expanding store presence and digital-first engagement support continued revenue growth and strong customer loyalty through innovation and personalized service..."
Discover why this Narrative puts Luckin Coffee at 31% undervalued.
Luckin Coffee’s price is only half the story investors need
Ratios and scenarios tell you what the market is paying for Luckin Coffee today, but the real test is who is steering the business and how their rewards line up with your interests. See who runs Luckin Coffee and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com