
Legal & General Group Investors Were Backing The Harder Case
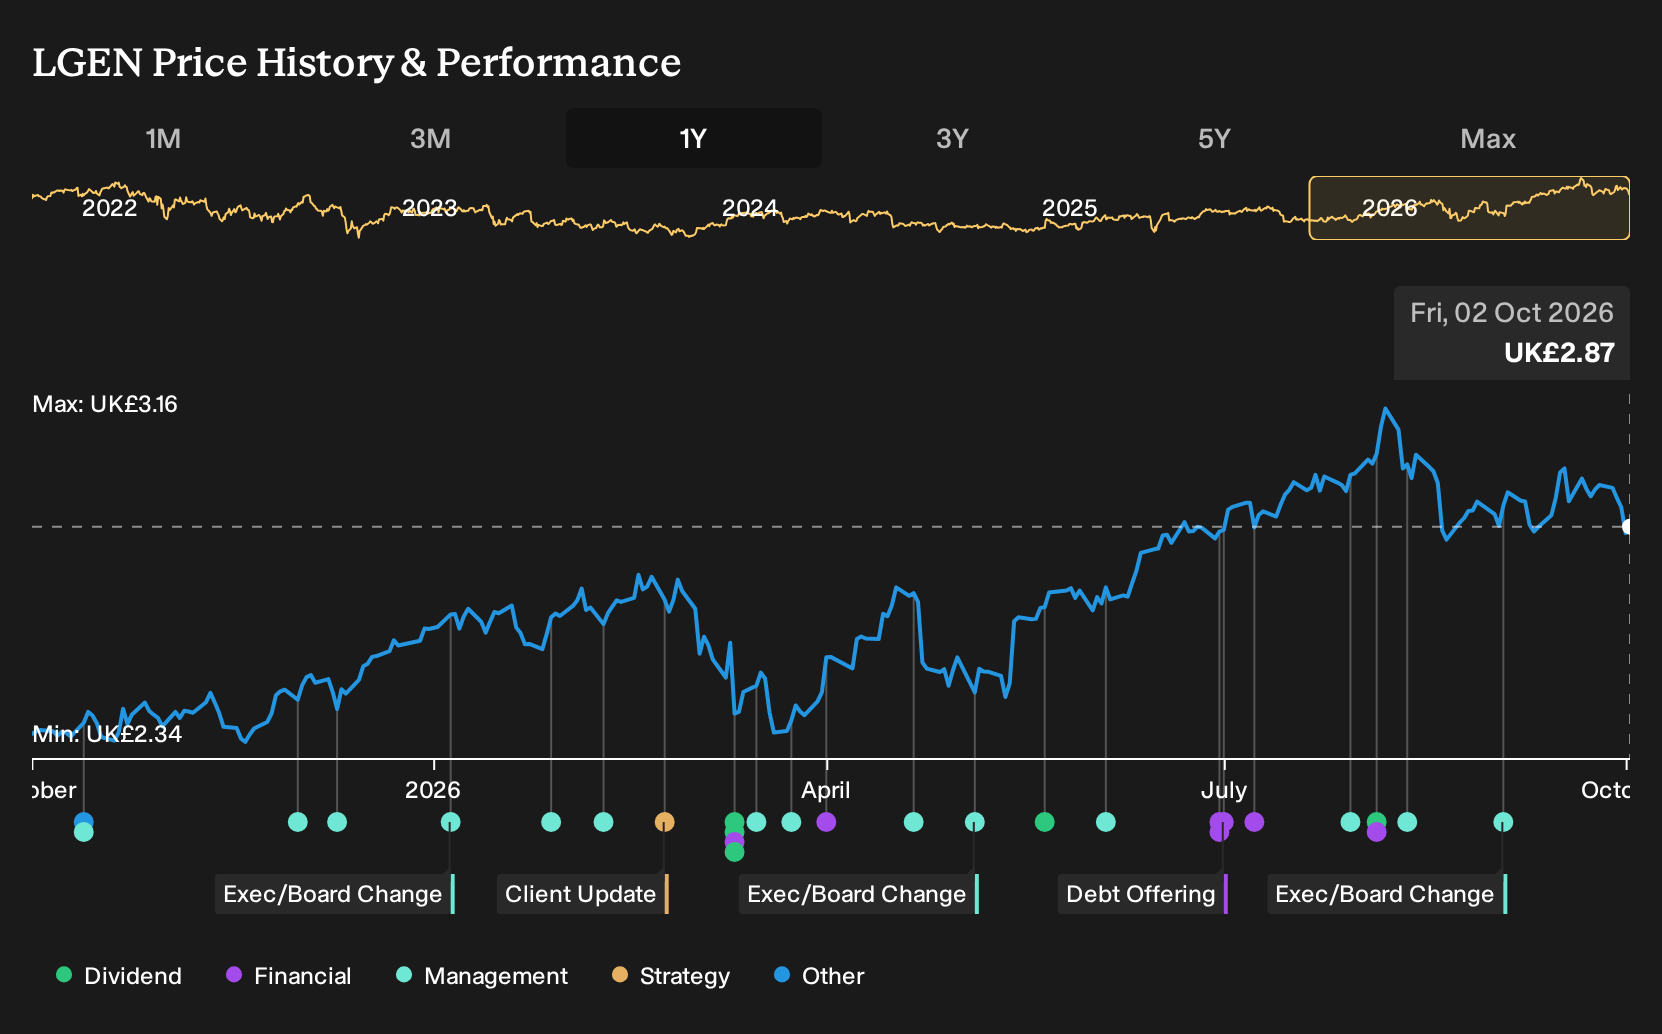
If you only glanced at Legal & General Group’s headlines this year, you saw a business cutting around 1,000 roles and selling non core units while talking up a simpler model and more than £5b earmarked for shareholder payouts by 2027. Holding Legal & General Group over the past year would have returned 31.5%, including dividends. If you had been weighing those October 2025 bull and bear narratives, what exactly did that contrast ask you to judge?
The move put Legal & General Group in the middle of this trade. Scan 39 power grid technology and infrastructure stocks for other companies exposed to it.
The Argument Investors Faced On Legal & General Group
The shares cost £2.37 at the start of the period, and Legal & General Group sat between two very different but credible stories about its future.
On the upbeat side, the bull Narrative suggested a Fair Value of £2.62. This was a rough guide to what that view thought the stock could be worth, built on ageing populations, digital transformation and an assumed 5.0% annual revenue decline paired with a 13.3% profit margin and a future P/E of 12.7x.
The bear Narrative pointed to a Fair Value of £2.15. This was rooted in worries about slower demographic support, fintech rivalry, tighter regulation and an assumed 4.3% revenue decline with profit margins rising to 16.4% and a future P/E of 7.9x.
What The Results Changed For Legal & General Group
The clearest test came from Legal & General Group’s H1 2026 report. Total revenue moved from £5,429m in H1 2025 to £6,260m in H1 2026, while net income excluding extra items rose from £259m to £447m and net margin improved from 4.8% to 7.1%. Job cuts of around 1,000 roles and non core disposals pointed to cost focus. Taken together, the evidence cut both ways.
The key assumption investors needed to watch was profitability, not just growth. For another insurer or asset manager, track the direction of reported net income and the net margin percentage over time and test whether management’s simplification or efficiency story actually shows up in those two figures.
What Legal & General Group’s Price Is Asking You To Believe Now
Legal & General Group now trades at £2.87, after a 31.5% gain over the past year. The selected cautious Narrative places its Fair Value below that level, framing the current quote as rich if its concerns on competition, regulation and long term demand prove accurate.
The Narrative leans on the risk that pension risk transfer and retirement flows slow while rivals and new technology compress fees. Anyone paying today’s price is effectively assuming those pressures will stay manageable, so the key question is how that assumption holds up against the risks the selected Narrative highlights.
"Slowing demographic growth, market overexposure, and heightened regulation threaten Legal & General's long-term earnings, margins, and ability to sustain dividends. Rising competition and disruptive technologies risk margin contraction and revenue stagnation as innovative challengers erode the company's pricing power and market share."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Where Legal & General’s Theme Extends
Legal & General leans hard on retirement and insurance demand. You can also look sideways at who is reshaping the same toolkit.
Across global insurance and asset management, one large group is pushing hard on AI in underwriting, marketing and claims handling.
It is also building a fuller health and protection pillar, aiming for steadier contract based cash flows alongside traditional cover.
Its asset management arm is chasing new inflows and higher fee income, then feeding that into AI and productivity projects.
If Legal & General’s story interests you, this neighbour’s push on technology and health cover raises a different kind of insurance play to examine.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 39% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com