
SentinelOne (S) Expands Wayfinder Across Clouds, Is The Stock Fully Priced?
SentinelOne (S) has expanded its Wayfinder Threat Hunting service to the major cloud providers, extending coverage across AWS, Azure, and Google Cloud in a single expert-led security workflow for enterprise environments.
Recent trading has been strong, with SentinelOne’s share price showing a 3.83% 1-day return and a 19.58% 30-day share price return. This builds on a 68.51% year-to-date share price gain as investors react to product updates like the Wayfinder expansion and reassess long-term prospects. These developments are reflected in a 38.83% 1-year total shareholder return and 51.54% total shareholder return over three years, despite a 56.54% total shareholder return decline over five years.
Spot opportunities alongside SentinelOne by scanning a hand-picked set of cybersecurity and AI-driven peers in our 37 profitable AI stocks that aren't just burning cash that pair real cash generation with exposure to similar themes.After a sharp run on the back of Wayfinder’s cloud roll out, SentinelOne now forces a timing call. Is it worth paying up today, or does patience on entry price matter more here?
Most Popular Narrative: 2% Overvalued
SentinelOne closed at $24.67, slightly above the most followed fair value estimate of $24.25, so the current quote leans ahead of that narrative while still anchored to the same long term story.
Expansion beyond endpoint security into high-demand adjacent markets such as cloud security, identity, and data protection, including the Prompt Security acquisition for GenAI risk, unlocks significant cross-sell opportunities and is expected to elevate average contract value and diversify revenue streams, laying the groundwork for outsized multi-year revenue growth. The escalating pace of digital and AI transformation is making robust and integrated cybersecurity an enterprise priority across industries, positioning SentinelOne as an essential partner and benefitting long-term demand visibility, multi-year contracts, and earnings quality.
See why 96 investors see SentinelOne as 2% overvalued.
Result: Fair Value of $24.25 (OVERVALUED)
Still, SentinelOne’s reliance on large partners, along with the potential impact of tighter data regulations, could pressure both margins and the long term growth story.
Find out about the key risks to this SentinelOne narrative.
Another View on SentinelOne’s Value
The analyst narrative presents SentinelOne as close to fairly priced, yet the SWS DCF model presents a different picture. On that future cash flow view, $24.67 is about 10% below an estimated value of $27.47, which frames the recent share price strength as less stretched than it first appears. For you as an investor, the real question is which set of assumptions feels more realistic for a still unprofitable cybersecurity platform.
Before leaning on that output too heavily, it is worth understanding how sensitive any model is to small shifts in discount rates or long run margins, especially for a business that reports a loss of $340.1 million today and is not forecast to reach profitability within three years. Look into how the SWS DCF model arrives at its fair value.
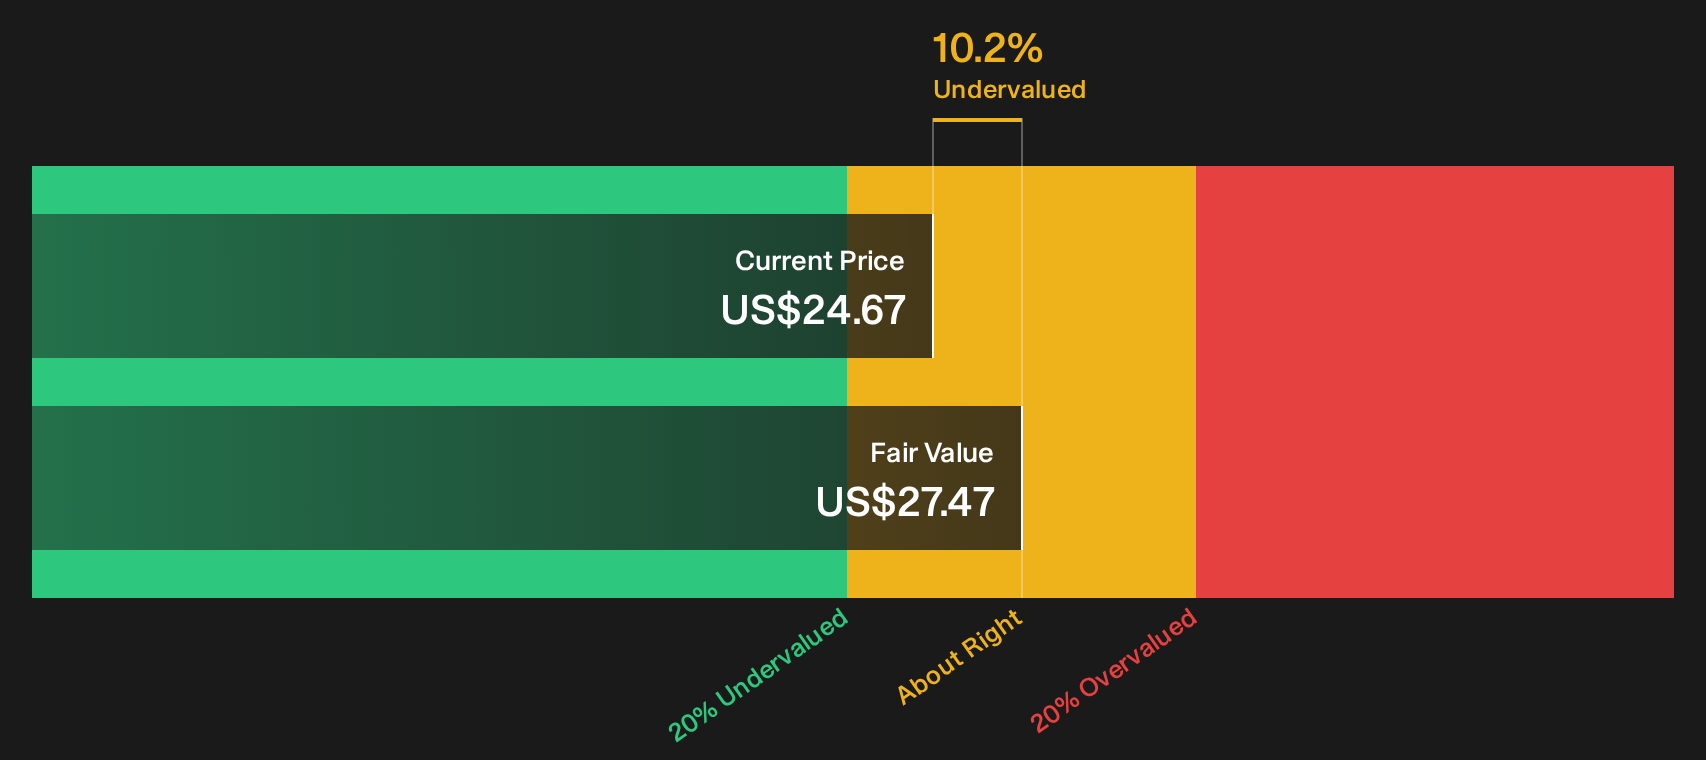
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SentinelOne for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split sentiment around SentinelOne leaves you undecided, move fast and dig into the underlying data so you can draw your own line in the sand. To see how both the upside and the downside stack up in one place, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond SentinelOne?
Do not stop your research at SentinelOne. The best opportunities often sit just outside the obvious choices, and a few targeted screens can surface them quickly.
- Target dependable returns by reviewing companies in the 7 dividend fortresses that focus on income strength backed by higher yields.
- Hunt for upside potential by scanning the 19 high quality undiscovered gems and spotting quality businesses that many investors are still overlooking.
- Dial down portfolio risk by reviewing a 31 resilient stocks with low risk scores to help balance growth ideas with sturdier, lower volatility holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com