
How New CFO Appointment Will Impact Levi Strauss Stock
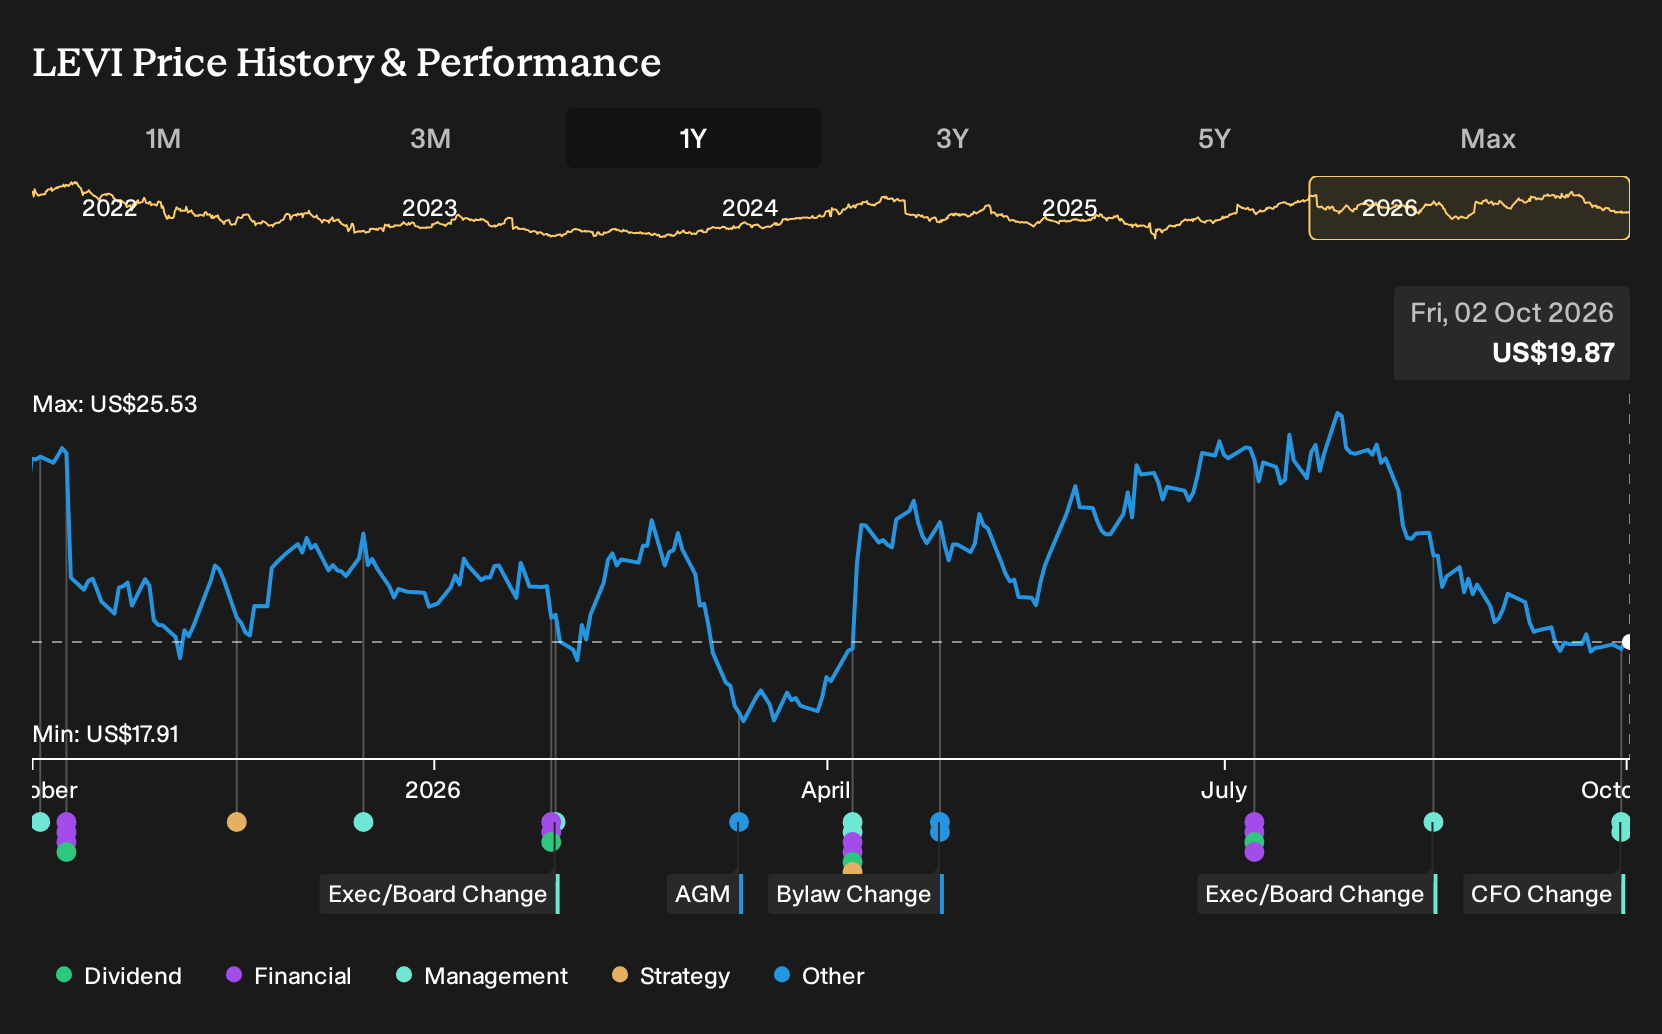
- Levi Strauss & Co. has appointed John Vandemore as Chief Financial Officer and Executive Vice President, effective November 1, 2026, following Harmit Singh’s planned retirement and transition to Special Advisor through November 30, 2026.
- Vandemore’s background running finance, supply chain, digital and IT at Skechers, Mattel and other consumer-focused groups gives Levi Strauss a leader with hands-on experience across cost control, data and global operations.
- This article now explores how Levi Strauss's investment narrative could be shaped by John Vandemore's broad finance and operations remit.
Scan how Levi Strauss’s CFO transition compares with peers by lining up management-heavy stories against our curated list of list of solid balance sheet and fundamentals (25 results).
Levi Strauss Investment Narrative Recap
To own Levi Strauss, you need to believe the brand can keep turning its global reach, DTC focus and category expansion into steady earnings, even while denim tastes and tariffs keep shifting. The key near term swing factor is execution on DTC and omnichannel, where higher SG&A and heavy investment can either support margins or dilute them.
The CFO change to John Vandemore looks operationally important but not a thesis breaker by itself. The biggest risk still sits with concentration in the Levi’s label, tariff exposure and a soft patch in Asia, especially China, where slower progress could cap the benefit from Europe and Latin America.
The most relevant announcement is Vandemore’s appointment as Chief Financial Officer and Executive Vice President from November 1, 2026, with Harmit Singh moving to Special Advisor through November 30. This keeps continuity in the finance seat during a handover while putting an operator with broad consumer experience into a role that touches supply chain, digital and IT.
For catalysts, you are watching whether this finance leadership can keep funding DTC, omnichannel and lifestyle category growth without letting SG&A drift higher as a share of sales. Execution on tariff mitigation, brand only portfolio and Asia reset will sit squarely in Vandemore’s remit, so future commentary from Levi Strauss around costs and capital allocation will matter more after this transition.
Levi Strauss’ current analyst narrative points to revenue of $7.7b and earnings of $839.5 million by 2029, based on 5.1% yearly revenue growth and an earnings increase of about $285 million from $554.1 million today.
Uncover why Levi Strauss' fair value indicates a 42% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses less on tariffs and more on the risk that Levi Strauss’s long ERP and logistics overhaul drags on profit. The most cautious analysts were already penciling in about 4.8% annual sales growth to roughly US$7.6b and earnings of US$843.4 million by 2029. Those projections came before the Vandemore news and could shift meaningfully.
Explore 3 other Levi Strauss fair value estimates, including one that suggests as much as 39% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Levi Strauss research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Levi Strauss. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Levi Strauss' overall financial health at a glance.
Looking for more Levi Strauss investment ideas?
If the Levi Strauss story has sharpened your thinking, use that momentum to compare it with other potential opportunities that match your risk profile and income goals.
- For investors who want strong fundamentals and balance sheets that can absorb shocks, start with a focused list of solid balance sheet and fundamentals (25 results) that filters for financially resilient businesses.
- If value is your priority and you prefer companies where quality and price both matter, scan the 28 high quality undervalued stocks to see which stocks currently screen well on fundamentals and valuation.
- Income focused investors who care about cash returns can sift through the 7 dividend fortresses to spot higher yielding payers with the potential for more stable payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com