
Tootsie Roll Industries (TR) Draws Fresh Analyst Attention, Is The Stock Fully Priced?
Tootsie Roll Industries (TR) has drawn fresh attention after new analyst coverage put the confectioner alongside a broader group of packaged food peers. This has prompted investors to revisit how this long-running candy producer is currently valued.
Recent trading paints a mixed picture for Tootsie Roll Industries. The share price is around $37.84 after a year to date share price return of 10.07%. However, the 1 year total shareholder return declined 8.39%, while the 3 and 5 year total shareholder returns of 37.47% and 45.30% point to longer term momentum. This appears to have cooled in recent months, as the 30 and 90 day share price returns fell 6.13% and 7.21%.
Spot opportunities beyond Tootsie Roll Industries by scanning a curated 19 high quality undiscovered gems that features companies with strong fundamentals that still fly under most investors' radar.After a long run that now looks softer at the edges, Tootsie Roll Industries forces a simple choice: Is this recent pullback enough of an entry, or does patience still look safer before the valuation work begins?
Price-to-Earnings of 29.7x: Is it justified?
Tootsie Roll Industries trades on a P/E of 29.7x, which looks rich when set against peers and the last close at $37.84.
The P/E ratio compares the current share price with earnings per share and gives a quick sense of how much investors pay for each dollar of profit. For a mature confectionery producer with a long history, this kind of metric often reflects how much the market values consistency in cash generation and brand strength.
TR has grown earnings by 5% over the past year and by 9.6% per year over the last 5 years, with current net profit margins of 13% compared with 12.6% a year ago. That earnings profile, together with high quality earnings and a Return on Equity of 10% that is described as low, suggests the current P/E reflects a healthy level of confidence rather than a clear discount.
The valuation gap is wide. Tootsie Roll Industries trades on a P/E of 29.7x, compared with a peer average of 20.9x and a US Food industry average of 17.8x, which indicates the stock is priced at a premium rather than in line with sector norms.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 29.7x (OVERVALUED)
Still, Tootsie Roll Industries carries clear risks, including pressure on confectionery demand as well as any shift in retailer shelf space or private label competition.
Find out about the key risks to this Tootsie Roll Industries narrative.
Another View on Tootsie Roll Industries: Cash Flows Point the Same Way
A second lens does not soften the picture. Our DCF model estimates Tootsie Roll Industries' future cash flows point to a value of about $33.79 per share, while the stock trades at $37.84. That implies the shares look overvalued on both earnings and cash flow metrics. It raises a simple question for you: What would need to change in the story to close that gap?
Look into how the SWS DCF model arrives at its fair value.
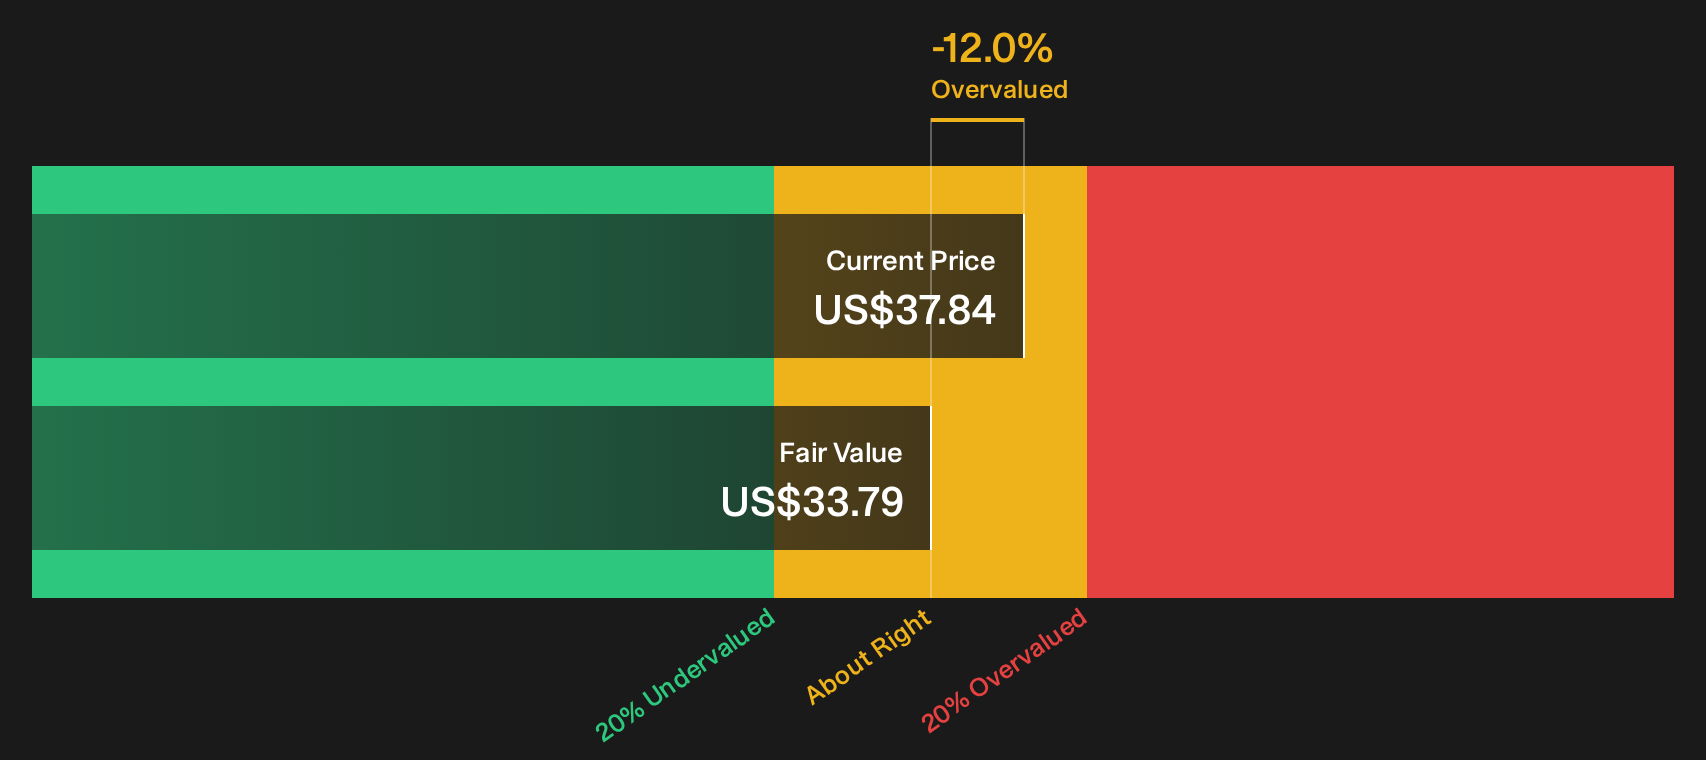
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tootsie Roll Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this read on Tootsie Roll Industries feels mixed, that is the point. Use the full data set, move quickly, and test the upside case in the 1 key reward.
Looking for more investment ideas beyond Tootsie Roll Industries?
If Tootsie Roll Industries feels fully priced to you, consider broadening your watchlist with ideas that align with your return goals and risk tolerance.
- Target potential mispricing by scanning a curated pool of companies that combine earnings strength with appealing entry points using the 28 high quality undervalued stocks.
- Anchor your portfolio with income ideas by reviewing a focused set of high yield opportunities through the 7 dividend fortresses.
- Protect your downside by filtering for businesses with resilient finances and steady fundamentals using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com