
OR Royalties (TSX:OR) Could Be 21% Below Fair Value As Project Catalysts Build
OR Royalties (TSX:OR) has put a spotlight on its portfolio with fresh operational news, including first gold at Cuiú Cuiú, imminent output from Amulsar and new royalty income from Bralorne.
Against this backdrop, OR Royalties' CA$49.1 share price comes after an 8.70% 90-day share price return but a decline of 3.48% over 30 days. The 1-year total shareholder return is down 10.15%, while the 3-year total shareholder return is a little over triple and the 5-year total shareholder return is slightly higher again. This points to strong long term compounding but softer recent momentum as investors weigh fresh project news against changes in perceived risk and future cash flow visibility.
Scan other royalty and precious metals plays showing similar project catalysts by reviewing the curated 36 elite gold producer stocks alongside OR Royalties' latest mine ramp ups and first royalty payments.
OR Royalties appears to be a solid royalty platform with growing assets feeding into it. After the recent share pullback, is that strength already fully reflected in the CA$49.1 price or not?
Most Popular Narrative: 21% Undervalued
On the most followed narrative, OR Royalties screens as undervalued, with a fair value of CA$62.23 against the CA$49.10 last close. This puts the recent pullback in a different light for anyone focused on long term cash flows rather than short term share moves.
Peer leading cash margins near 97% combined with a debt free balance sheet and roughly $1 billion of available liquidity enable disciplined capital deployment into high returning royalty and stream acquisitions, which can compound cash flow per share and underpin continued dividend growth.
See why 8 investors see OR Royalties as 21% undervalued.
Result: Fair Value of CA$62.23 (UNDERVALUED)
Still, the bullish OR Royalties story could fray if precious metal prices retreat meaningfully or if key partner projects suffer delays or weaker mine plans.
Find out about the key risks to this OR Royalties narrative.
Another View on OR Royalties’ Valuation
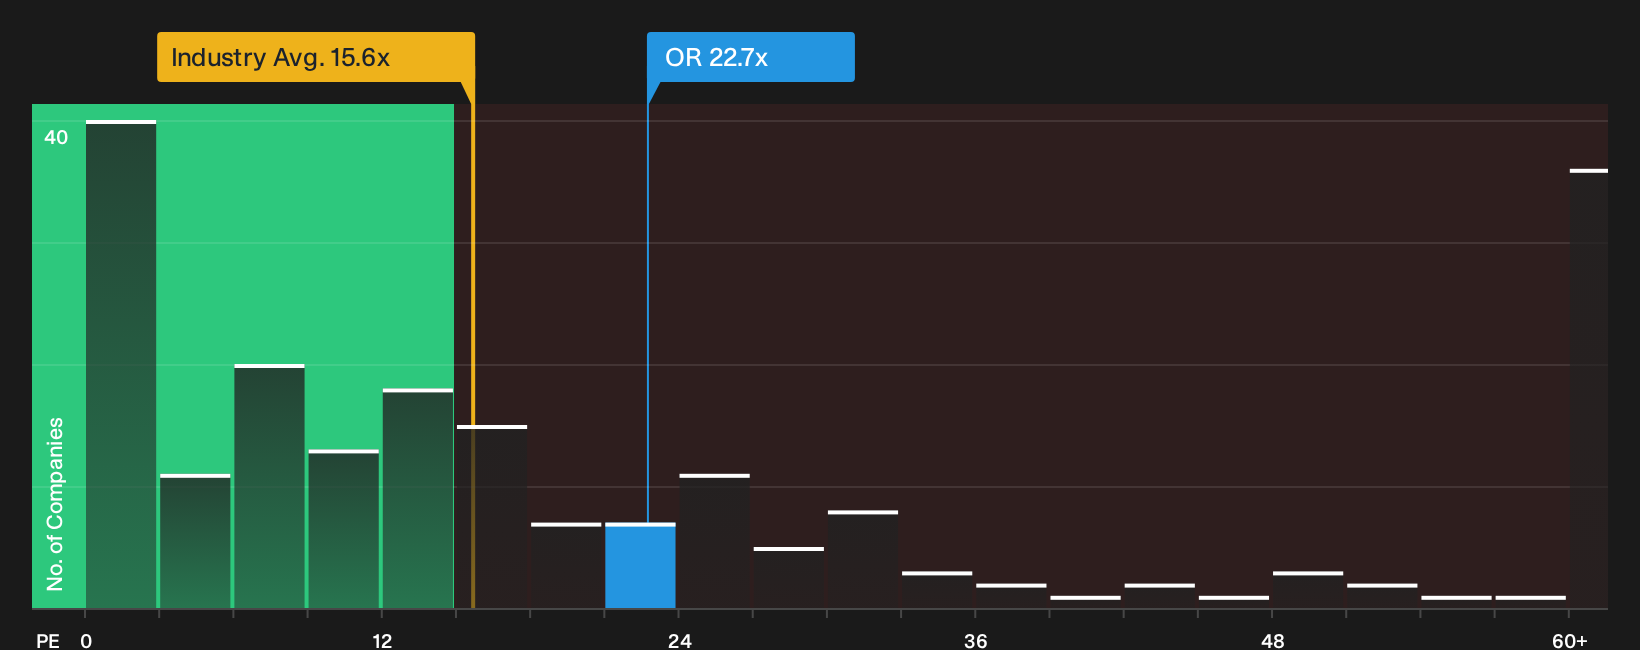
The earlier narrative leans on cash flow and fair value estimates that suggest OR Royalties is undervalued. A straight P/E check paints a harsher picture. The stock trades at 22.7x earnings, while peers average 10.7x, and the fair ratio is 14x. That gap points to real multiple risk if sentiment cools.
For investors who lean more on simple valuation markers, the question is whether OR Royalties’ royalty model and growth profile really justify paying a premium P/E that far above both sector averages and the fair ratio, or whether patience for a better entry point is the cleaner move.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals so far on OR Royalties, with strong long term compounding set against valuation questions and project execution risk, mean your own work matters. Review the numbers, pressure test the narratives and weigh both the upside and the hazards through the lens of 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond OR Royalties?
If OR Royalties has your attention, do not stop there. Broaden your watchlist now and give yourself more ways to put your capital to work.
- Target potential mispricing by scanning companies that screen as high quality yet out of favor through the 6 high quality undervalued stocks.
- Strengthen your income stream by focusing on reliable cash returns sourced via the 1 dividend fortresses.
- Dial down portfolio stress by concentrating on businesses with robust finances using the 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com