
Applied Digital (APLD) Completes Polaris Forge 1 Expansion, Is The Valuation Gap Too Wide?
Applied Digital (APLD) just switched on the second phase of Building 2 at its Polaris Forge 1 AI campus, adding 75 MW of IT capacity and completing the facility’s 150 MW buildout.
That extra capacity goes live against a mixed trading backdrop for Applied Digital, with the share price up 5.05% over the last day to US$25.38 but down 23.23% over three months. The 3-year total shareholder return of about 4x hints at earlier enthusiasm now cooling as investors reassess execution and funding risks around its AI buildout.
Compare Applied Digital’s AI buildout to other high-conviction infrastructure plays by scanning the hand picked 90 AI infrastructure stocks.
Applied Digital now runs a much larger AI campus, yet the share price has cooled sharply in recent months. Is this a strong platform for high performance computing that has become mispriced, or fairly valued for the risks involved?
Most Popular Narrative: 63% Undervalued
Applied Digital’s most followed narrative points to a fair value of about $68.35 against the last close of $25.38, with that gap hinging on long-term AI leasing, heavy buildout, and meaningful balance sheet risk.
The company has recently secured long-term (15-year) leasing agreements with CoreWeave, a major AI hyperscaler, for its purpose-built AI/HPC data center campus, Polaris Forge 1, representing a total of $7 billion in contracted revenue and a multi-year, recurring, and predictable revenue stream that directly supports future revenue growth and cash flow stability.
See why 260 investors see Applied Digital as 63% undervalued.
That framework uses an 11.07% discount rate and assumes Applied Digital can reach about $3.0b of revenue and $295.0m of earnings by around 2029, while the stock trades on a future P/E multiple of roughly 104.7x in that scenario. The wide spread between bullish and cautious expectations, together with the sizeable debt load and concentrated hyperscaler exposure, means investors are weighing sizeable contract-backed visibility against funding and execution risks.
Result: Fair Value of $68.35 (UNDERVALUED)
Still, Applied Digital’s dependence on a few hyperscaler tenants and its sizeable debt load could quickly challenge that upside narrative if contracts slip or funding tightens.
Find out about the key risks to this Applied Digital narrative.
Another View On Applied Digital’s Valuation
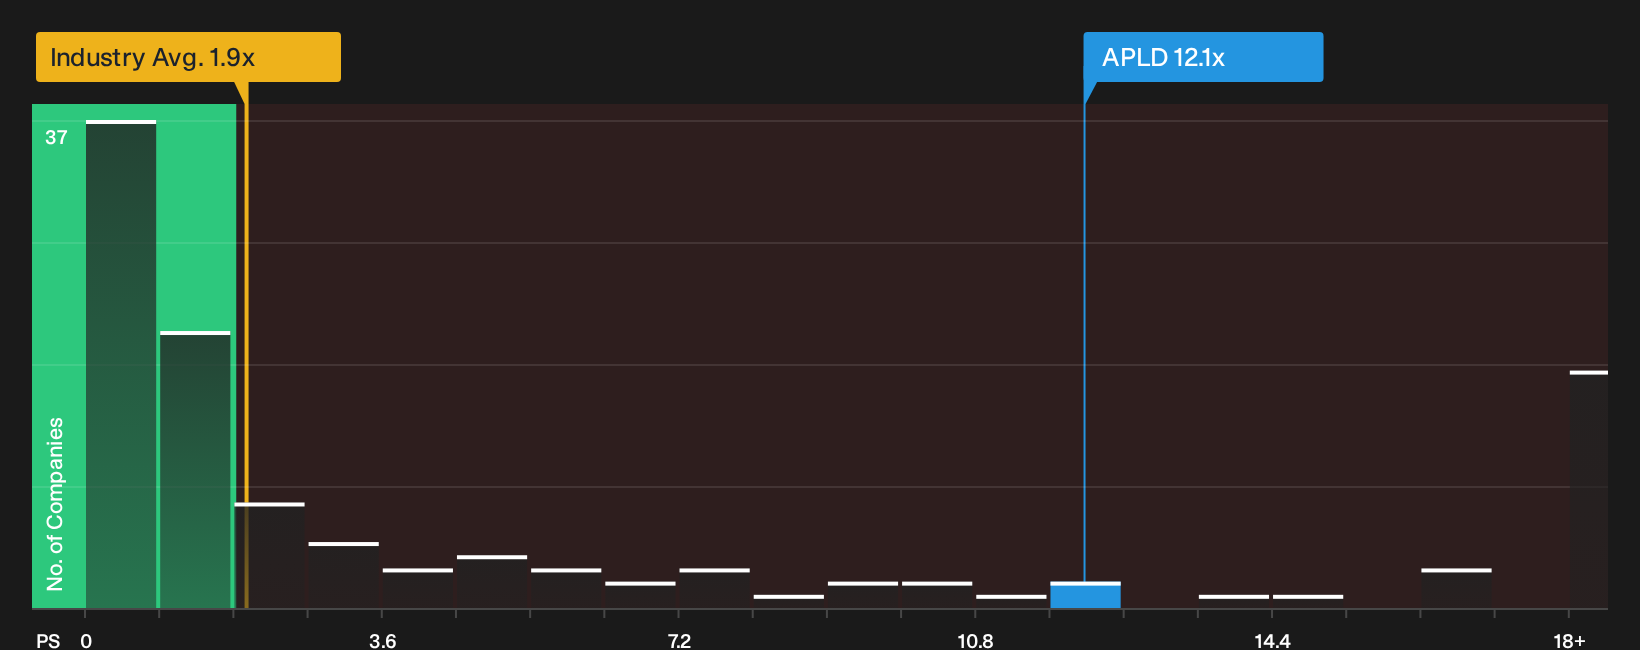
Those bullish fair value estimates for Applied Digital sit awkwardly next to the current pricing on its P/S ratio. The stock trades on roughly 12.1x sales compared with about 1.9x for the wider US IT group and a fair ratio of 5.5x, which points to meaningful valuation risk if sentiment cools from here.
That kind of gap can close in more than one way: through stronger fundamentals, a lower share price, or a mix of both. Which scenario do you think the market is really pricing in?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Applied Digital story feels finely balanced, with contract strength on one side and funding and tenant risk on the other. Move quickly to review the numbers and test your own thesis with the 1 key reward and 3 important warning signs.
Looking For More Investment Ideas Beyond Applied Digital?
If Applied Digital has sharpened your thinking, do not stop here. Broaden your watchlist now and keep fresh ideas coming before the market moves first.
- Target value first and hunt for quality companies trading below their estimated worth using the 31 high quality undervalued stocks.
- Protect your downside and focus on resilience by scanning the 31 resilient stocks with low risk scores that score well on stability and risk factors.
- Get ahead of the crowd and search for future leaders hiding in plain sight with the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com