
Maple Leaf Foods (TSX:MFI) Could Be 31% Undervalued Following Its U.S. Plant Protein Reset
Maple Leaf Foods reshapes U.S. plant protein footprint
Maple Leaf Foods (TSX:MFI) has kicked off a major reorganization of its U.S. plant protein operations, consolidating production at its Indianapolis facility while winding down plants in Seattle and Turners Falls.
The shift, tied to the Fuel for Growth initiative and expected to roll out over 12 to 18 months, aims to simplify the manufacturing network and sharpen the focus on a single Plant Protein Centre of Excellence.
Recent trading has been choppy for Maple Leaf Foods, with the share price down 7.2% over 30 days and 19.4% over 90 days, and a 1-year total shareholder return that declined 16.4%, even though the 3 and 5-year total shareholder returns remain positive at 22.9% and 27.0%.
Scan how Maple Leaf Foods' restructuring compares with other protein and packaged food players by checking our hand-picked list of solid balance sheet and fundamentals (7 results) that could better withstand operational shake-ups like this.
So with Maple Leaf Foods reshaping its plant protein footprint while the share price has already slid, is most of the easy upside gone, or is the market still underpricing this reset?
Most Popular Narrative: 31% Undervalued
Analysts tracking Maple Leaf Foods see a fair value of CA$35.90 against a last close of CA$24.76, which implies a wide gap that the current share price does not reflect, even after the recent restructuring headlines. That view rests on a discounted cash flow framework using a 6.44% discount rate and a detailed set of assumptions about revenue, margins and future earnings power.
Ongoing investments in manufacturing automation (for example, Bacon Center of Excellence and London Poultry facility) and supply chain optimization via the Fuel for Growth initiative are driving significant cost efficiencies, as reflected in expanding adjusted EBITDA margin, and are expected to further enhance margins and earnings long term. A strong product innovation pipeline, featuring numerous new product launches across premium, core, and adjacent categories, is diversifying Maple Leaf's offering and premiumizing the portfolio, which supports both volume growth and increases in average selling prices, positively impacting revenue and margin profile.
See why 20 investors see Maple Leaf Foods as 31% undervalued.
Result: Fair Value of CA$35.90 (UNDERVALUED)
Still, the Maple Leaf Foods story can change quickly if the Canada Packers spin off introduces execution hiccups, or if higher SG&A undercuts the expected margin reset.
Find out about the key risks to this Maple Leaf Foods narrative.
Another View: Multiples Paint A Richer Picture For Maple Leaf Foods
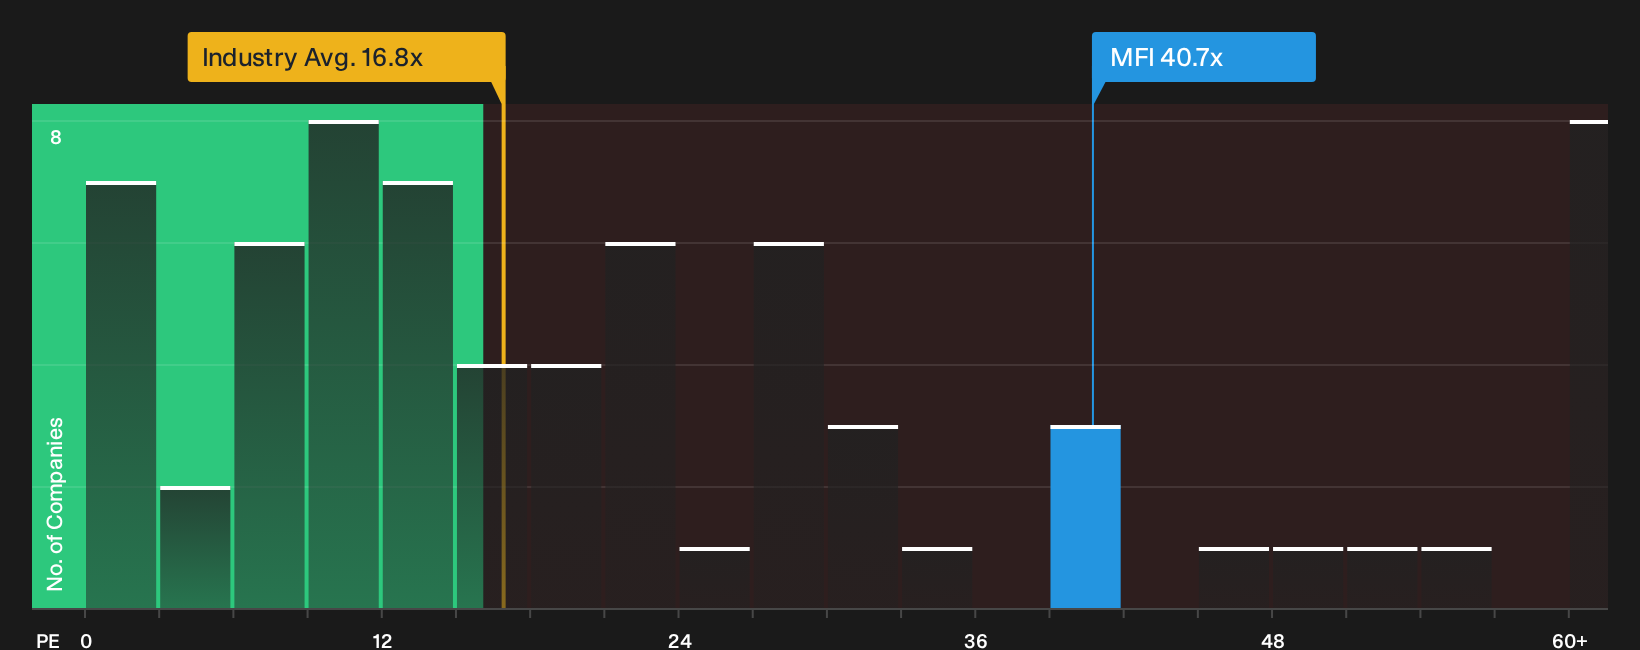
The discounted cash flow workup suggests Maple Leaf Foods looks undervalued, yet the P/E picture tells a tougher story. The stock trades on roughly 40.7x earnings versus about 16.8x for the wider North American Food group and a fair ratio estimate of 40.6x, which leans more toward fully priced than obviously cheap. The question is whether the gap to fair value is really a bargain, or simply compensation for execution and balance sheet risk that the model smooths over.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Maple Leaf Foods so far make this a moment to look at the evidence quickly and decide where you stand. To weigh both sides of the story in detail, start with the 4 key rewards and 3 important warning signs.
Looking for more Maple Leaf Foods style investment ideas?
Do not stop with Maple Leaf Foods when there are other opportunities on the table. Use these focused stock lists to quickly surface candidates that might deserve a place on your radar.
- Target potential mispricings by running your eye over our curated 6 high quality undervalued stocks that highlight companies the market may be pricing too cautiously right now.
- Lock in income prospects by reviewing the 1 dividend fortresses that feature higher yields backed by solid underlying businesses.
- Prioritise resilience first by working through the 8 resilient stocks with low risk scores which screens for companies with steadier profiles when conditions turn rough.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com