
Granite Construction (GVA) Wins Two Big Contracts As Undervalued View Faces A Fresh Test
Granite Construction (GVA) just landed two large infrastructure wins: a roughly $324.8 million Big Creek Tunnel contract in Ohio and a separate US$165 million defense facilities task order in Guam, both contributing to future backlog.
These contract wins arrive as Granite Construction trades at US$119.92, with a 1-day share price return of 2.63% and a 7-day share price return of 4.21%. However, the 90-day share price return is down 17.82%. Against that backdrop, the 1-year total shareholder return of 10.22% and the very large 3-year total shareholder return of about 3.2x suggest that longer term holders have still seen strong compounding, even as near term momentum has recently cooled.
Spot similar infrastructure contractors with growing backlogs by scanning our hand picked list of list of solid balance sheet and fundamentals (26 results).In the short term, Granite Construction stock has cooled, even as new Ohio and Guam work contributes to the backlog. Is the market reassessing the business, or did sentiment simply run ahead of itself and now reset the entry point?
Most Popular Narrative: 28% Undervalued
Against Granite Construction's last close of $119.92, the most followed narrative points to a fair value estimate of $167.20, which frames the recent pullback as a gap between price and the long term story.
Robust federal and state funding, particularly in historically underfunded regions like the Southeast and California, is driving a record backlog and strong multi-year demand pipeline, and this supports outsized revenue growth potential as public infrastructure investment continues to accelerate.
Recent acquisitions expand Granite's reach in high-growth Sunbelt and Western states as well as its materials vertical, positioning the company to benefit from long-term urbanization, population growth, and private sector development, fueling sustained revenue and volume expansion.
See why 4 investors see Granite Construction as 28% undervalued.
Result: Fair Value of $167.20 (UNDERVALUED)
Still, the bullish Granite Construction narrative can break if acquisition integration stumbles, or if public infrastructure funding or project timing turns less supportive.
Find out about the key risks to this Granite Construction narrative.
Another View On Granite Construction’s Valuation
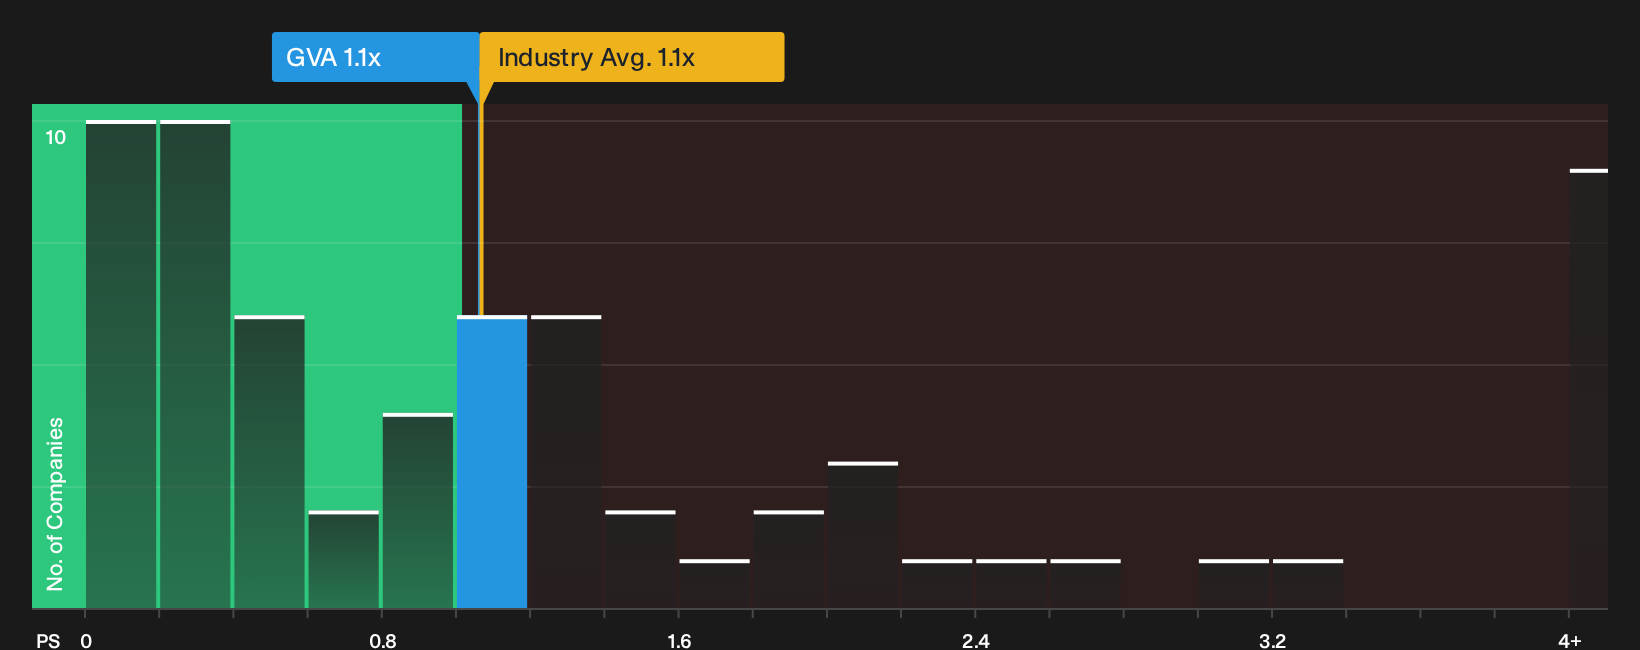
The earlier fair value work points to Granite Construction trading below an estimated worth of $167.20. Yet on a simple P/S lens, the picture is less generous. The stock trades at 1.1x sales, roughly in line with the US Construction industry at 1.1x and only slightly below a fair ratio of 1.2x. That narrows the margin of safety and raises a practical question for investors: Is the real upside in the cash flow story rather than in how the market prices each dollar of current revenue?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these around Granite Construction rarely stay unresolved for long, so it makes sense to review the data yourself and decide quickly where you stand. To weigh both the upside case and the concerns side by side, start with 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Granite Construction?
If Granite Construction has your attention, do not stop here. Put fresh ideas on your radar now so you are not chasing them later.
- Target dependable income streams by scanning for companies that resemble rock solid payers with the 7 dividend fortresses.
- Hunt for quality at a discount by reviewing the 31 high quality undervalued stocks before the market fully prices in their strengths.
- Protect your downside by focusing on resilient businesses using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com