
Are Sales And SUV Launch Altering The Investment Case For Stellantis (BIT:STLAM)?
- Stellantis reported second quarter 2026 sales of 324,277 vehicles compared with 324,825 a year earlier, with year to date deliveries at 958,463 vehicles versus 928,023 in the prior period.
- The 2027 Jeep Cherokee Trailhawk adds a higher priced, feature rich off road SUV to Stellantis' Jeep line, which could influence future product mix and margin focus.
- This article examines how Stellantis' investment narrative is shaped by its 2026 sales levels and the launch of the new Jeep Cherokee Trailhawk.
Stellantis Investment Narrative Recap
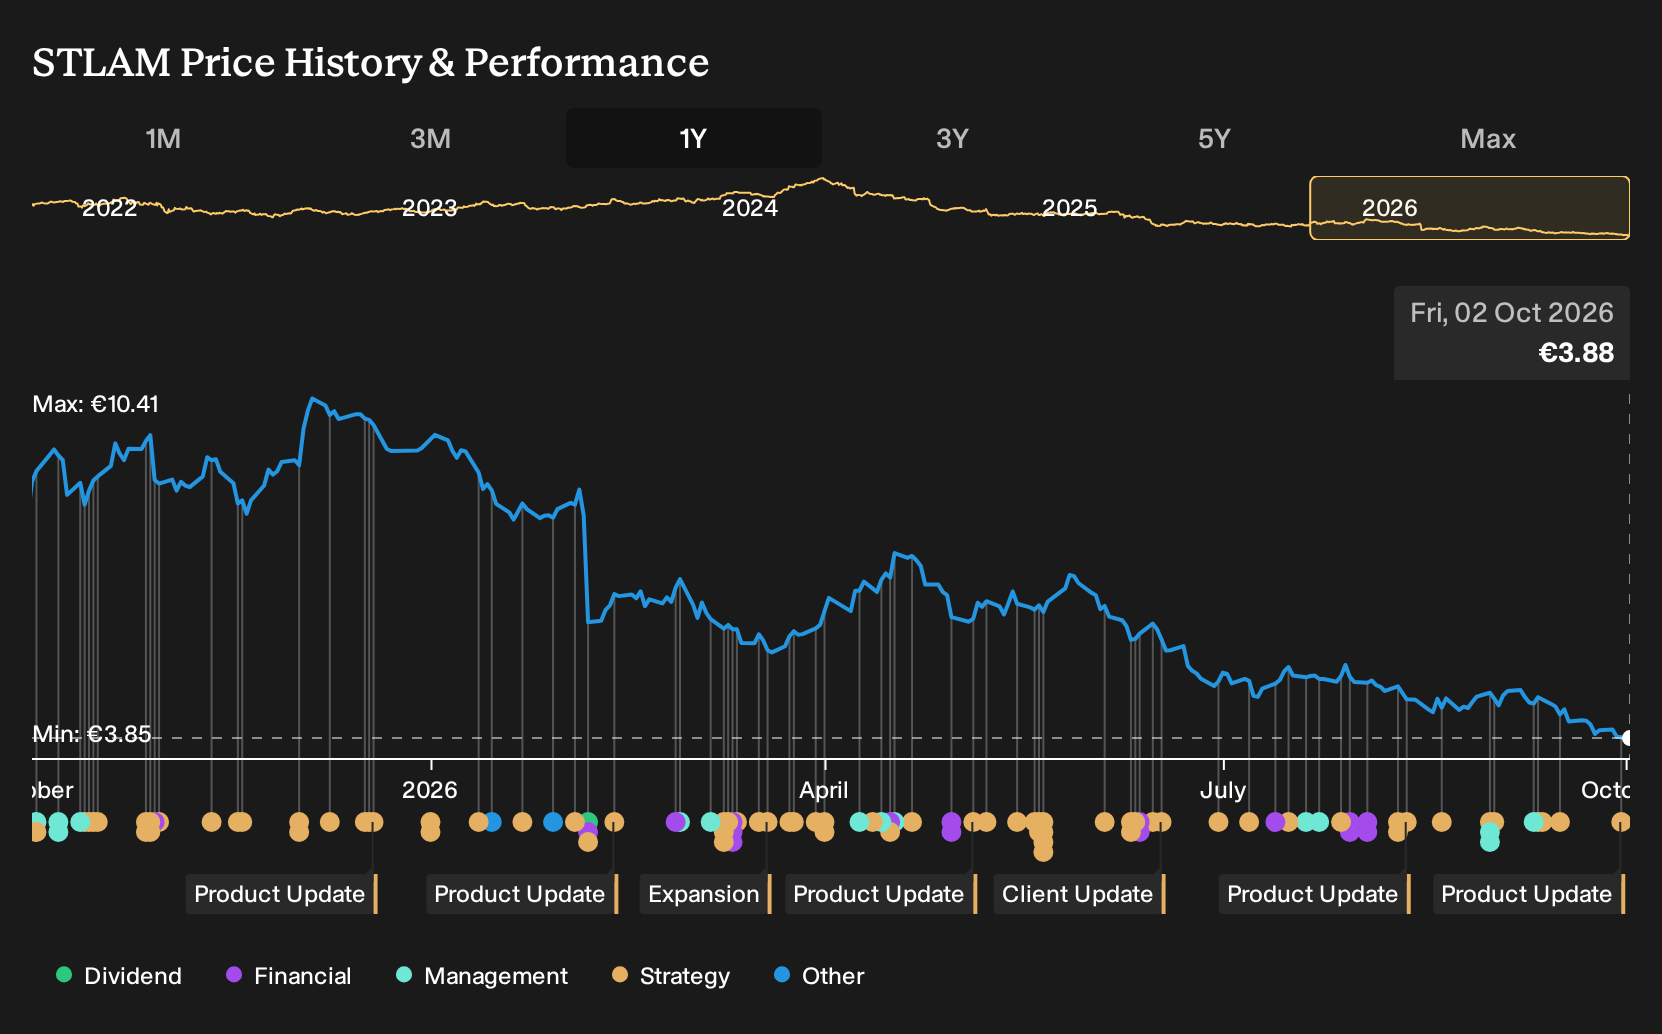
For an investor to stay with Stellantis, there needs to be confidence that a broad, multi brand portfolio can convert stable deliveries into healthier earnings over time. The latest quarter shows 324,277 vehicles sold, essentially in line with a year earlier, while year to date volumes of 958,463 vehicles modestly exceed the prior period. The near term focus stays on execution, cost control and mix.
The biggest near term swing factor is whether Stellantis can protect margins while facing tariff uncertainty, weak European light commercial demand and less profitable BEV ramps. Recent sales figures do not materially change that equation. The key risk remains ongoing restructuring and competitive pressure eroding pricing power and earnings quality.
The arrival of the 2027 Jeep Cherokee Trailhawk matters because it leans into a Jeep strength that investors already understand. This SUV combines off road credentials, hybrid powertrain and a richer feature set at a starting price of €44,625 including destination. That kind of product can influence mix, not just raw unit count.
For catalysts, investors will want to see whether vehicles like the Cherokee Trailhawk can support Stellantis in holding margins as electrification and regulation pressure profitability elsewhere. The off road focus, premium options and hybrid towing capability speak directly to Jeep brand equity. Execution risk sits in scaling production at Toluca, managing warranty exposure and keeping pricing discipline in a crowded SUV field.
On these analyst figures, Stellantis is tied to a narrative that points to €175.0b in revenue and €4.8b in earnings by 2029, built on an assumed 2.8% yearly revenue growth rate and an earnings swing of about €24.3b from a loss of €19.5b today.
Uncover why Stellantis' fair value indicates a 45% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You can read Stellantis very differently if you focus on the bullish catalyst of faster earnings repair. The most optimistic analysts were outlining revenue of about €189.9b and earnings near €11.1b by 2029, compared with the consensus of €175.0b and €4.8b. Those views predate this Trailhawk launch and the latest sales data, so they may shift as the story evolves.
Explore 10 other Stellantis fair value estimates, including one that suggests potential upside of up to 327% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Stellantis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Stellantis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stellantis' overall financial health at a glance.
Looking for more investment ideas beyond Stellantis?
Once you have formed a view on Stellantis, it can help to compare that thesis with other businesses that share similar financial strengths or different risk profiles. The Simply Wall St Screener gives you a quick way to line up alternatives side by side and pressure test your thinking.
- If capital preservation is a priority, start by scanning a universe of sturdier balance sheets and steadier fundamentals with the 228 resilient stocks with low risk scores.
- For investors hunting for mispriced quality, broaden your watchlist using the 196 high quality undervalued stocks and see which companies combine solid cash flows with supportive valuations.
- If you prefer businesses that are less crowded by attention, cast a wider net over the 616 high quality undiscovered gems and compare their fundamentals with what you see at Stellantis.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com