
3 Indian Growth Stocks With At Least 24% Revenue Growth
Global bond yields have been surging in recent weeks, with investors increasingly treating top tier government debt as a rare safe harbour. When money flows so aggressively into perceived havens, risk capital tends to be choosier and rewards businesses that already show strong growth and have leaders with real skin in the game. This piece looks at three Indian fast growers where insiders hold meaningful stakes and explains why they deserve a closer look now.
The three Indian stocks that follow are just a small sample, and the full screen surfaced 107 more businesses with equally compelling insider-backed growth stories that are not covered in this article. If you want to move beyond headlines and actually identify, filter, and analyze these high conviction ideas, head straight to the Fast Growing Stocks With High Insider Ownership screener.
Rubicon Research (NSEI:RUBICON)
Rubicon Research aligns with the screener’s theme through its specialty pharmaceutical platforms, where proprietary drug delivery technology supports a focused push into higher value formulations backed by committed insider ownership.
Rubicon Research develops specialty pharmaceutical products using its RubiReten and RubiSRL drug delivery platforms. All ₹19,358 million in revenue comes from pharmaceutical products and related services, and the business is currently valued at about ₹270b by the market.
"Consistent R&D investment at roughly 10% to 11% of revenue, together with a track record of commercialising 88% of approved products, points to a deeper product basket that can support future revenue and earnings visibility."
What happens to margins if one major assumption about how that expanding product mix is priced and absorbed by customers starts to shift?
If that pricing power is already starting to shift, reading the full narrative for Rubicon Research helps you see whether Rubicon Research is quietly compounding or stalling out.

Atlanta Electricals (NSEI:ATLANTAELE)
Atlanta Electricals manufactures power and special duty transformers for transmission, solar, and industrial projects, directly tied to infrastructure and renewable build outs. It generated about ₹20,027 million from transformer manufacturing in India and carries a market value of roughly ₹132b.
Earnings growth of 74.1% over the past year, paired with a 23.4% ROE and rising profit margins, places Atlanta Electricals firmly in the fast growing, insider aligned transformer theme. Investors still have to weigh how much of that earnings momentum is already reflected in the current valuation if even a single key assumption changes.
If you want to see how much of that earnings surge is already priced in, run Atlanta Electricals through the analysis report for Atlanta Electricals for the full valuation story.
Bajel Projects (NSEI:BAJEL)
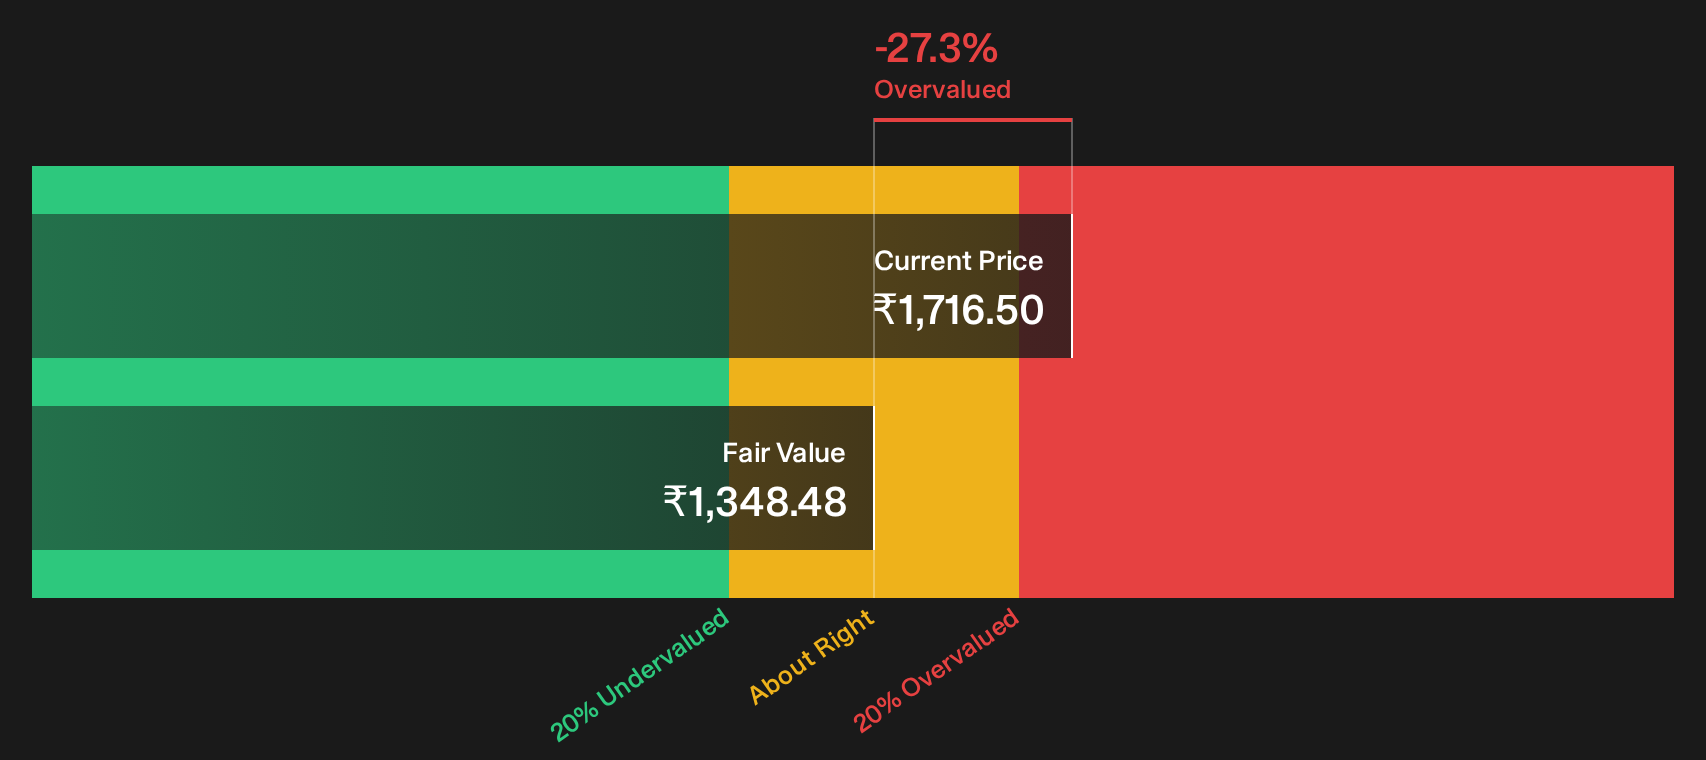
Bajel Projects is an EPC specialist focused on extra high voltage power transmission and distribution contracts, a clear fit with a high growth, insider aligned infrastructure theme. It generated about ₹27,508 million from power transmission and distribution and carries a market value near ₹18.9b.
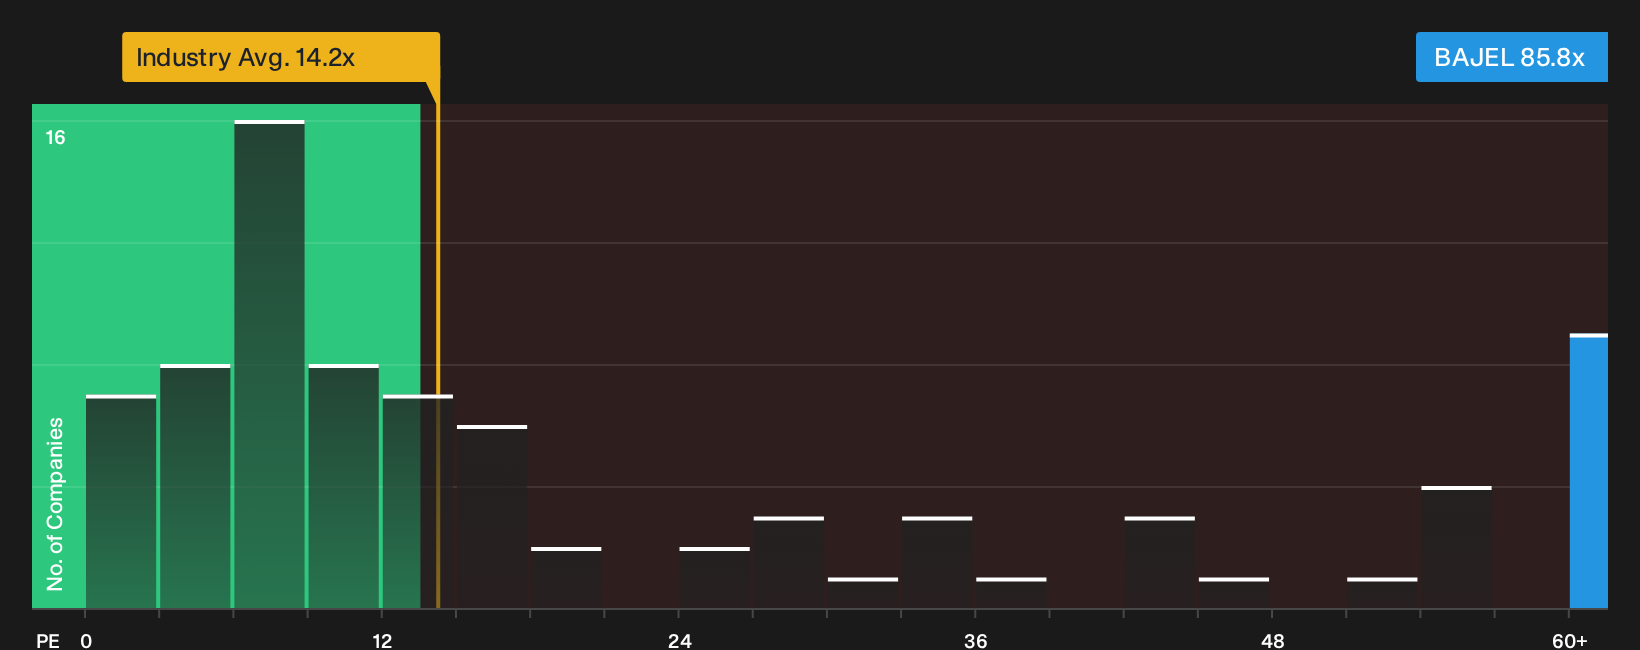
Earnings increased 71% over the past year and analysts report rapid top line and profit expansion off a growing order book in high voltage lines and substations. That growth story comes with a rich P/E near 85.8x and thin 0.8% margins, depending on how one unseen pressure plays out.
That pressure point is exactly where Bajel Projects could be most misread. Use the analysis report for Bajel Projects to see whether rich multiples are masking or rewarding execution.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum builds, the best setups get caught quickly and pricing power drops fast. Scan these under the radar for now and get in early.
- Target resilient compounding potential by scanning the 228 resilient stocks with low risk scores curated to highlight businesses where volatility scores stay contained while fundamentals still pull their weight.
- Ride structural demand shifts by tracking the 40 power grid technology and infrastructure stocks curated to spotlight operators supplying the backbone of tomorrow's electricity and grid upgrades.
- Back real earnings engines by reviewing the 37 profitable AI stocks that aren't just burning cash curated to surface AI players already converting hype into cash flow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com