
3 Australian Penny Stocks To Watch In October 2026
Global bond markets recently steadied after a sharp sell off that pushed borrowing costs to multi decade highs, reminding investors how quickly sentiment can swing back toward risk assets such as equities. That kind of reset can put smaller Australian companies with stronger balance sheets and limited dilution firmly on the radar. This article highlights three low priced shares from our quality focused penny stock pool that have all moved higher over the past year.
The three companies covered below are only a sample, with the full screen surfacing 14 more low priced Australian shares that share similar balance sheet strength, limited dilution and insider alignment. To identify and analyze the rest of these elite penny stock ideas, head straight into the Elite Penny Stocks screener.
Ora Banda Mining (ASX:OBM)
Ora Banda Mining runs the 100% owned Davyhurst Gold Project in Western Australia, producing and selling gold and gold bearing ore that anchors its place in a quality focused penny stock pool. The group generated about A$807 million from gold production and exploration in Australia and has a market cap near A$2.85b.
Ora Banda Mining lines up closely with the Elite Penny Stocks theme because Davyhurst is an operating gold project that backs high earnings growth, strong ROE above 40% and a valuation that some models see as well below fair value. That mix of profitability, balance sheet strength and growth potential could look very different if one unseen pressure on future margins shifts direction.
If pressure on future margins is your main concern, go straight to the 4 key rewards and 1 important warning sign for the full risk reward picture.
Alkane Resources (ASX:ALK)
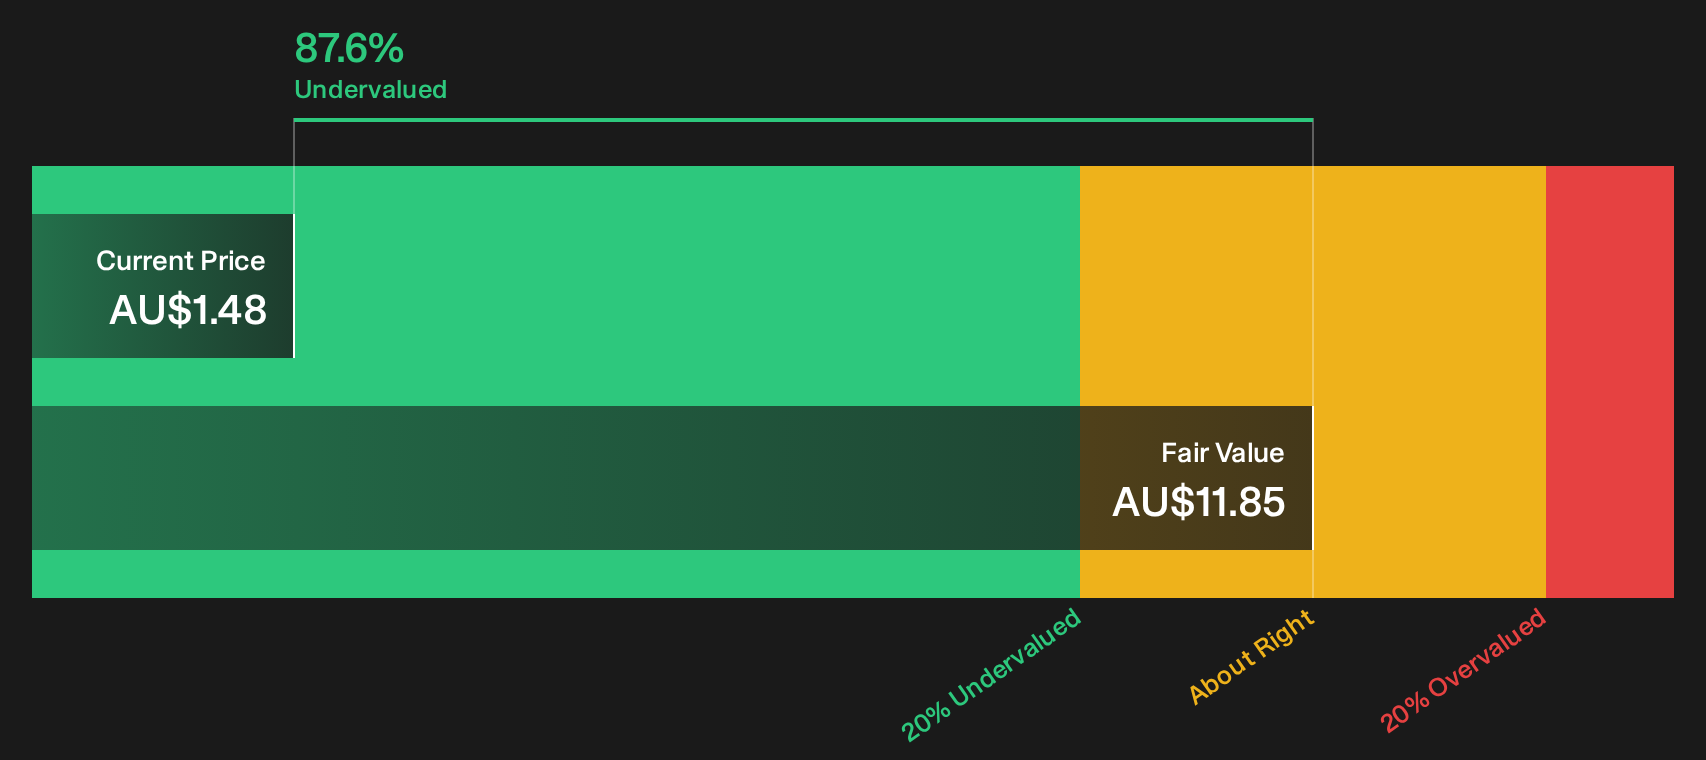
Alkane Resources brings a different flavour to this Elite Penny Stocks group, with its Tomingley gold mine anchoring real production while two other operations and exploration projects add extra torque to the story.
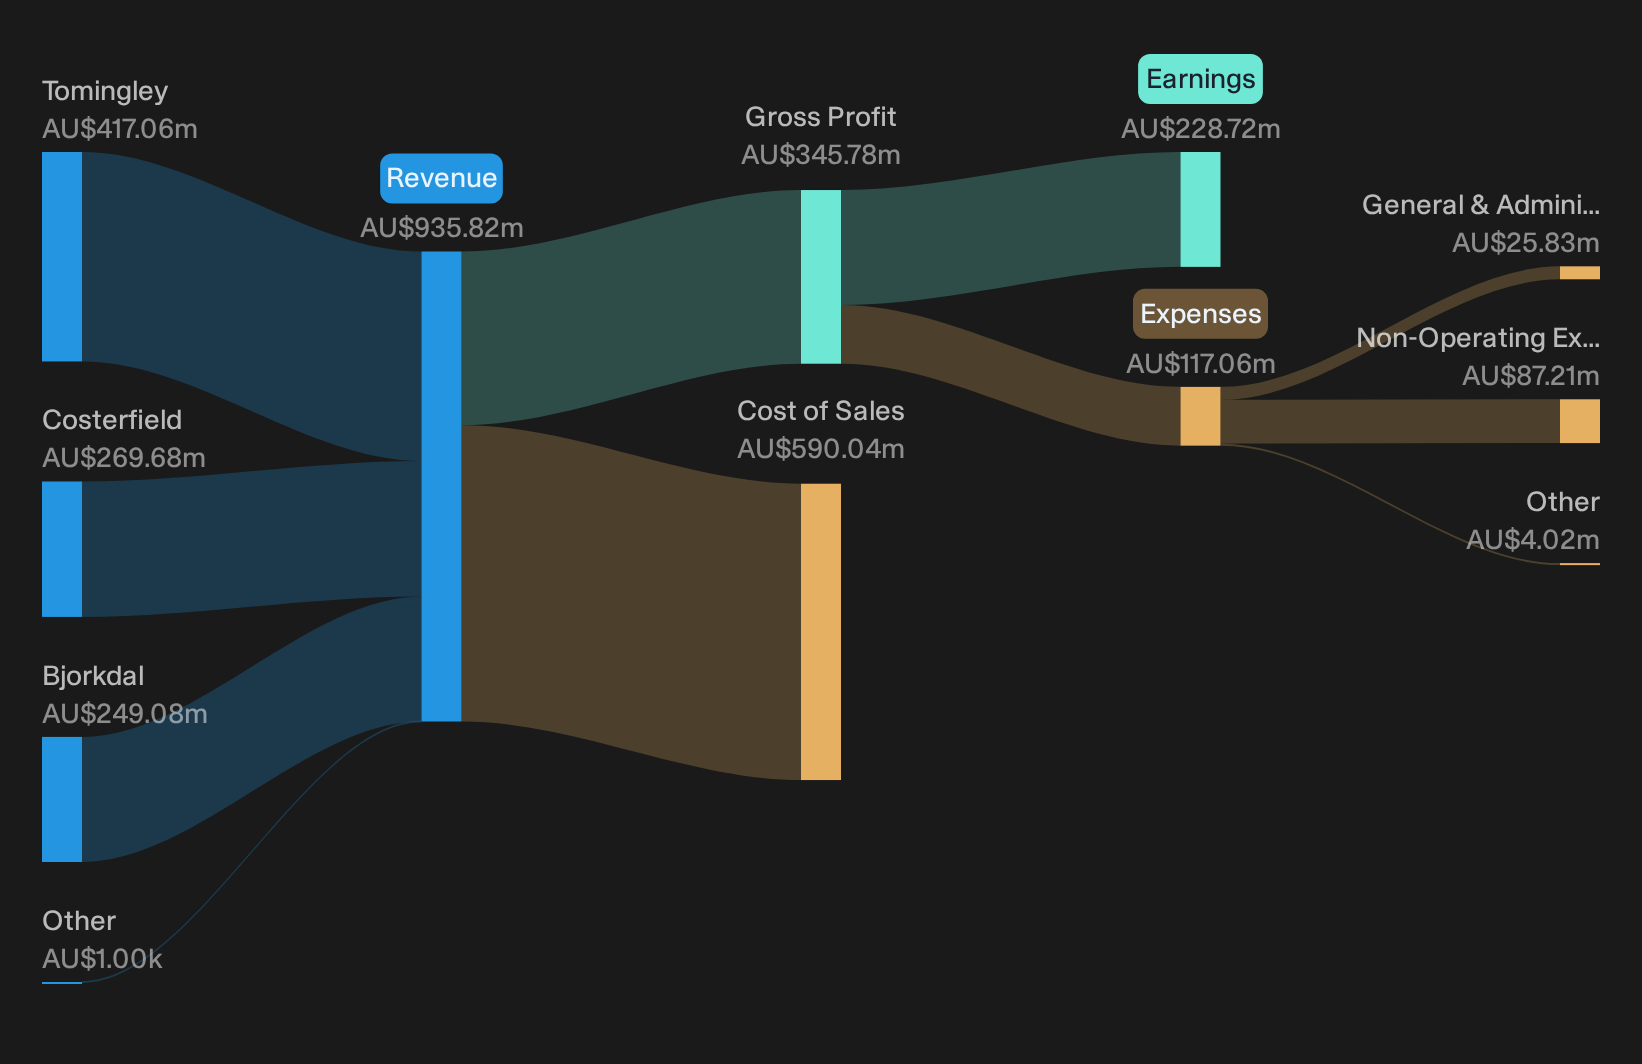
Alkane Resources is a multi mine gold producer and explorer, with the Tomingley operation generating A$417 million of revenue, Bjorkdal A$249 million and Costerfield A$270 million, all from Australia based reporting, and the group valued at about A$2.58b.
"The main risk is that Alkane is now a more complex business. Instead of one operation, investors must understand three mines, three jurisdictions, different cost structures, underground mining risk, antimony market volatility, and a large future capex project at Boda-Kaiser."
What happens if a single assumption inside that growth and funding puzzle shifts against Alkane Resources could matter far more than headline output guidance.
That kind of single assumption risk is exactly why it pays to read the full narrative for Alkane Resources and see how Alkane Resources could still accelerate from here.
NRW Holdings (ASX:NWH)
NRW Holdings is a diversified contractor to Australia’s resources and infrastructure sectors, with its civil arm providing concrete heavy works that tie directly into the Elite Penny Stocks theme. Revenue is spread across Mining at about A$1.5b, Civil A$862 million, MET A$1.3b and EMIT A$684 million, with the group valued near A$3.7b.
For NRW Holdings, the appeal in this Elite Penny Stocks pool comes from its mix of hard infrastructure exposure and a growing project book that speaks directly to long term demand for concrete heavy civil works.
"The significant expansion in the project pipeline and order book, underpinned by ongoing global demand for critical minerals such as lithium and copper for electrification and energy transition, positions NRW Holdings to capture robust future revenue growth as mining investment in Australia accelerates."
What happens if one assumption behind NRW Holdings’ margin improvement shifts direction will likely matter far more than any headline revenue target.
That margin question is exactly why reading the full narrative for NRW Holdings can be useful, as it connects the project pipeline to areas where NRW Holdings could still be accelerating.

Seeking Alternatives Before The Crowd?
Fresh ideas can move fast when momentum builds and prices start flying. Spot potential breakouts under the radar for now. Do the work while it matters and get in early.
- Track cash rich businesses that aim to protect dividends even when sentiment drops by scanning the 3 dividend fortresses before income hunters crowd in.
- Catch potential breakout miners riding renewed interest in precious metals by running the 36 elite gold producer stocks while these producers remain under heavier radars.
- Follow the build out of future power demand by reviewing the 40 power grid technology and infrastructure stocks and see which infrastructure players could gain momentum next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com