
Will New AI Product Launches Change MongoDB (MDB) Narrative
- MongoDB announced MongoDB 9.0, Atlas Infinite, Atlas Agent Engine, and a Cognition partnership, focusing on performance, AI agents, and faster migrations, while also increasing its share repurchase authorization to US$2b.
- The combination of Atlas Infinite’s consumption-based pricing, AI-focused Agent Engine, and Devin-powered modernization support directly targets workload elasticity, migration costs, and platform stickiness for large enterprises.
- We will look at how MongoDB’s investment narrative is affected by Atlas Infinite’s consumption-based scale model and AI-focused product stack.
MongoDB Investment Narrative Recap
To own MongoDB, you need to be comfortable with a thesis that centers on Atlas as a multi-cloud data platform that can handle both traditional enterprise workloads and newer AI-heavy applications. The recent releases of MongoDB 9.0, Atlas Infinite, and Atlas Agent Engine speak directly to that, but the near term catalyst still looks operational. Execution on AI and data workloads needs to show up in customer usage and deals.
The biggest risk remains competitive and economic pressure on Atlas driven by hyperscaler databases and open source options, which can keep pricing and margins under strain. In addition, CEO turnover and insider selling combine with share-price volatility to raise execution and perception risk. The expanded buyback and product launches do not fully change those near term watchpoints yet.
Atlas Infinite looks most relevant for you as an investor trying to connect this Investor Day to the existing bull and bear cases. It separates compute from storage and introduces consumption-based pricing within Atlas, which directly addresses workload elasticity and cost sensitivity, especially for AI use cases that can spike usage sharply.
That matters because current catalysts already rely on Atlas gaining a bigger share of customer workloads and improving recurring revenue quality. If Atlas Infinite and MongoDB 9.0 help migrate larger, more variable projects to the cloud without painful replatforming, they could support that thesis. The flip side is clear. Any uptake that trails expectations would leave MongoDB more exposed to cloud-native rivals and temper enthusiasm around earnings growth forecasts.
MongoDB's current narrative assumes revenues reach US$4.6b and earnings come in at US$295.3m by 2029, based on analyst expectations for 17.9% yearly top line growth and an earnings increase of roughly five times from US$58.9m today.
Uncover why MongoDB's fair value indicates a 27% potential upside to its current price, a discount that could narrow more quickly than many investors expect.
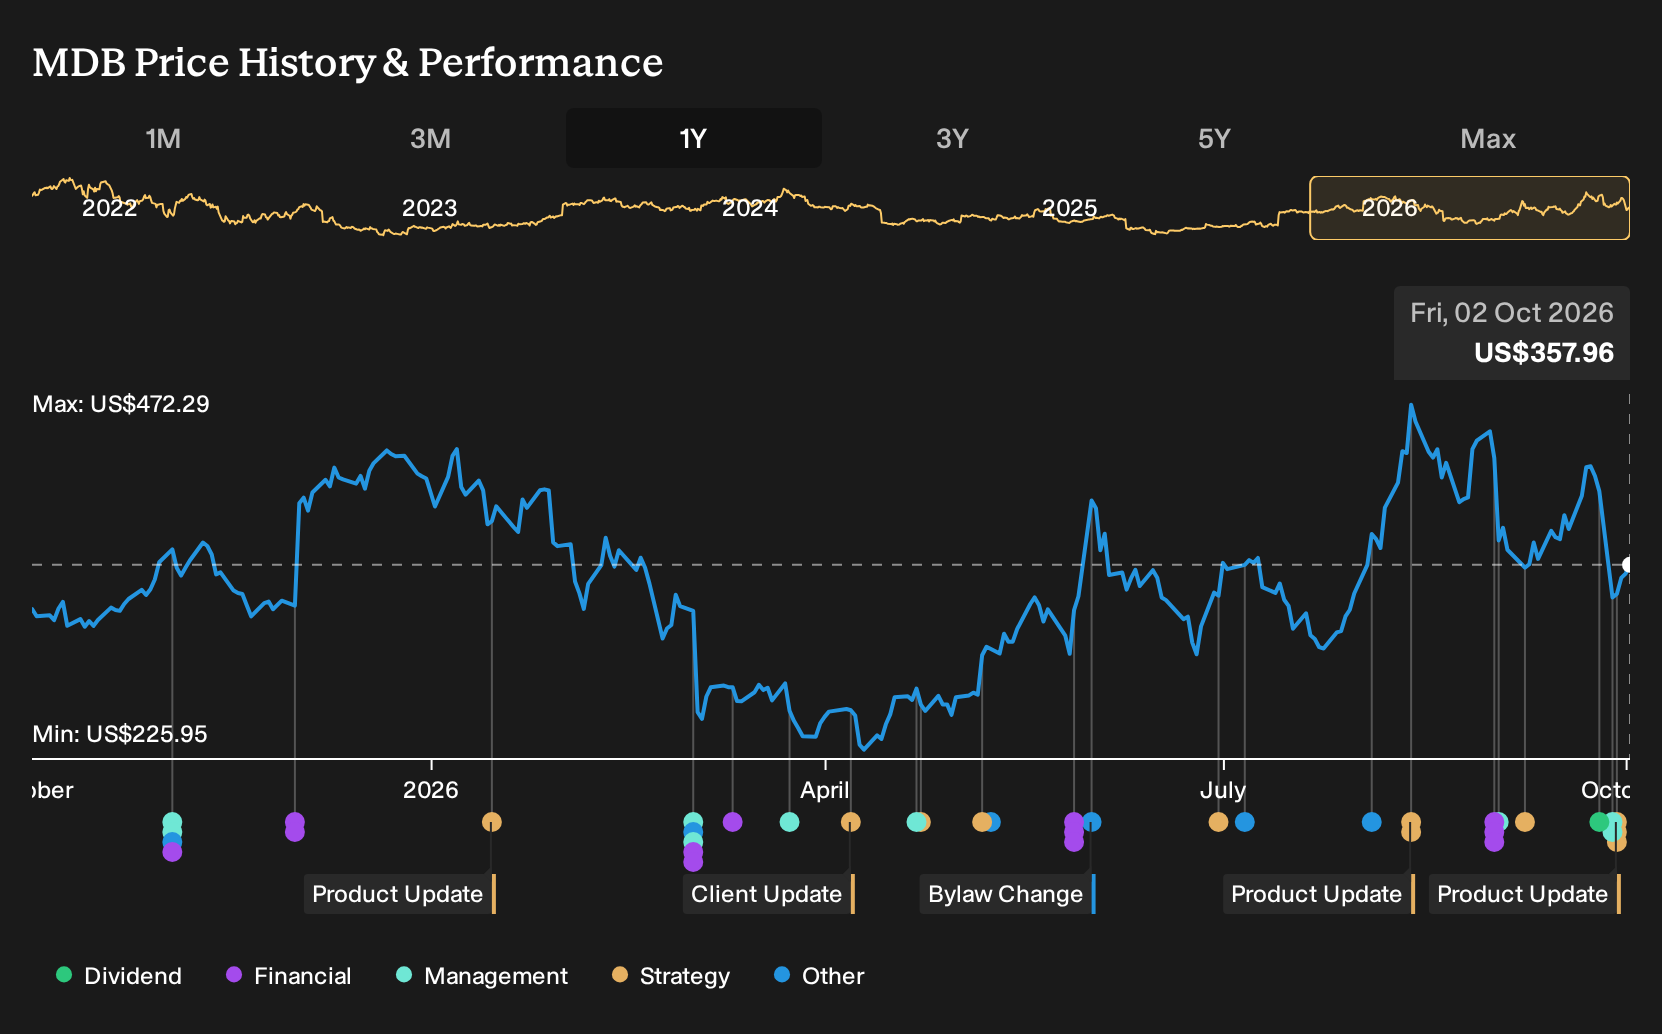
Exploring Other Perspectives
One alternate view focuses on earnings risk rather than product upside. The most bearish analysts saw MongoDB reaching only US$4.5b of revenue and US$37.9m of earnings by 2029, with a very high implied P/E. That is a far more cautious story. These projections all predate the Atlas Infinite and Agent Engine announcements, so opinions may move.
Explore 3 other MongoDB fair value estimates, including one that suggests it could be worth just $371.17.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your MongoDB research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MongoDB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MongoDB's overall financial health at a glance.
Looking For More Ideas Beyond MongoDB?
If MongoDB's AI and data story has you thinking more broadly about where to deploy capital, it can help to line it up against a wider field of potential opportunities. A focused stock screener gives you a faster way to compare quality, balance sheet strength, and income potential instead of sifting through tickers one by one.
- For readers who care most about quality at a reasonable entry point, start with a tight group of 31 high quality undervalued stocks that pair solid fundamentals with potentially attractive pricing.
- If capital preservation and resilience are higher on your checklist, filter for a 31 resilient stocks with low risk scores to see which businesses score well on financial strength and volatility.
- Income focused investors can zero in on dependable payouts by scanning a handpicked set of 7 dividend fortresses that aim to combine yield with staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com