
Are Rising Long Term Treasury Yields Altering The Investment Case For Great West Lifeco Stock?
- Great-West Lifeco has been highlighted as a long duration liability insurer whose life, pension, and annuity businesses are closely tied to fluctuations in 30 year US Treasury yields, with rising yields influencing how its products are priced and funded.
- The focus on pricing pressure and new competitors entering long dated savings and protection markets points to potential strain on Great-West Lifeco's segment level earnings, even as its liability profile should, in theory, benefit from higher long term risk free rates.
- We will look at how Great-West Lifeco's investment narrative holds up when long term US Treasury yields climb and liability pricing tightens.
Compare how Great-West Lifeco's rate sensitive model stacks up against other insurers positioned for higher long term yields by scanning our curated list of 8 resilient stocks with low risk scores.
Great-West Lifeco Investment Narrative Recap
To own Great-West Lifeco, you need to believe its mix of long dated insurance guarantees and fee based retirement and wealth businesses can keep generating solid earnings as rates stay higher and competition intensifies. The near term swing factor is how effectively it reprices life, pension, and annuity contracts as 30 year U.S. Treasury yields move.
The biggest short term risk is margin pressure in U.S. retirement and wealth, where fee compression and competitive pricing could bite just as higher yields reshape product economics. If pricing pressure or participant outflows accelerate from retiring baby boomers, organic growth and fee income could soften.
There have been no fresh company announcements tied directly to this move in long dated U.S. yields, so the focus stays on previously outlined priorities. Management has been investing heavily in digital transformation and efficiency, with post tax charges of CA$250 million to CA$300 million, with the aim of achieving a leaner expense base over time.
For you as a shareholder, execution on those technology and process projects matters more now that liability pricing is tightening. If Great-West Lifeco can convert those investments into lower unit costs in Empower and other fee based segments, it gains more room to compete on price without giving up profitability, which ties directly into the main catalyst and the key risk around margins.
Great-West Lifeco's current earnings are CA$4.4b, with analysts forecasting CA$5.2b of earnings by 2029. This implies an increase of about CA$0.8b, or roughly 1.2x current levels. Based on the same projections, revenues are expected to reach CA$45.1b by 2029, which would align with the assumed 7.4% yearly revenue growth rate built into the long range model.
Uncover how Great-West Lifeco's fair value indicates a 4% potential upside to its current price, a gap that could close sooner than many expect.
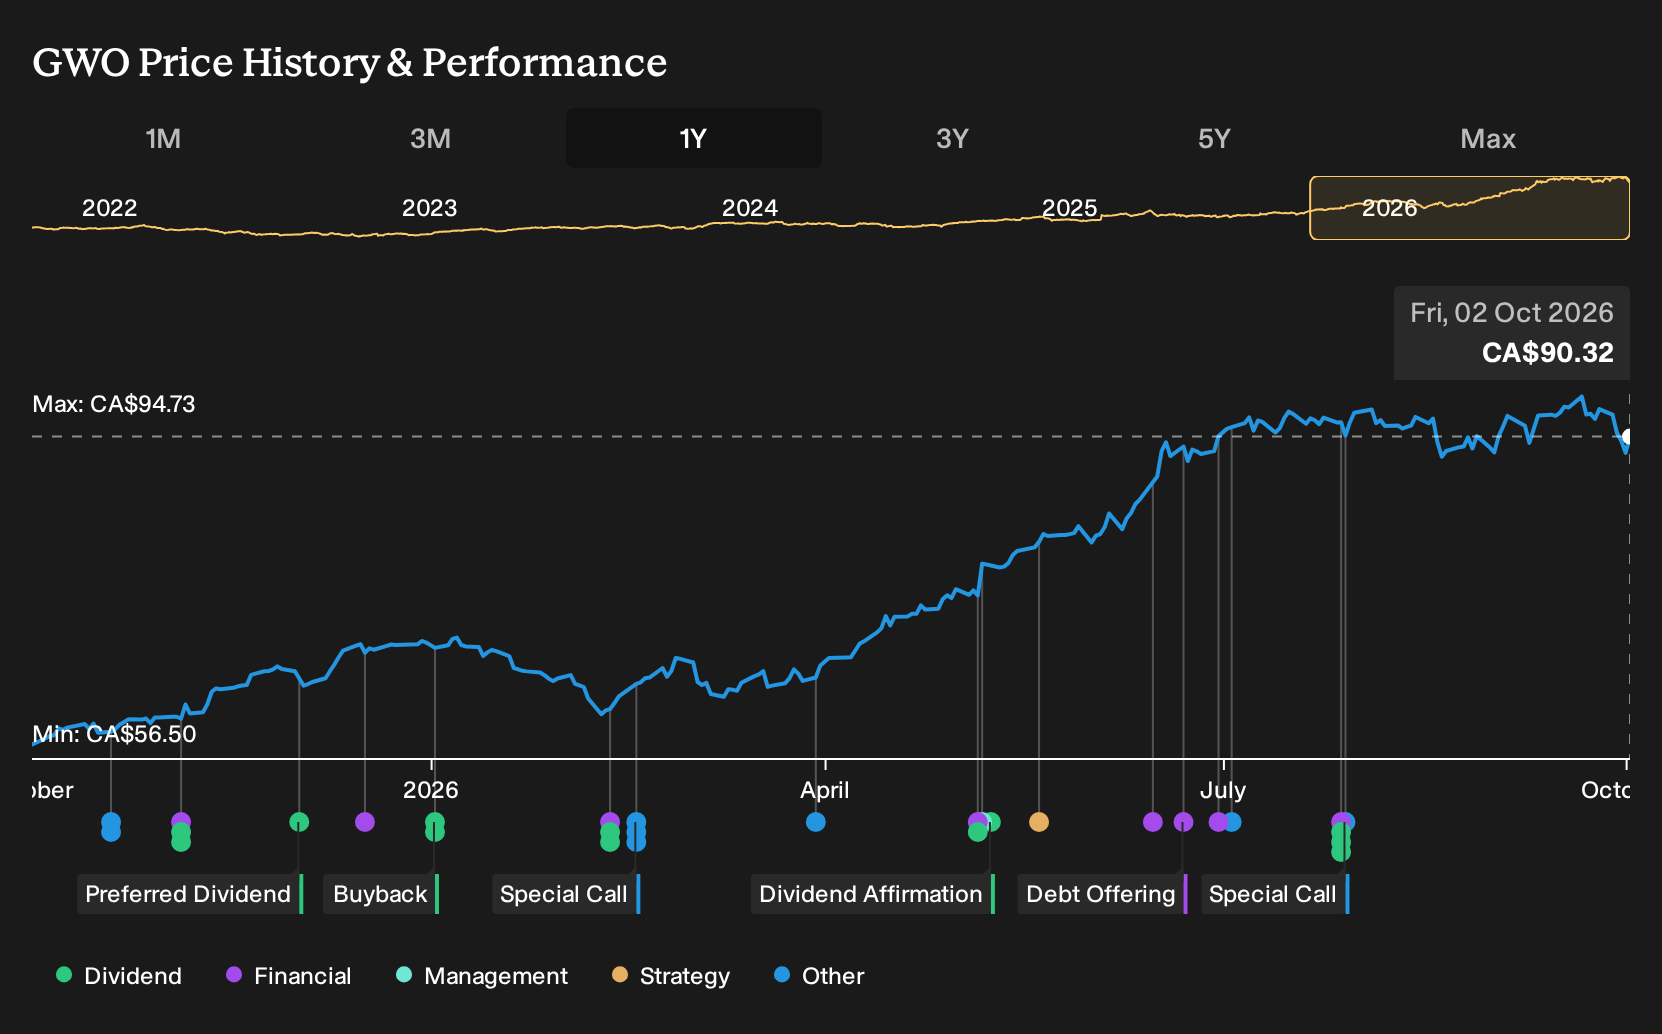
Exploring Other Perspectives
One alternate view on Great-West Lifeco leans hard into the earnings potential from capital light businesses. The most optimistic analysts had already pencilled in CA$46.1b of revenue and CA$6.7b of earnings by 2029 before this latest move in long term yields. That is a far rosier setup than the baseline. Treat it as one of several possible paths and explore which narrative best fits your own expectations as new information emerges.
Explore 2 other Great-West Lifeco fair value estimates, including one that suggests as much as 85% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Great-West Lifeco research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Great-West Lifeco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Great-West Lifeco's overall financial health at a glance.
Looking for more Great-West Lifeco sized investment ideas?
If this review of Great-West Lifeco has sharpened your thinking and you want to pressure test that view against other opportunities, the Simply Wall St Screener can help you line up potential candidates side by side and apply the same discipline to each one.
- For investors who care most about valuation support and business quality, check out a curated set of 6 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- If resilience is your priority, especially when markets feel choppy, scan a focused 8 resilient stocks with low risk scores that emphasises sturdier balance sheets and milder risk profiles.
- Income focused readers can size up potential payers by reviewing a hand picked group of 1 dividend fortresses that aim to pair higher yields with durable fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com