
Something Changed In The HUB24 Story This Year
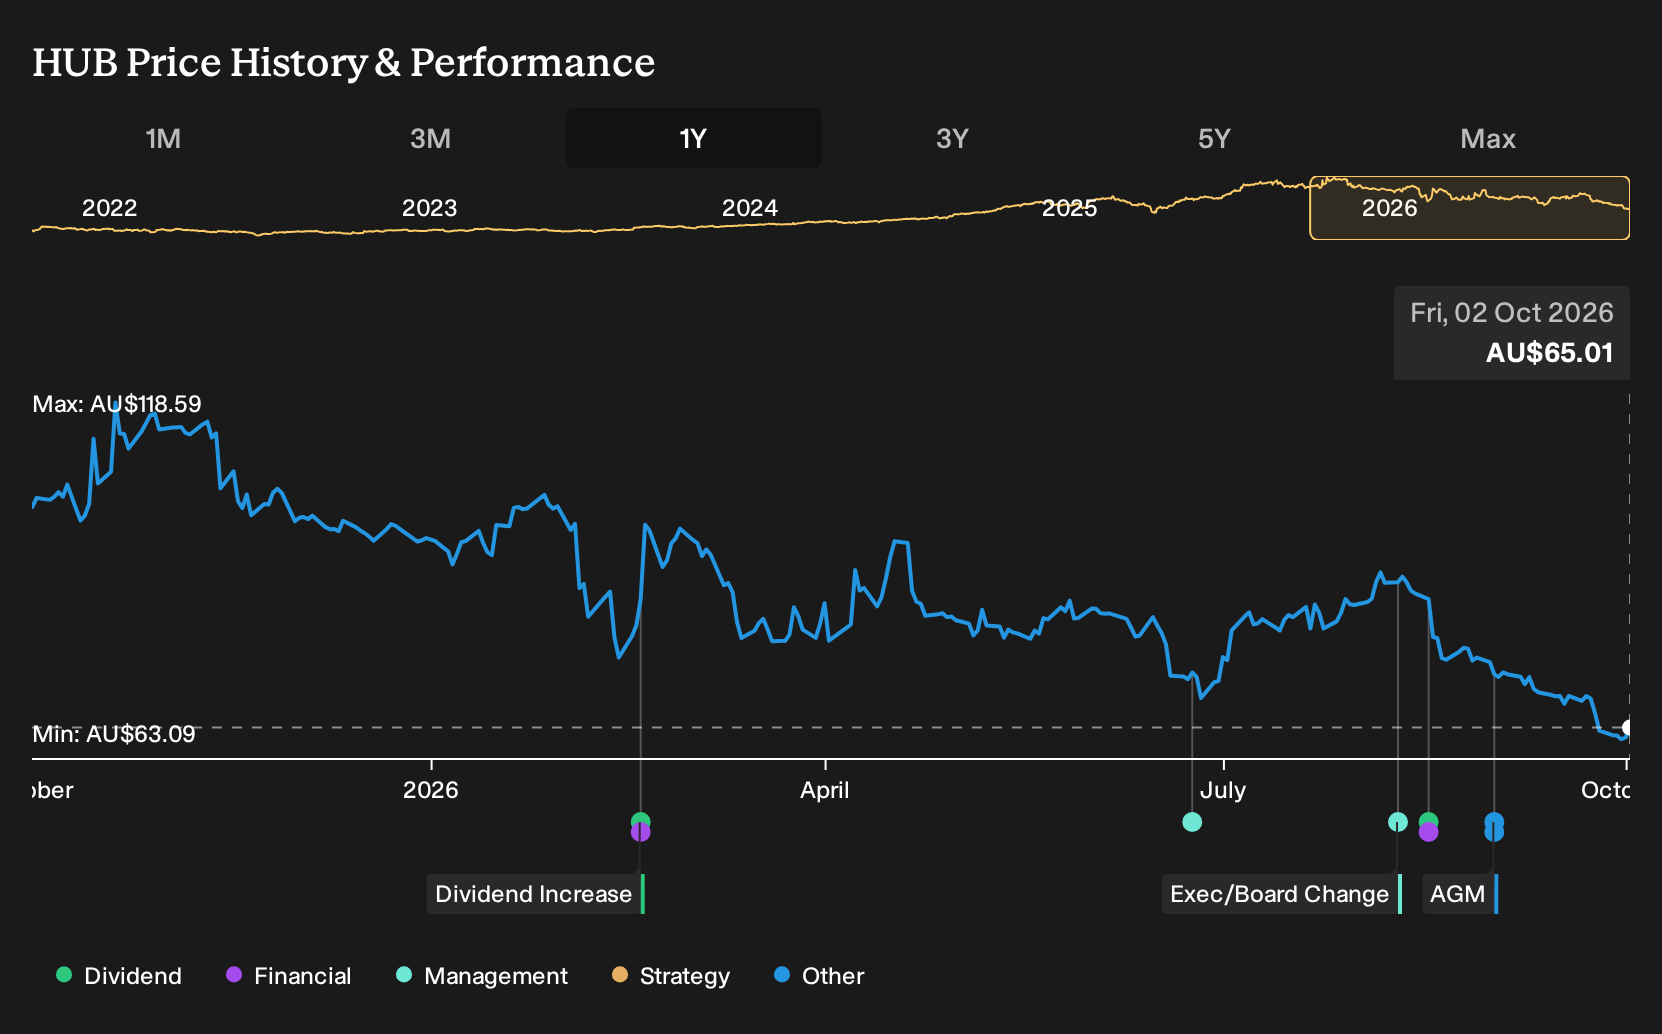
HUB24 has been back in the headlines after a 40% jump in annual profit and a fresh warning from its CEO that growth could slow as higher rates, taxes and global conflicts weigh on inflows. Holding HUB24 over the past year would have meant a 36.2% loss, including dividends. If you had bought on 2 October 2025, after seeing bulls talk up digital adoption and wealth transfer, how do those early expectations stack up against today’s more cautious tone?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
HUB24 has already moved. See which of 5 high quality undervalued stocks still trade below our estimates.
The Two HUB24 Stories Investors Were Weighing
The shares cost A$101 at the start of the period, so anyone looking at HUB24 then had to choose between two very different stories about where things might go next.
The bullish narrative put fair value at A$115, or 13% above the start price. This view hinged on adviser network penetration and digital adoption driving stronger revenue and margin expansion, as well as room for acquisitions funded by a strong balance sheet.
The bearish view anchored fair value at A$40, or 61% below the start price. This perspective focused on rising digital competitors, fee pressure, and heavier regulation potentially squeezing HUB24's profitability over time.
What The HUB24 Results Actually Tested
HUB24 reported total revenue of A$252.947m and net income of A$60.504m in H2 2026, with net margin rising to 23.9%. That supported the optimistic story that stronger economics were possible. The cautionary case still mattered though, as APRA licence conditions and a trading update that coincided with a 52 week low reminded investors that regulatory and inflow risks had not gone away. Overall, the evidence cut both ways.
The key assumption here was profitability resilience. For a different platform stock, investors would watch whether net income and margin, not just funds under administration headlines, are tracking the story management presented at the outset.
What HUB24's Lower Price Now Asks You To Believe
HUB24 trades at A$65.01 today. The selected Narrative places its Fair Value above that level, arguing the current quote does not fully reflect what a larger adviser base and a more embedded technology platform could mean for earnings power.
If you are weighing the 36.2% loss over the past year, the key question is whether adviser adoption and technology-led efficiency gains can outweigh competition, cost pressure and market swings strongly enough to justify paying today's price.
"The strategic positioning of HUB24 as a market leader with strong growth in funds under administration (FUA) suggests potential for ongoing revenue growth, as indicated by a 4-year CAGR of 42% in group revenue. This is complemented by a substantial increase in market share from 6.6% to 7.9% over the last 12 months."
The price and this Narrative do not agree. → Uncover what this Narrative says HUB24 is actually worth
Looking Beyond HUB24's Platform
HUB24 lives where advisers manage wealth. You can also look where that wealth actually moves.
Every portfolio on a platform still needs payment rails to move money securely and consistently.
Behind those transfers sits an operator that routes card spending and business payments worldwide.
It does not lend and instead focuses on a small cut from each transaction.
If advisers win more clients on HUB24, how might these payment toll collectors quietly benefit?
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 36% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com