
How Investors May Respond To Freddie Mac Stock As 30 Year Mortgage Rates Rise
- Freddie Mac reported in its latest Primary Mortgage Market Survey that the average 30 year fixed rate mortgage recently stood at 7.28%, with management commentary indicating the housing market continues to be supported by broader economic conditions despite this higher rate level.
- The updated mortgage rate data matters for Federal Home Loan Mortgage because it directly links funding costs, borrower affordability and potential future refinancing volumes across its US$3.7b plus single family and multifamily credit exposure.
- We will now see how Freddie Mac's investment narrative could be affected by higher 30 year mortgage rates in its latest survey.
Scan how Federal Home Loan Mortgage stacks up against other housing exposed opportunities by reviewing carefully filtered list of solid balance sheet and fundamentals (26 results) aligned with higher for longer mortgage rates.
Federal Home Loan Mortgage Investment Narrative Recap
To own Federal Home Loan Mortgage, you need to be comfortable with a housing finance utility that operates on thin margins, under heavy regulation, and with a very large credit book of more than US$3.7 billion. The short-term swing factor is how single-family and multifamily volumes hold up as mortgage rates stay closer to 7% on the 30-year. The latest survey read-across is more about affordability than about headline sentiment.
The biggest immediate risk remains a prolonged period of elevated or choppy rates that keeps refinance activity muted and limits fee and interest income. Higher 30-year rates also make prior assumptions on house prices and credit reserves more important, because any reset there could feed back into earnings pressure and capital build.
Recent commentary around the Primary Mortgage Market Survey is directly relevant because Freddie Mac’s model ties funding costs, borrower affordability, and guarantee fee potential together. A 7.28% average 30-year rate implies fewer easy refinancing opportunities, so the focus shifts toward the quality and mix of new originations and how efficiently Federal Home Loan Mortgage prices credit risk.
For catalysts, that puts more weight on the existing drivers in the narrative. The pivot toward fully guaranteed multifamily securitizations, high average borrower credit scores, and the roll-out of VantageScore 4.0 matter more when volumes are harder to come by. Execution on these levers can influence how well the business absorbs a period of higher-for-longer mortgage rates without eroding its housing mission or balance sheet flexibility.
Federal Home Loan Mortgage's current analyst story points to revenues of US$23.7b and earnings of US$0.0 thousand by 2029, based on an assumed 1.2% yearly revenue growth rate and a move from a loss of US$24.0m in earnings today to that breakeven level over the same period.
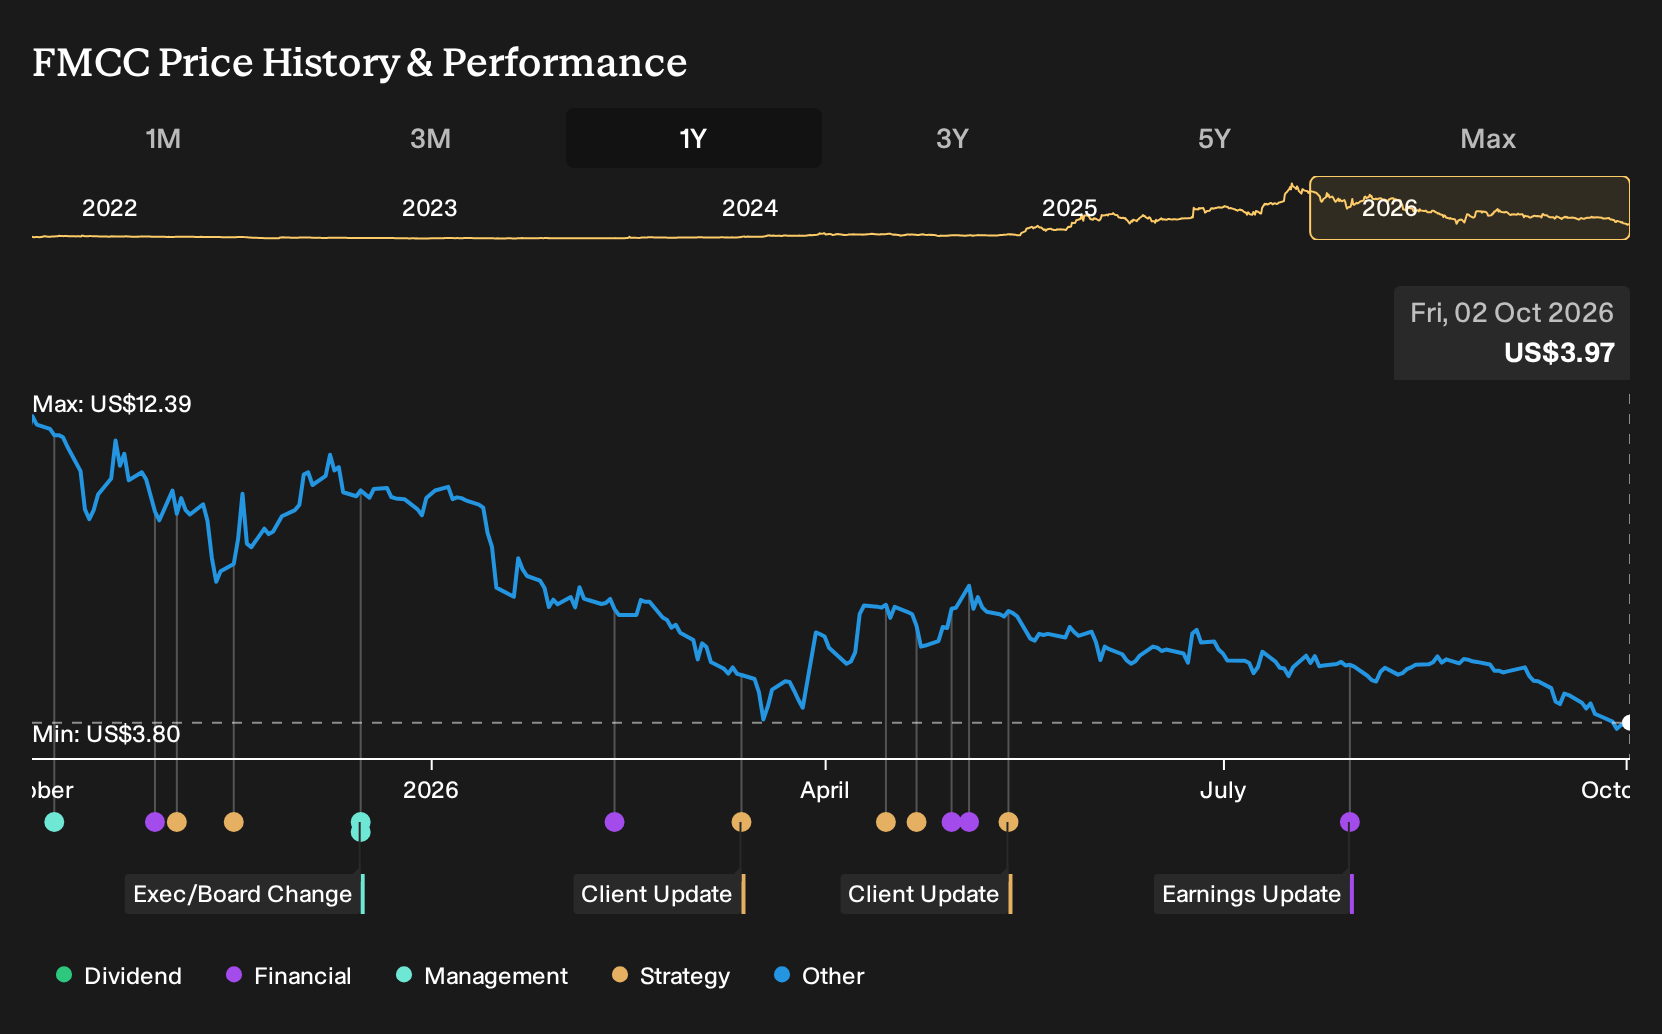
Uncover why Federal Home Loan Mortgage's fair value indicates a 270% potential upside to its current price. This discount could narrow quickly as sentiment shifts.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span a wide band, from about US$12.13 to roughly US$47.12 per Federal Home Loan Mortgage share. This shows how far apart retail views can sit. These opinions pre date the 7.28% mortgage rate print, so reassess them alongside refinancing risks and housing policy catalysts before forming your own stance.
Explore 3 other Federal Home Loan Mortgage fair value estimates, including one that suggests as much as 1087% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Federal Home Loan Mortgage research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Federal Home Loan Mortgage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Federal Home Loan Mortgage's overall financial health at a glance.
Looking for more Federal Home Loan Mortgage investment ideas?
If Federal Home Loan Mortgage has you thinking more broadly about housing, credit and income resilience, use the Simply Wall St screener to line up a wider watchlist that fits your own risk and return preferences.
- For investors who want strong finances to do more of the heavy lifting in tougher conditions, review the list of solid balance sheet and fundamentals (26 results) and see which businesses pair resilient balance sheets with solid fundamentals.
- If value is your priority and you want to focus on companies that currently screen as high quality yet priced at a discount, check out the 31 high quality undervalued stocks that meet those criteria.
- For those building a portfolio around cash returns, scan the 7 dividend fortresses that combine yields of 5% or more with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com