
3 British Dividend Stocks To Own In October 2026
Eurozone inflation recently moved to a 3 year high, and that puts dependable cash payouts from established European dividend stocks back in the spotlight. When prices feel less predictable, a stream of income that does not depend on selling shares can be particularly attractive. This article looks at three United Kingdom listed companies from a high yield screen and explains why their dividend profiles may appeal to patient investors.
The three high yield stocks covered below are only a starting sample from this dividend idea. The full screen surfaces 59 more companies with similarly interesting income stories that are not included here.
If you want to identify, analyze, and focus on your own highest conviction income plays built around this 3%+ yield theme, head straight into the Dividend Powerhouses (3%+ Yield) screener.
MONY Group (LSE:MONY)
MONY Group runs a portfolio of comparison, cashback and consumer finance platforms in the UK, with its high margin Insurance vertical on MoneySuperMarket providing the most direct link to the Dividend Powerhouses theme through recurring, cash generative lead fees that help support regular payouts.
MONY Group generated £236.9 million from Insurance, £110.5 million from Money, £54.8 million from Home Services and £49.3 million from Cashback, with smaller segment adjustments. All £448.1 million of revenue came from the United Kingdom, and the group carries a market value of about £884.2 million.
For income focused investors, MONY Group earns attention because its insurance comparison engine throws off dependable fee income that can underpin a well covered, growing dividend profile, while the broader portfolio of money, home services and cashback sites adds extra cash flow depth.
"The ongoing investment in digital and AI-enabled platforms is increasing automation and operational efficiency, evidenced by a 300% improvement in tech productivity and cost reductions from replatforming, which is likely to support sustainable long-term expansion of net margins."
What really matters now is how a single pressure on MONY Group’s revenue mix evolves, because that shift could reshape dividend headroom.
That revenue mix question sits at the heart of what happens next for shareholder income. It is worth reading the full narrative for MONY Group to see how that tension between cash generation and payout ambition might really be evolving in the full narrative for MONY Group.

Lloyds Banking Group (LSE:LLOY)
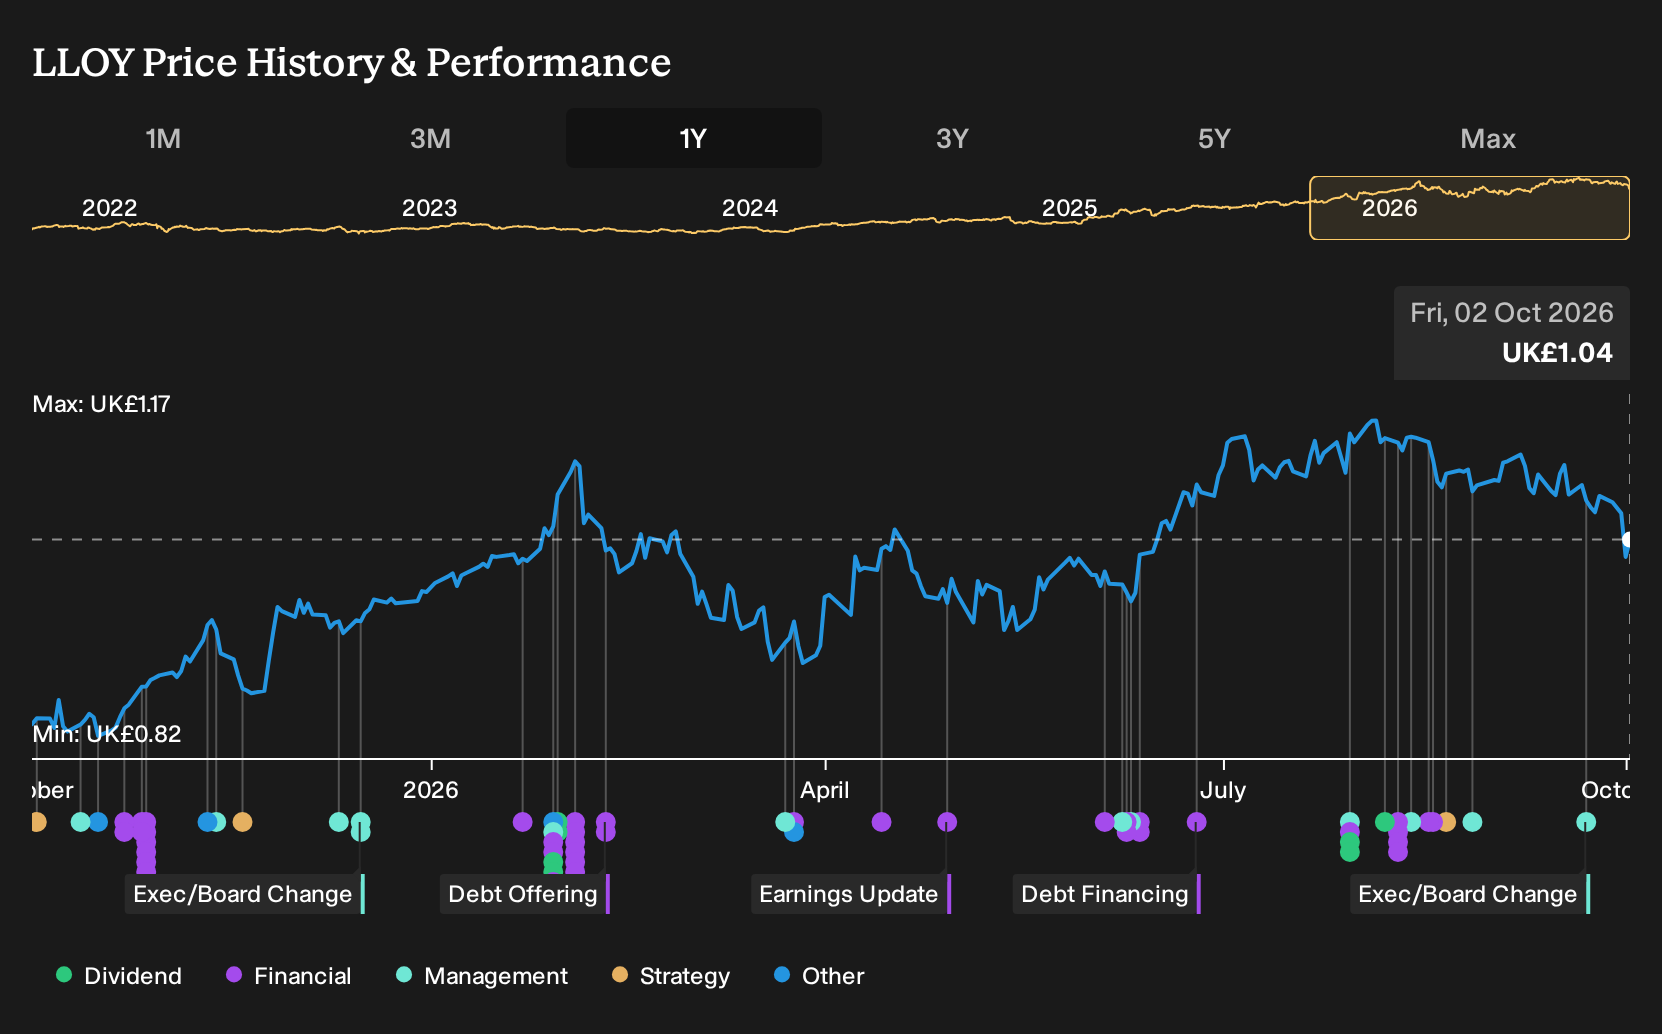
Lloyds Banking Group is a UK focused lender and financial services group where Retail and Commercial Banking cash flow underpins a dividend yield above 3% that fits this income screen, with most revenue coming from Retail, followed by Commercial clients and insurance activities, and a market value near £59.7b.
Lloyds Banking Group turns everyday banking relationships into the kind of recurring cash generation this 3%+ yield screen looks for, with its large deposit base and lending franchise providing the fuel for regular distributions.
"Digital transformation, including expanding mobile-first services for 21 million users, rolling out a new digital remortgage journey, and leveraging AI innovation, continues to drive operating cost reductions and enhances efficiency, positioning the company to support sustained long-term margin expansion and higher earnings."
What happens if a single pressure on loan losses and capital buffers shifts will go a long way to deciding how dependable that income stream feels.
That shift in loan losses and capital buffers is exactly what the full narrative for Lloyds Banking Group unpacks, highlighting where Lloyds Banking Group’s income engine could be accelerating or quietly stalling.
HSBC Holdings (LSE:HSBA)
HSBC Holdings is a global banking group with a long history, but for this 3%+ yield screen the real interest is how its mature Hong Kong and UK retail and wealth franchises turn everyday deposits and fees into steady cash that can support regular dividends.
"The bank is intensifying investment in Asian wealth management and private banking, leveraging a strong brand and local presence in fast-growing wealth markets like Hong Kong, mainland China, and Southeast Asia. This positions HSBC to capture rising affluence and middle class expansion, fueling potential growth in fee income and supporting more resilient earnings and higher margins."
What happens if a single unseen credit cost pressure shifts will play a big role in how secure those future margins feel.
Those credit risks and fee opportunities come together in the full narrative for HSBC Holdings, which maps where HSBC Holdings’ income engine could be accelerating faster than headline numbers suggest.

Seeking Alternatives Before The Crowd?
Fresh stock ideas can move from quiet to flying under momentum while many investors focus on past performance. Consider using available tools early, before opportunities move out of reach.
- Look for resilient balance sheets and cash-rich operators by running the list of solid balance sheet and fundamentals (9 results) while they still trade within your preferred price range.
- Explore fast-moving miners by scanning the 36 elite gold producer stocks while these producers remain less widely followed.
- Track structural shifts in automation by checking the 90 robotics and automation stocks before additional capital competes for the same opportunities and narrows potential entry points.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com