
Is New Regional CMOs Altering The Investment Case For Hims & Hers Stock (HIMS)?
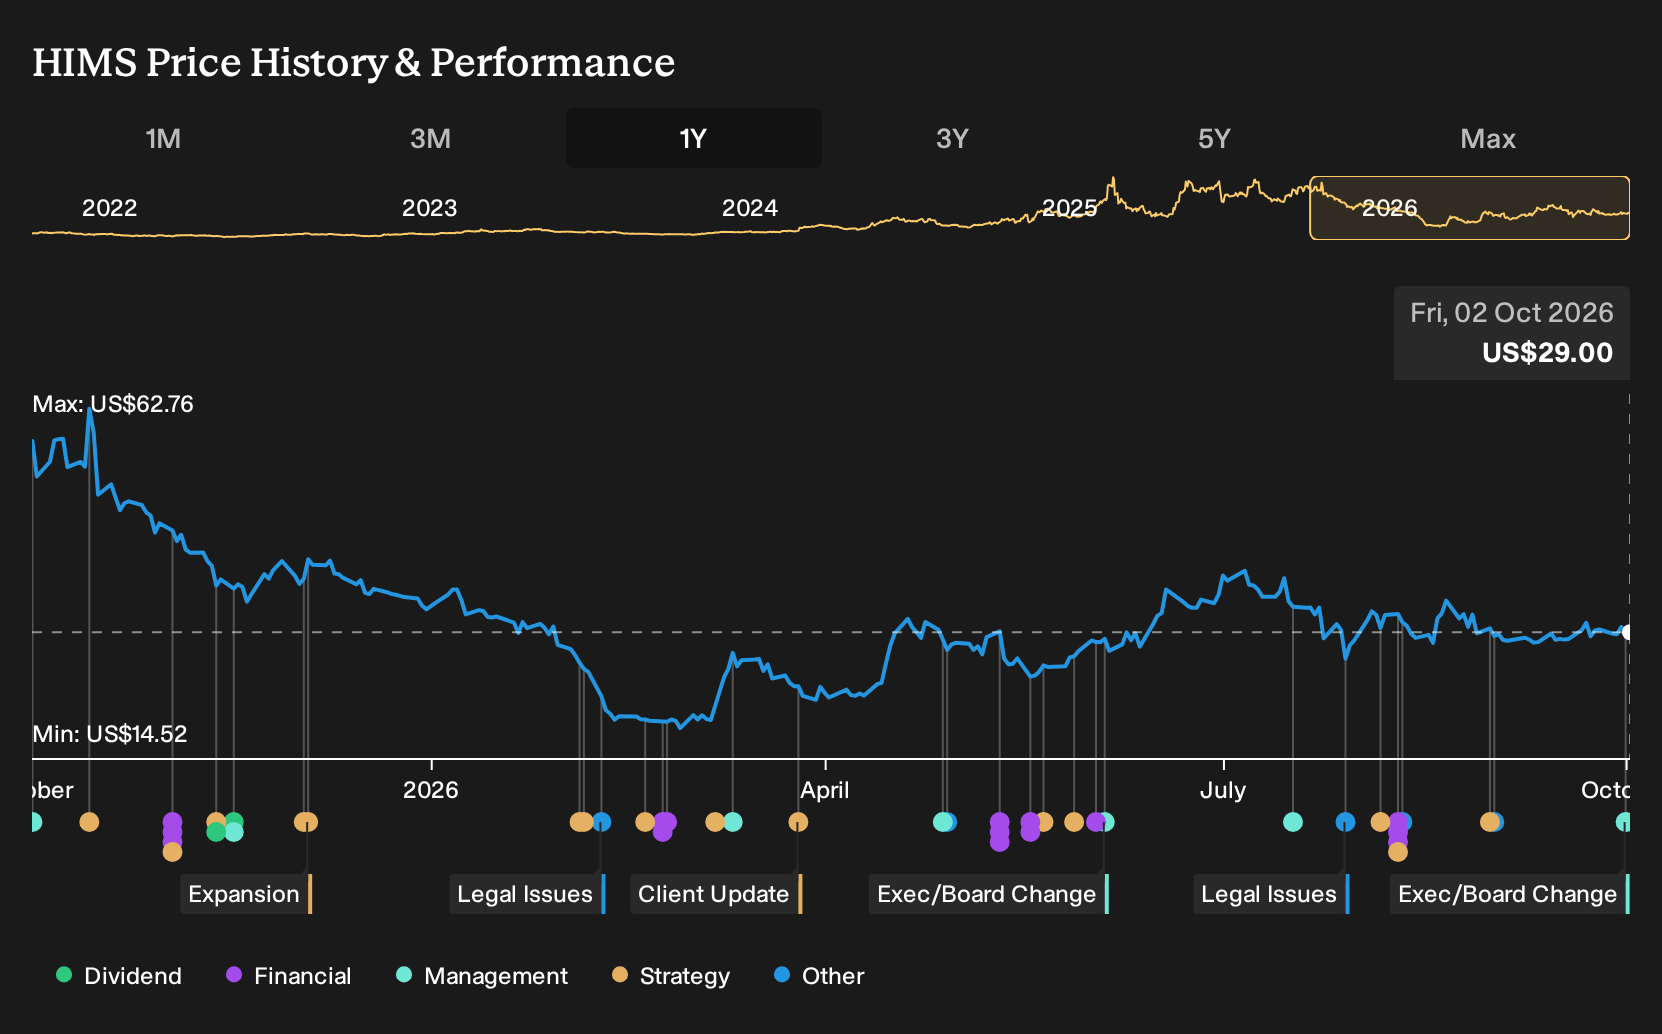
- Hims & Hers Health recently appointed Kultar Garcha as Chief Medical Officer for the UK and EMEA and Matt Vickers as Chief Medical Officer for Australia, expanding local clinical leadership across key international regions.
- The move concentrates experienced physicians on clinical quality, patient safety, and prescribing standards, which directly influences how effectively the business can scale personalized care across multiple markets.
- We will now look at how these new regional Chief Medical Officers could shape the broader investment narrative for Hims & Hers Health.
Scan how Hims & Hers Health fits into the broader push toward digital, clinically led care by comparing it with a curated group of 35 healthcare AI stocks.
Hims & Hers Health Investment Narrative Recap
To own Hims & Hers Health, you need to believe it can turn its telehealth reach into durable subscription style relationships across multiple conditions and geographies, while eventually turning current losses of about US$142 million into profits. In the short term, the key factor remains execution in weight loss and daily care programs, where demand, regulation, and competition can shift quickly.
The new regional Chief Medical Officers should help clinical quality in the UK, EMEA, and Australia but do not fundamentally change the main near term catalyst. That catalyst is whether newer categories like hormonal health and at home labs deepen engagement. The biggest risk still sits with international expansion complexity and marketing efficiency, where higher compliance or acquisition costs could pressure margins.
The most relevant recent development is the broader international build out of Hims & Hers Health, including its presence in Canada under a dedicated Chief Medical Officer since late 2025. That earlier appointment, together with today’s UK, EMEA, and Australia roles, shows the platform is being run more as a network of locally led medical hubs rather than a single central play.
For you as an investor, that structure matters for both catalysts and risks. Local medical leadership can support tighter prescribing standards, smoother regulatory engagement, and potentially better patient retention in hormonal health, mental health, and weight loss programs. The trade off is more complexity and cost across regions, so the near term focus is whether customer growth and recurring revenue in each new market justify the added overhead.
Hims & Hers Health's current analyst narrative points to revenues of US$4.6b and earnings of US$241.0 million by 2029, built on an assumed 21.6% yearly revenue growth rate and a move from an earnings loss of US$142.0 million today to positive consensus earnings. This implies an earnings swing of about US$383.0 million over that period.
Uncover why Hims & Hers Health's fair value indicates an 8% potential upside to its current price before the discount to Hims & Hers Health closes.
Exploring Other Perspectives
One alternate view on Hims & Hers Health focuses on regulatory and payments scrutiny around weight loss subscriptions. The most bearish analysts had pencilled in revenue of about US$4.1b and earnings of US$163.7 million by 2029, far below the top forecasts. These new clinical appointments could eventually shift those expectations, in either direction.
Explore 17 other Hims & Hers Health fair value estimates, including one that suggests as much as 14% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hims & Hers Health research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hims & Hers Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hims & Hers Health's overall financial health at a glance.
Looking for more investment ideas beyond Hims & Hers Health?
If you want to pressure test your view on Hims & Hers Health, compare it with other companies that share some of the traits you care about, whether that is value, resilience, or balance sheet strength.
- For investors who care most about downside protection, start with companies that rank well on resilience by reviewing 31 resilient stocks with low risk scores.
- If quality at a fair sticker price is your priority, scan a hand picked set of potential value opportunities through 31 high quality undervalued stocks.
- When balance sheet strength is non negotiable, focus on businesses with solid fundamentals by running a search using the list of solid balance sheet and fundamentals (26 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com