
International Seaways (INSW) And The Fleet Renewal Story Following Questions On Valuation
International Seaways (INSW) has drawn attention after a strong run, with the share price closing at US$115.81 on 30 September 2026 after sizeable gains over the past year and the past 3 months.
That recent surge fits into a much longer winning streak for International Seaways, with a year to date share price return of 146.46% and a 1 year total shareholder return of 186.73%. These figures point to strong momentum and a shifting view of its risk and reward profile.
Scan beyond International Seaways and compare its surge with a curated set of other strong movers across our 31 high quality undervalued stocks to see what else fits your playbook.
Bulls see International Seaways as a momentum story backed by current cash flows. Bears point to falling revenue and earnings growth. Which side do the numbers lean toward as you weigh valuation next?
Most Popular Narrative: 8% Overvalued
Against the last close at $115.81, the most followed narrative pegs fair value for International Seaways at $107.17, which frames the recent surge as slightly ahead of that modelled estimate while still anchored in detailed cash flow work and sector assumptions.
The company's strategy of renewing and modernizing its fleet, including the acquisition of newbuild eco-vessels and selling older tonnage, positions it to benefit from stricter environmental regulations, reducing operating costs and supporting sustained or improved net margins. Tightening supply fundamentals are anticipated, as the orderbook fails to keep pace with required fleet replacement. By 2029, nearly 50% of the global fleet will be over 20 years old, likely to be excluded from commercial trade, which could drive up vessel charter rates and future earnings.
See why 57 investors see International Seaways as 8% overvalued.
Result: Fair Value of $107.17 (OVERVALUED)
Still, the narrative can break if global energy transition policies erode long term demand for crude and product shipping, or if tighter regulations sharply raise compliance costs.
Find out about the key risks to this International Seaways narrative.
Another View on International Seaways Valuation
A different lens on International Seaways comes from our DCF model, which points to a future cash flow value of $161.09 per share. That sits well above the current $115.81 price. How comfortable are you with a fair value that depends heavily on long term cash flow assumptions?
Look into how the SWS DCF model arrives at its fair value.
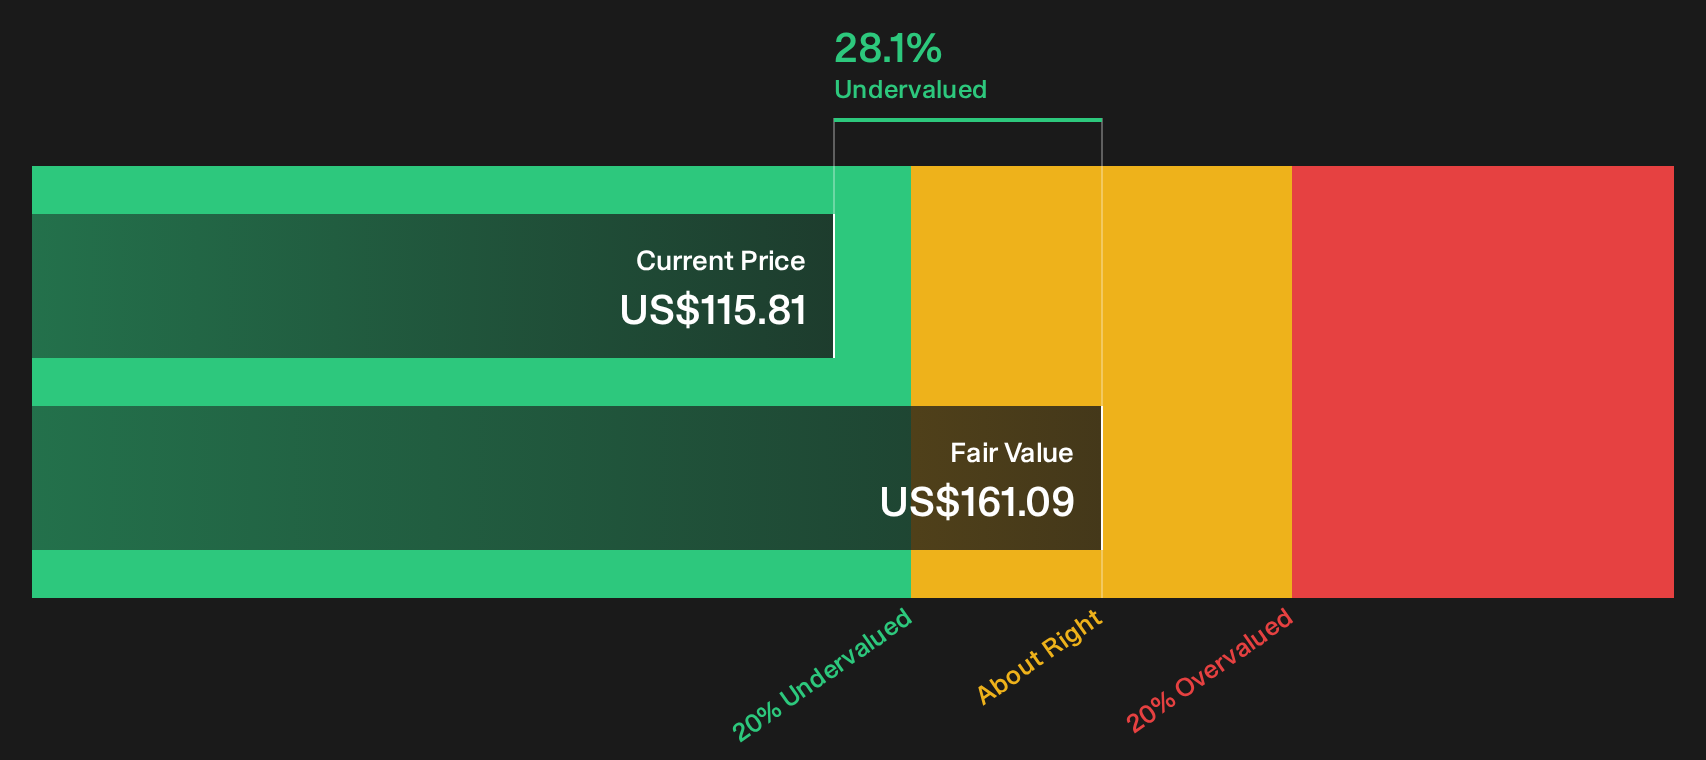
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out International Seaways for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of views are already forming around International Seaways, but your takeaway should be grounded in your own work and urgency. To weigh both concern and optimism in one place, start with our 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond International Seaways?
If International Seaways has caught your attention, do not stop here. Broaden your opportunity set with focused lists that match your style and risk comfort.
- Target resilient income by checking out 7 dividend fortresses to help anchor your portfolio with consistent cash distributions.
- Hunt for stronger balance sheets through our list of solid balance sheet and fundamentals (26 results) and avoid businesses weighed down by fragile finances.
- Spot potential future leaders early by scanning the 19 high quality undiscovered gems before everyone else starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com